Edge16 Oct 2026
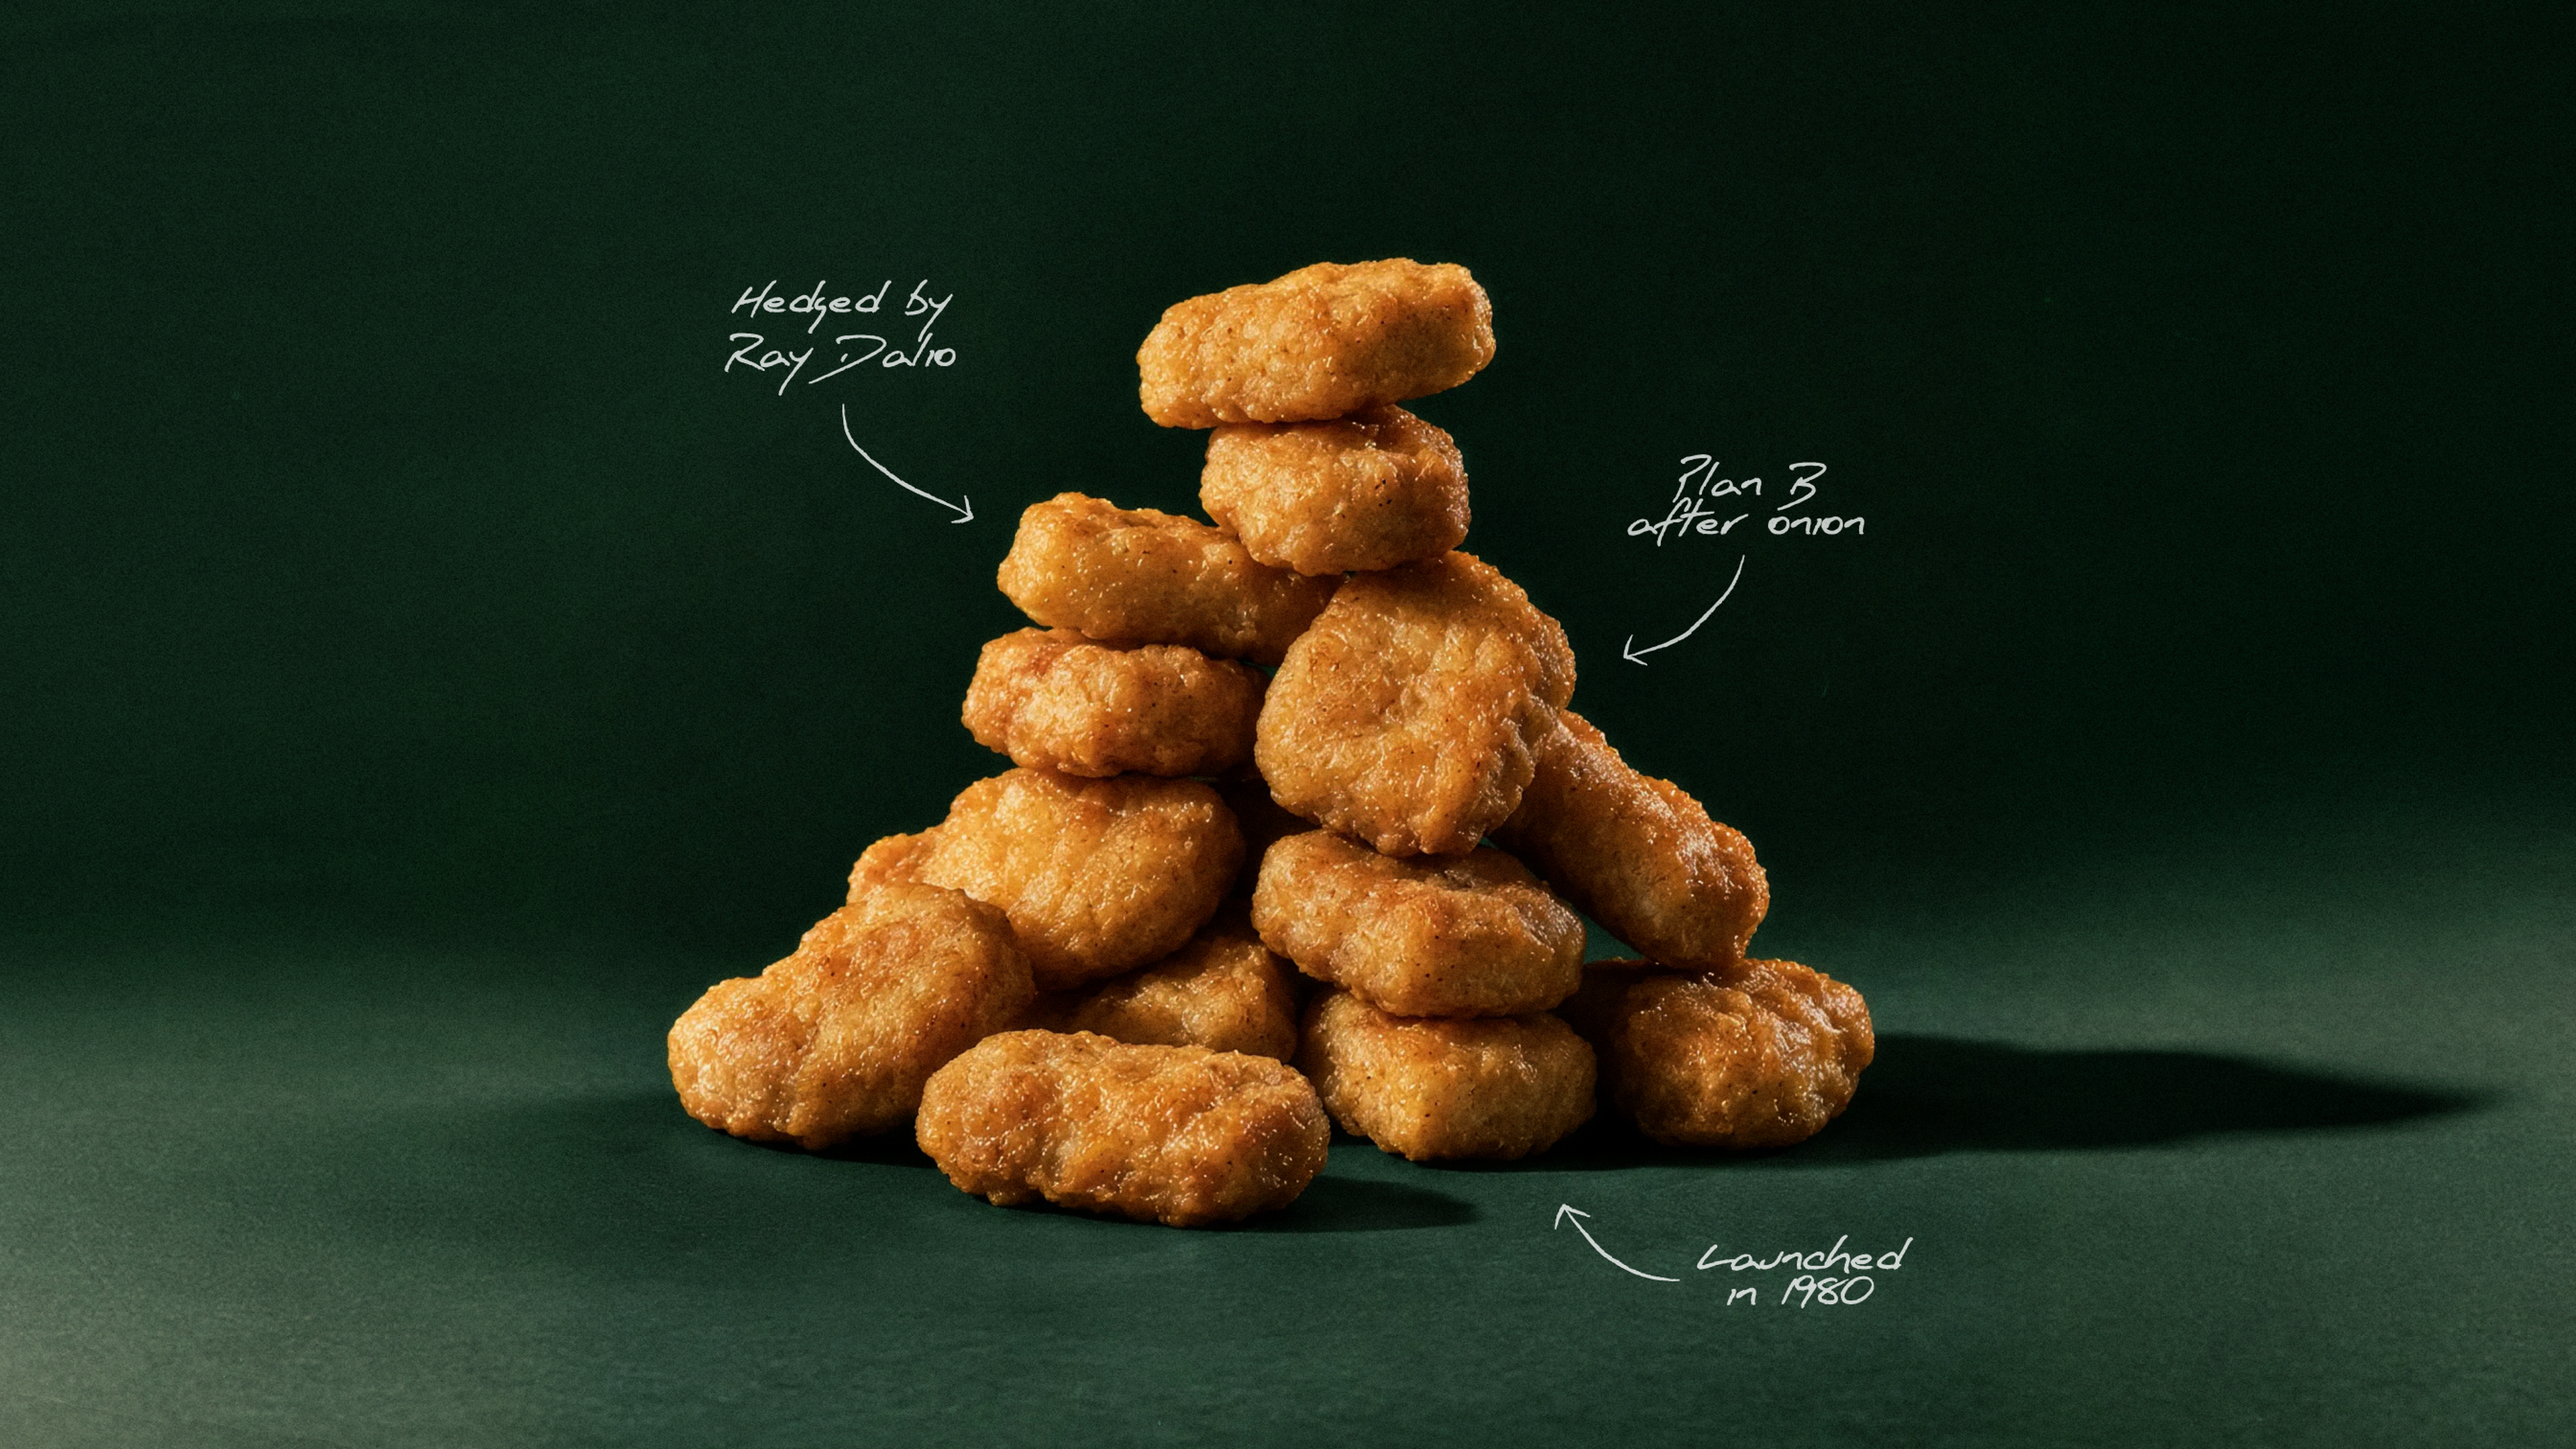
Winner, Winner: The Chicken McNugget Story
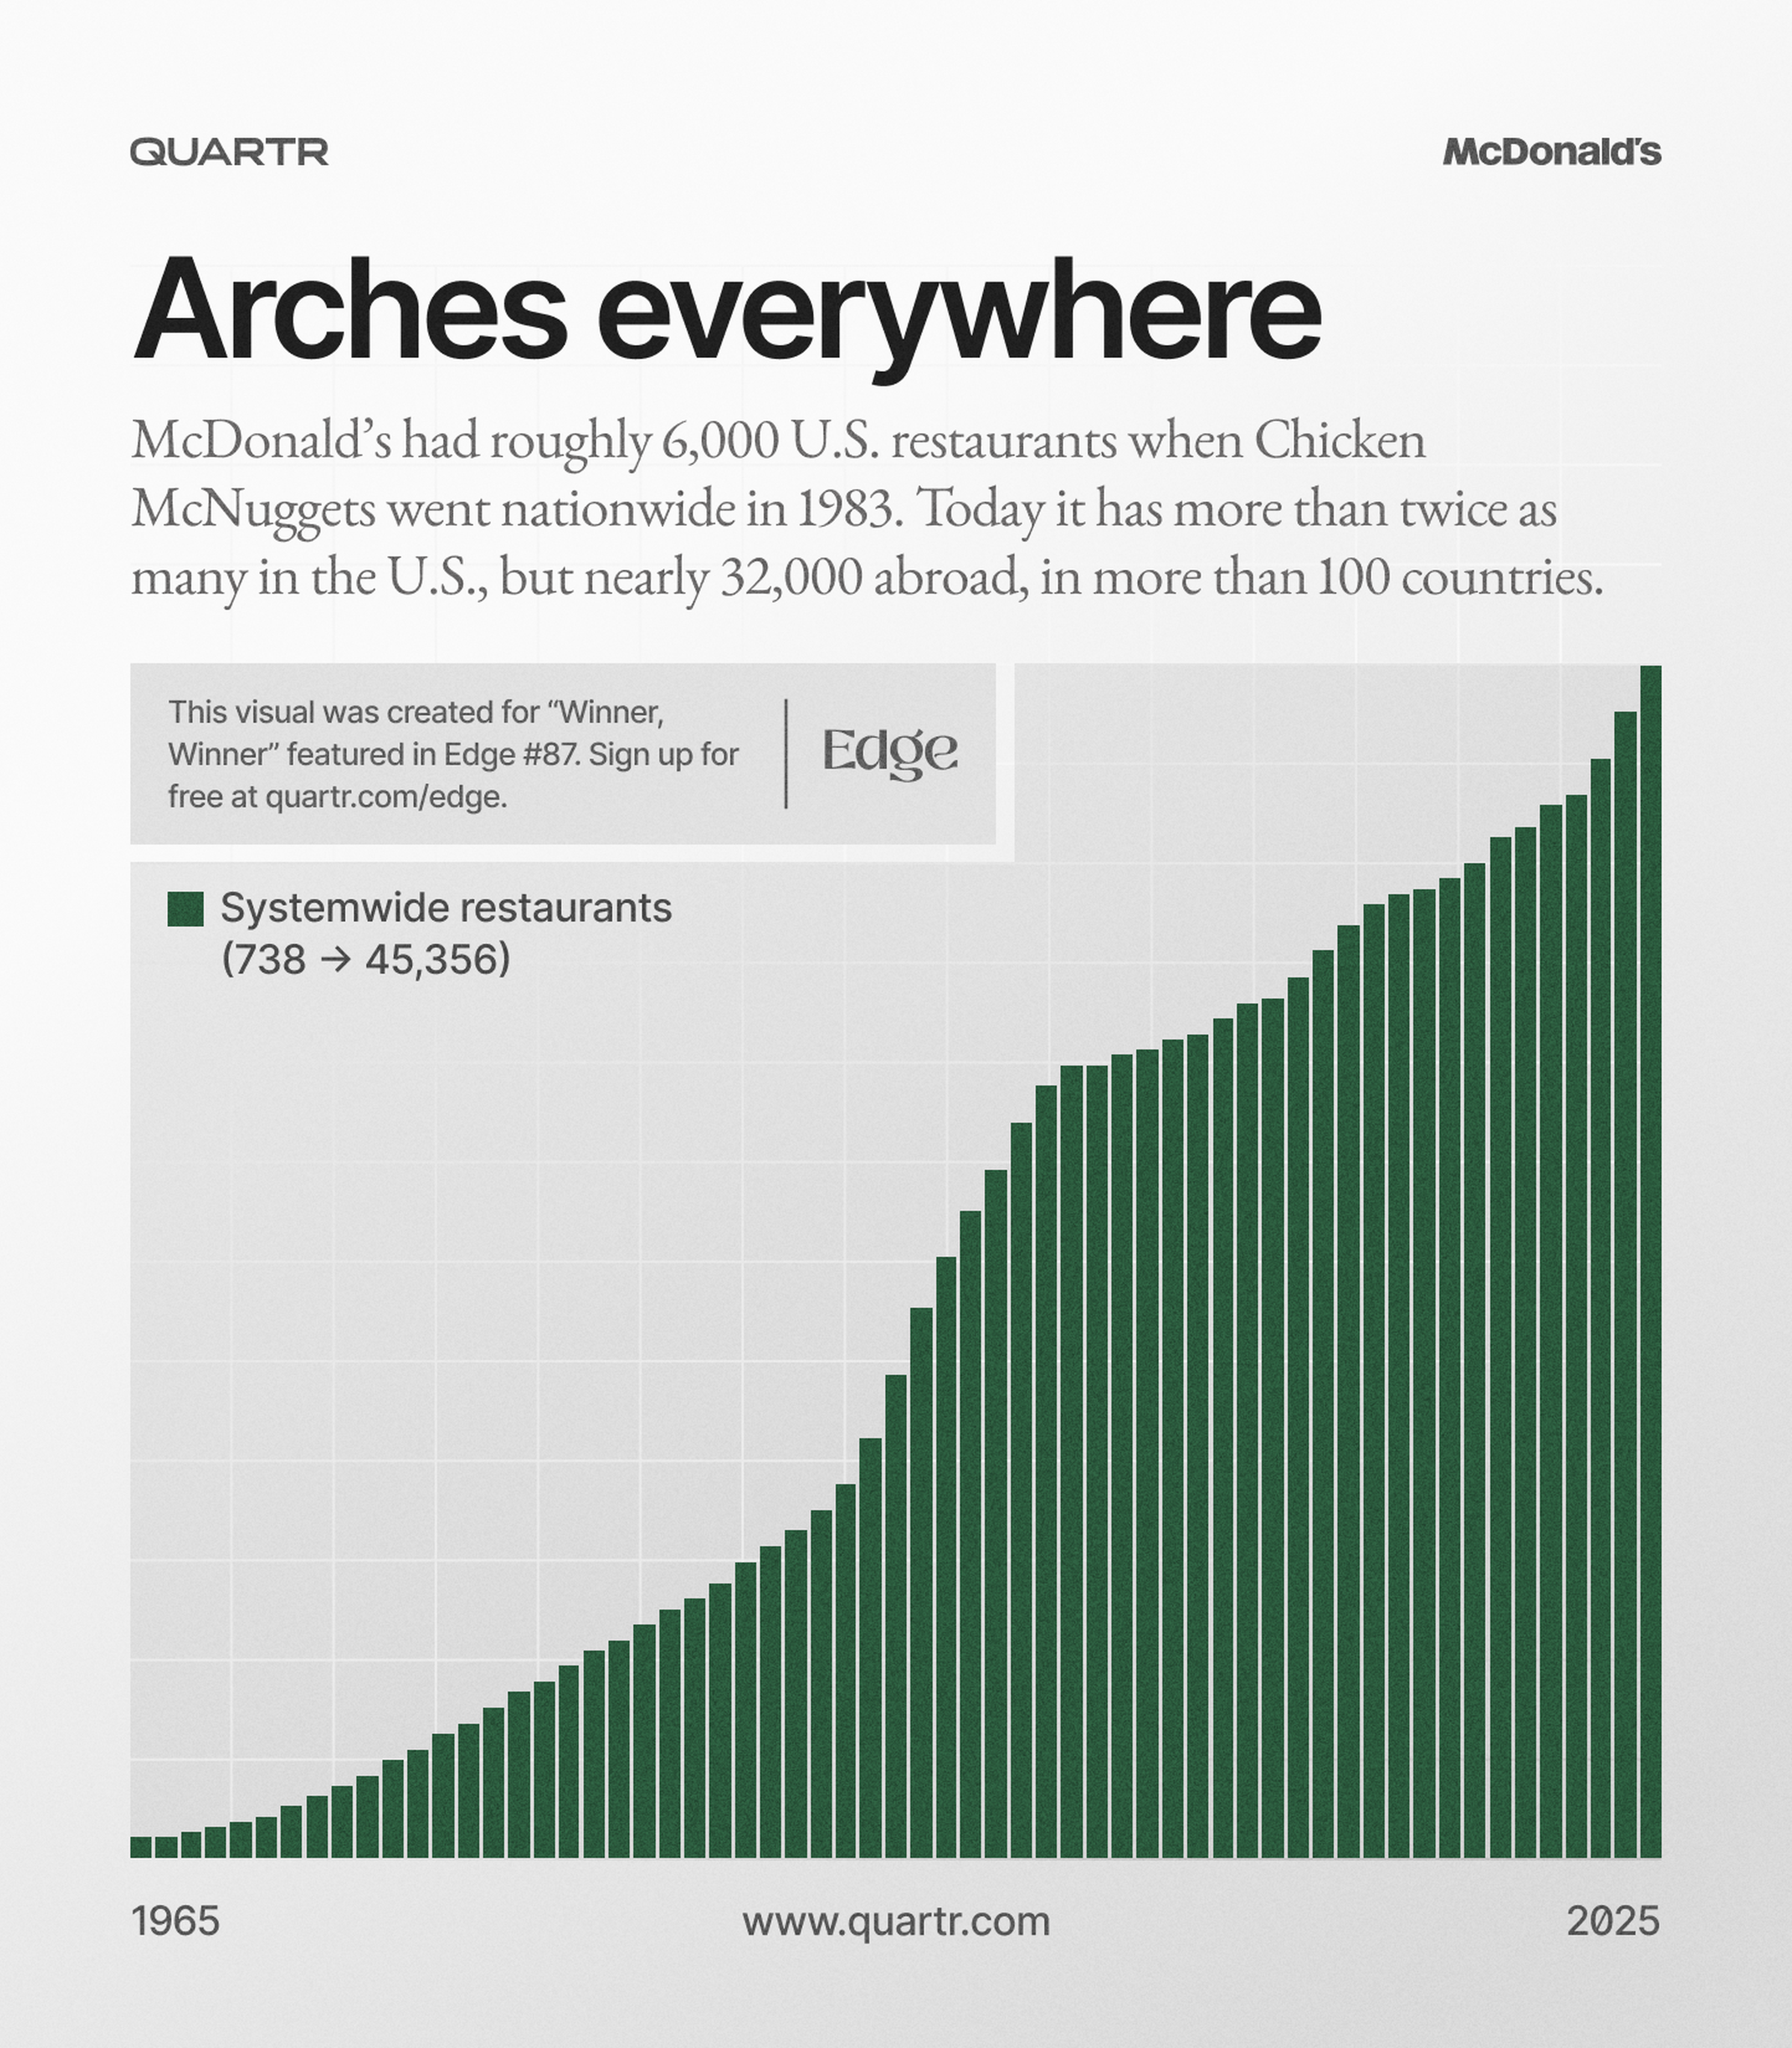
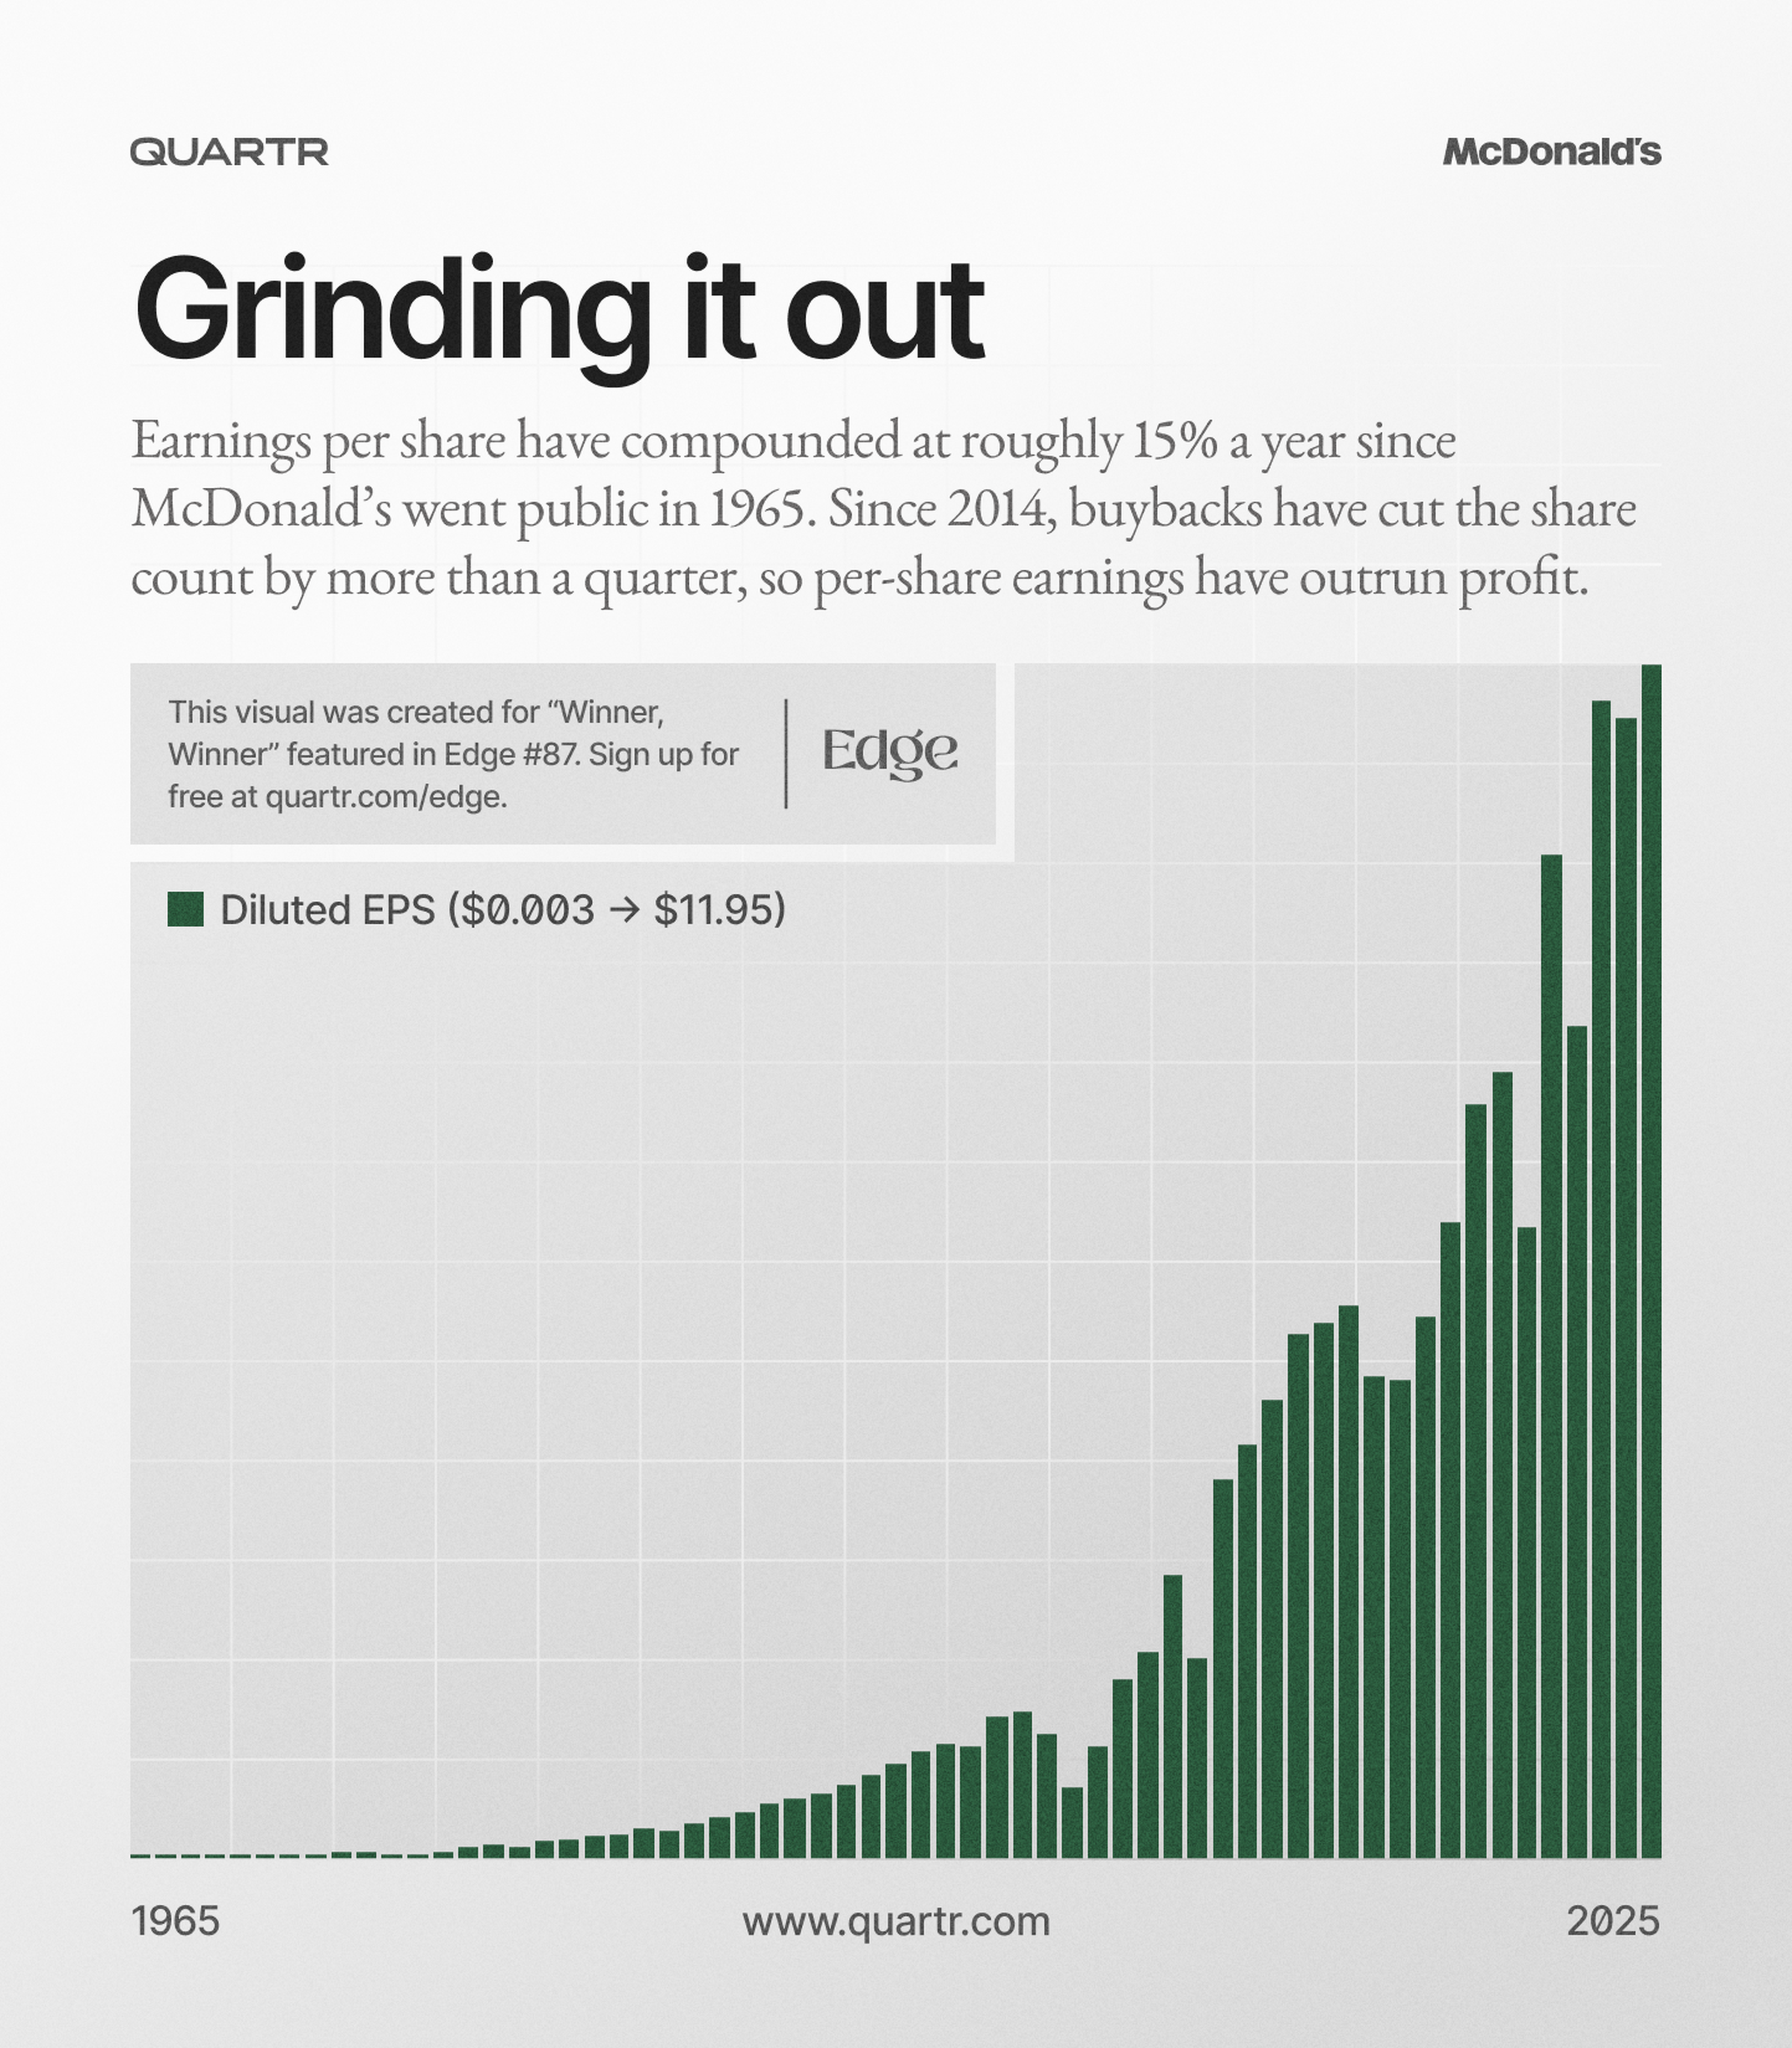
How a 1940s breeding contest, a Cornell food scientist, and a hedge by Ray Dalio helped McDonald's turn the Chicken McNugget into a fast-food icon.

Q2 FY2027 was muted amid deficient, uneven monsoon rainfall, weak channel replenishment and crop-area pressure; H1 revenue and earnings grew modestly.
New-product launches and portfolio-focused execution supported resilience, while elevated inventory, input costs and pricing pressure weighed on performance.
Q2 revenue from operations was INR 858 crore versus INR 861 crore YoY; 5% pricing growth was offset by a similar volume decline.
Q2 EBITDA fell 18% to INR 126 crore from INR 154 crore; PAT declined 17% to INR 85 crore from INR 102 crore.
H1 revenue rose 3% to INR 1,880 crore, EBITDA increased 2% to INR 311 crore and PAT rose 6% to INR 210 crore.
H1 PBT was INR 282 crore versus INR 266 crore; H1 results included a INR 16 crore exceptional gain.
Management expects the next season to be significantly better with normal rainfall and improved crop economics; weather visibility remains limited until March-April.
Rabi prospects depend on winter rainfall, soil moisture and irrigation; reservoir levels were ~70% of capacity versus a 10-year average of 76%.
Capacity utilization is expected to remain broadly stable, with growth from product mix, operating efficiencies and higher-value offerings.
Long-term priorities include portfolio expansion, targeted R&D, cost competitiveness, strategic alliances and custom synthesis.

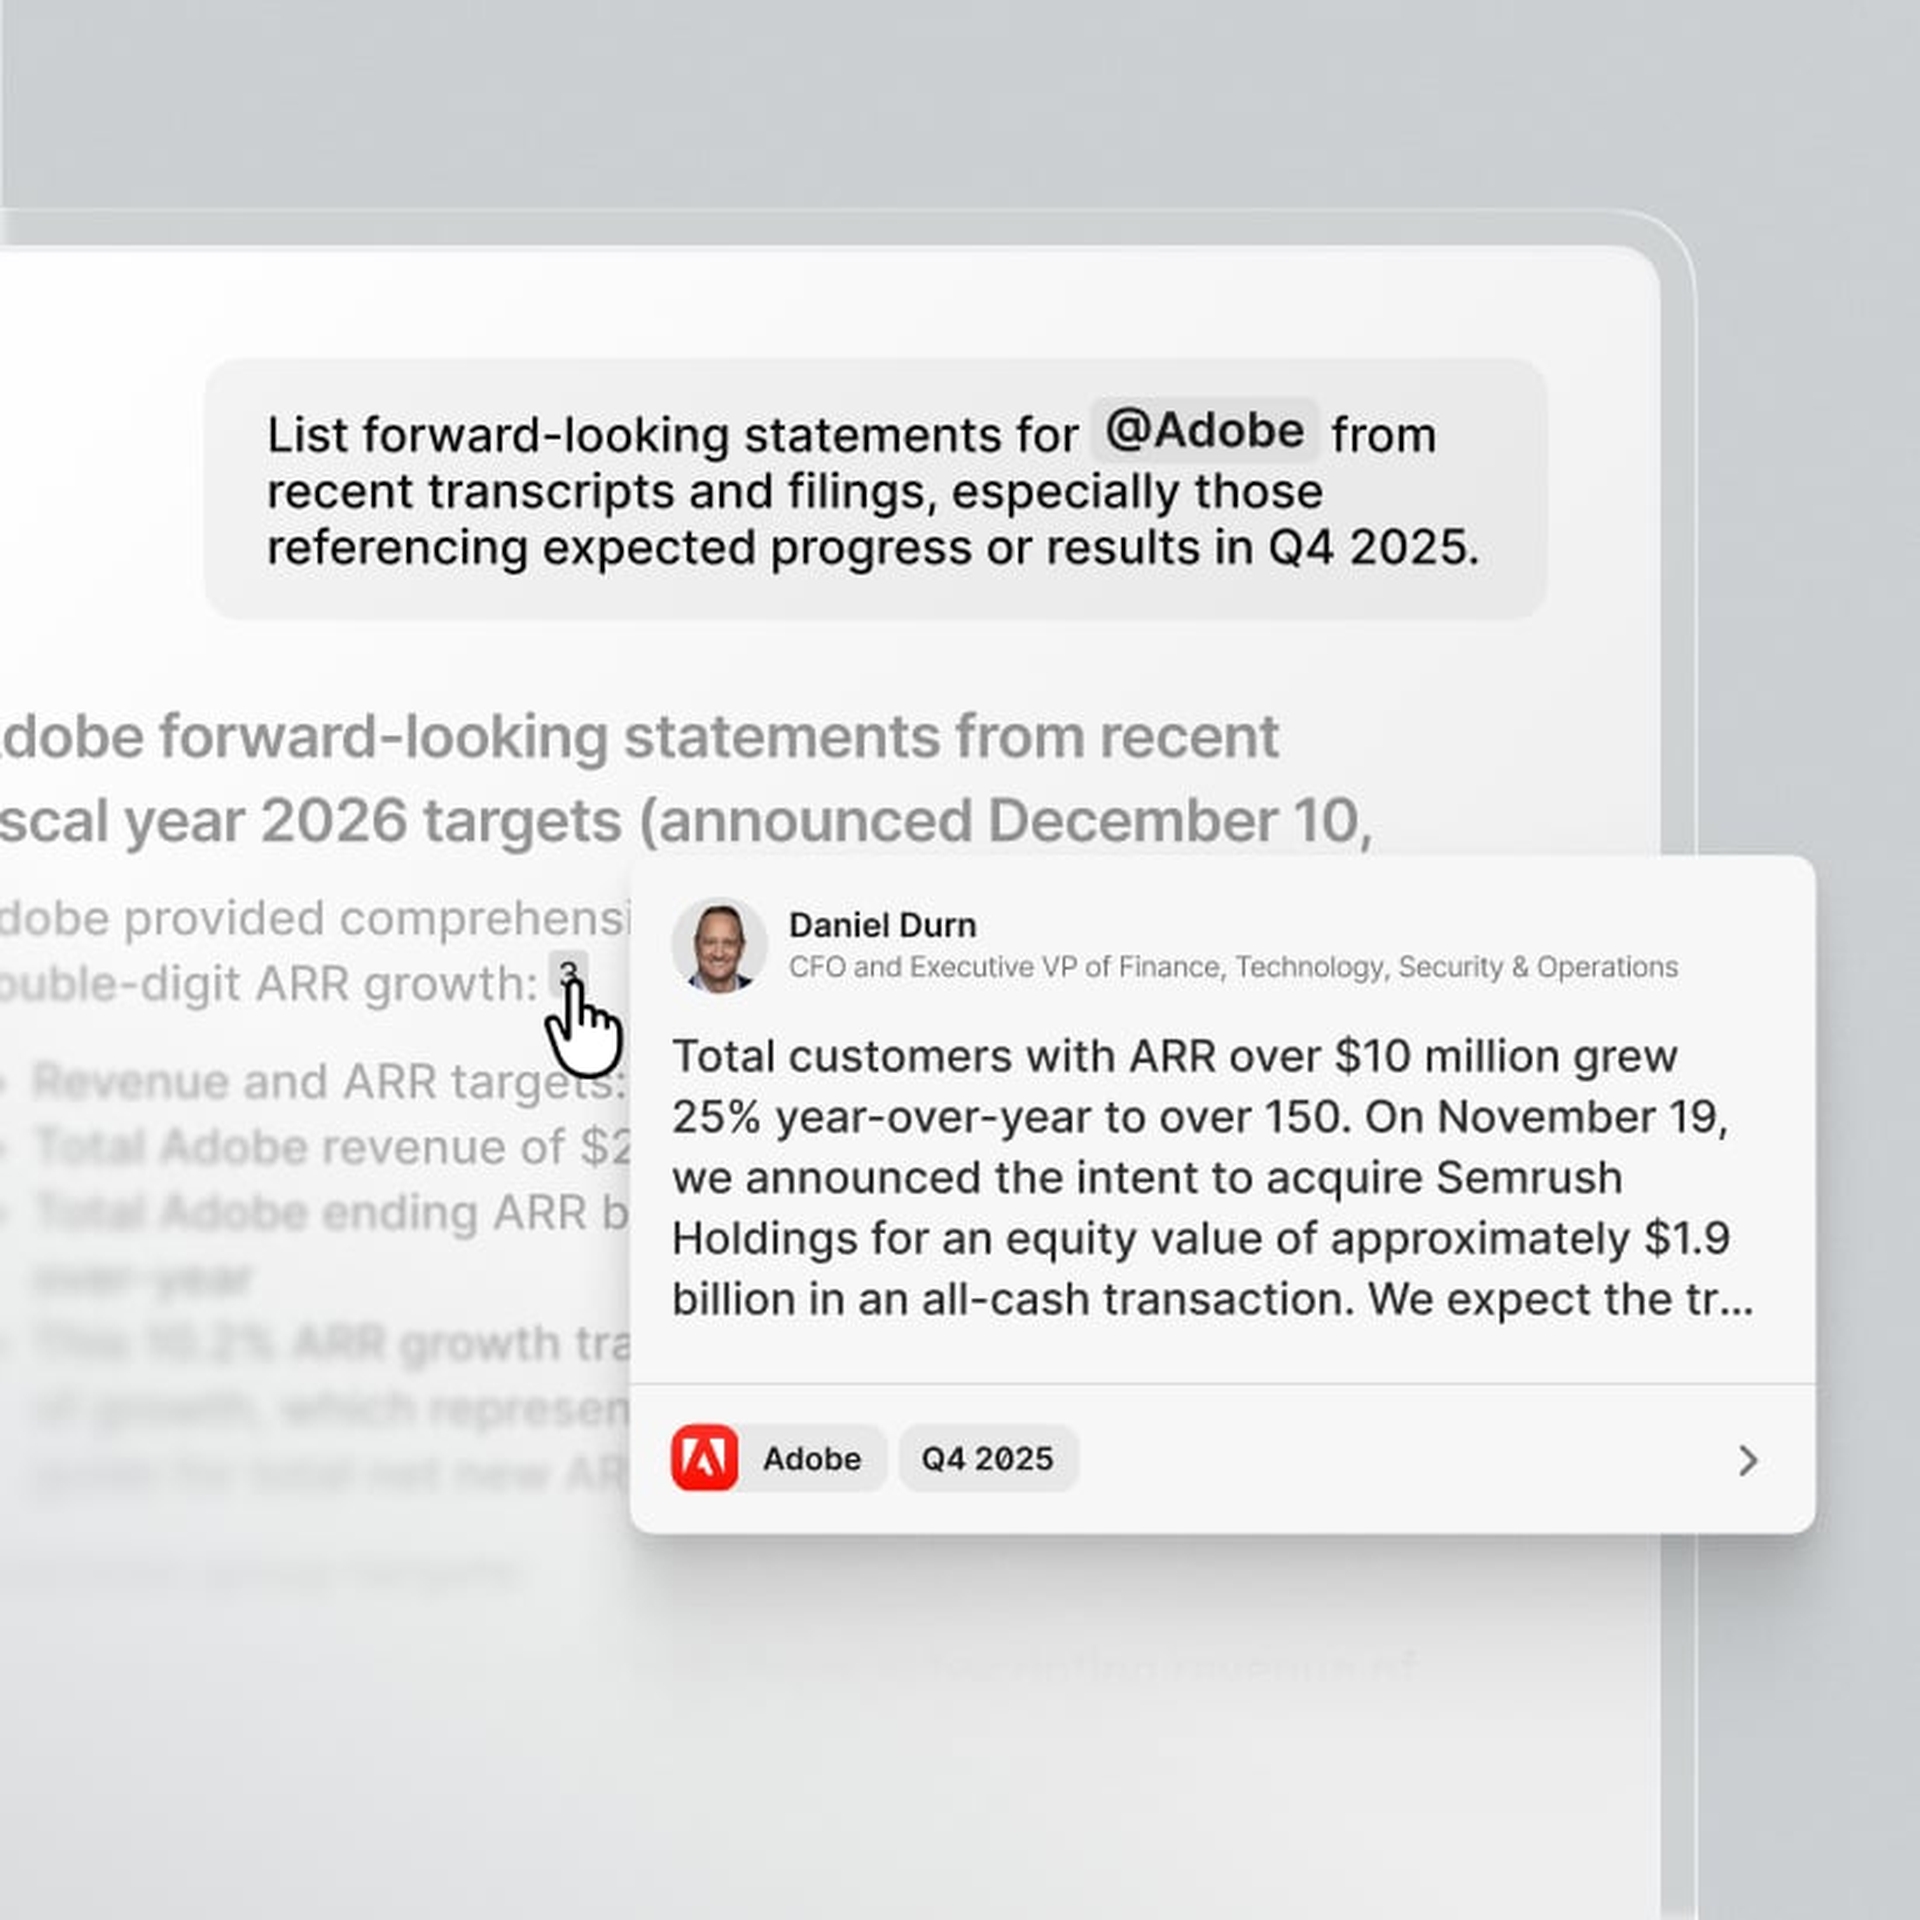
AI chat
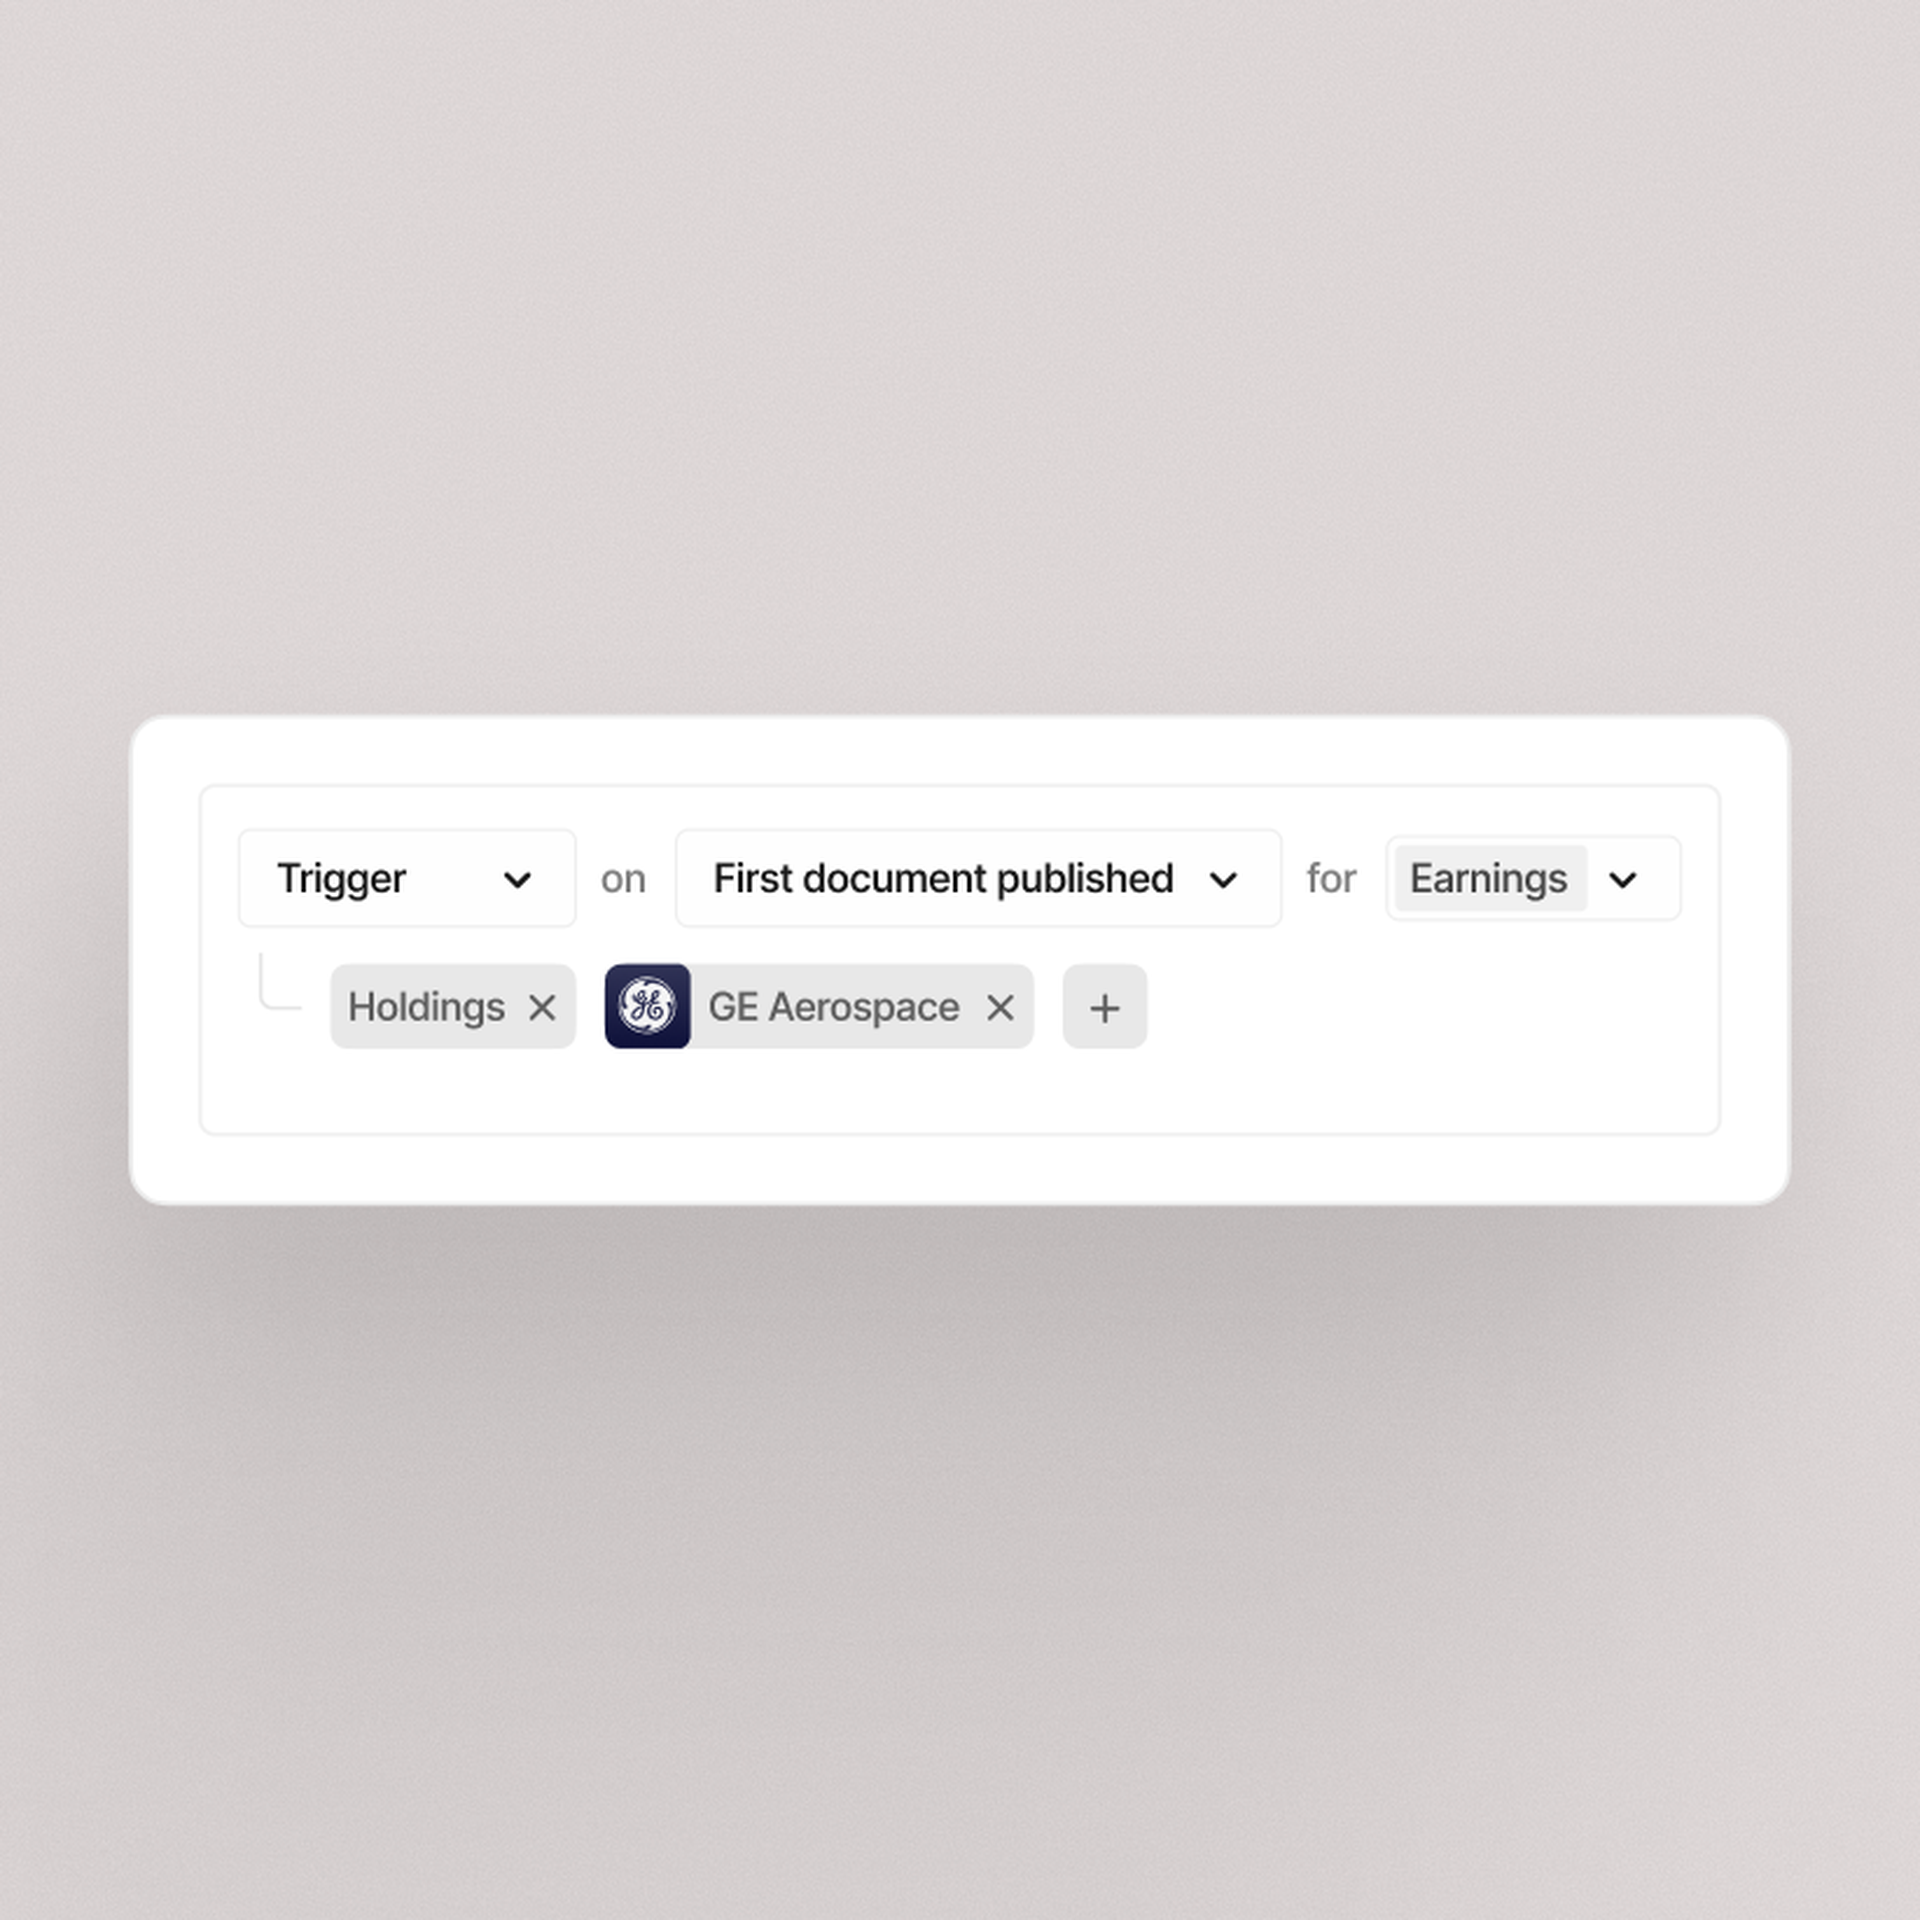
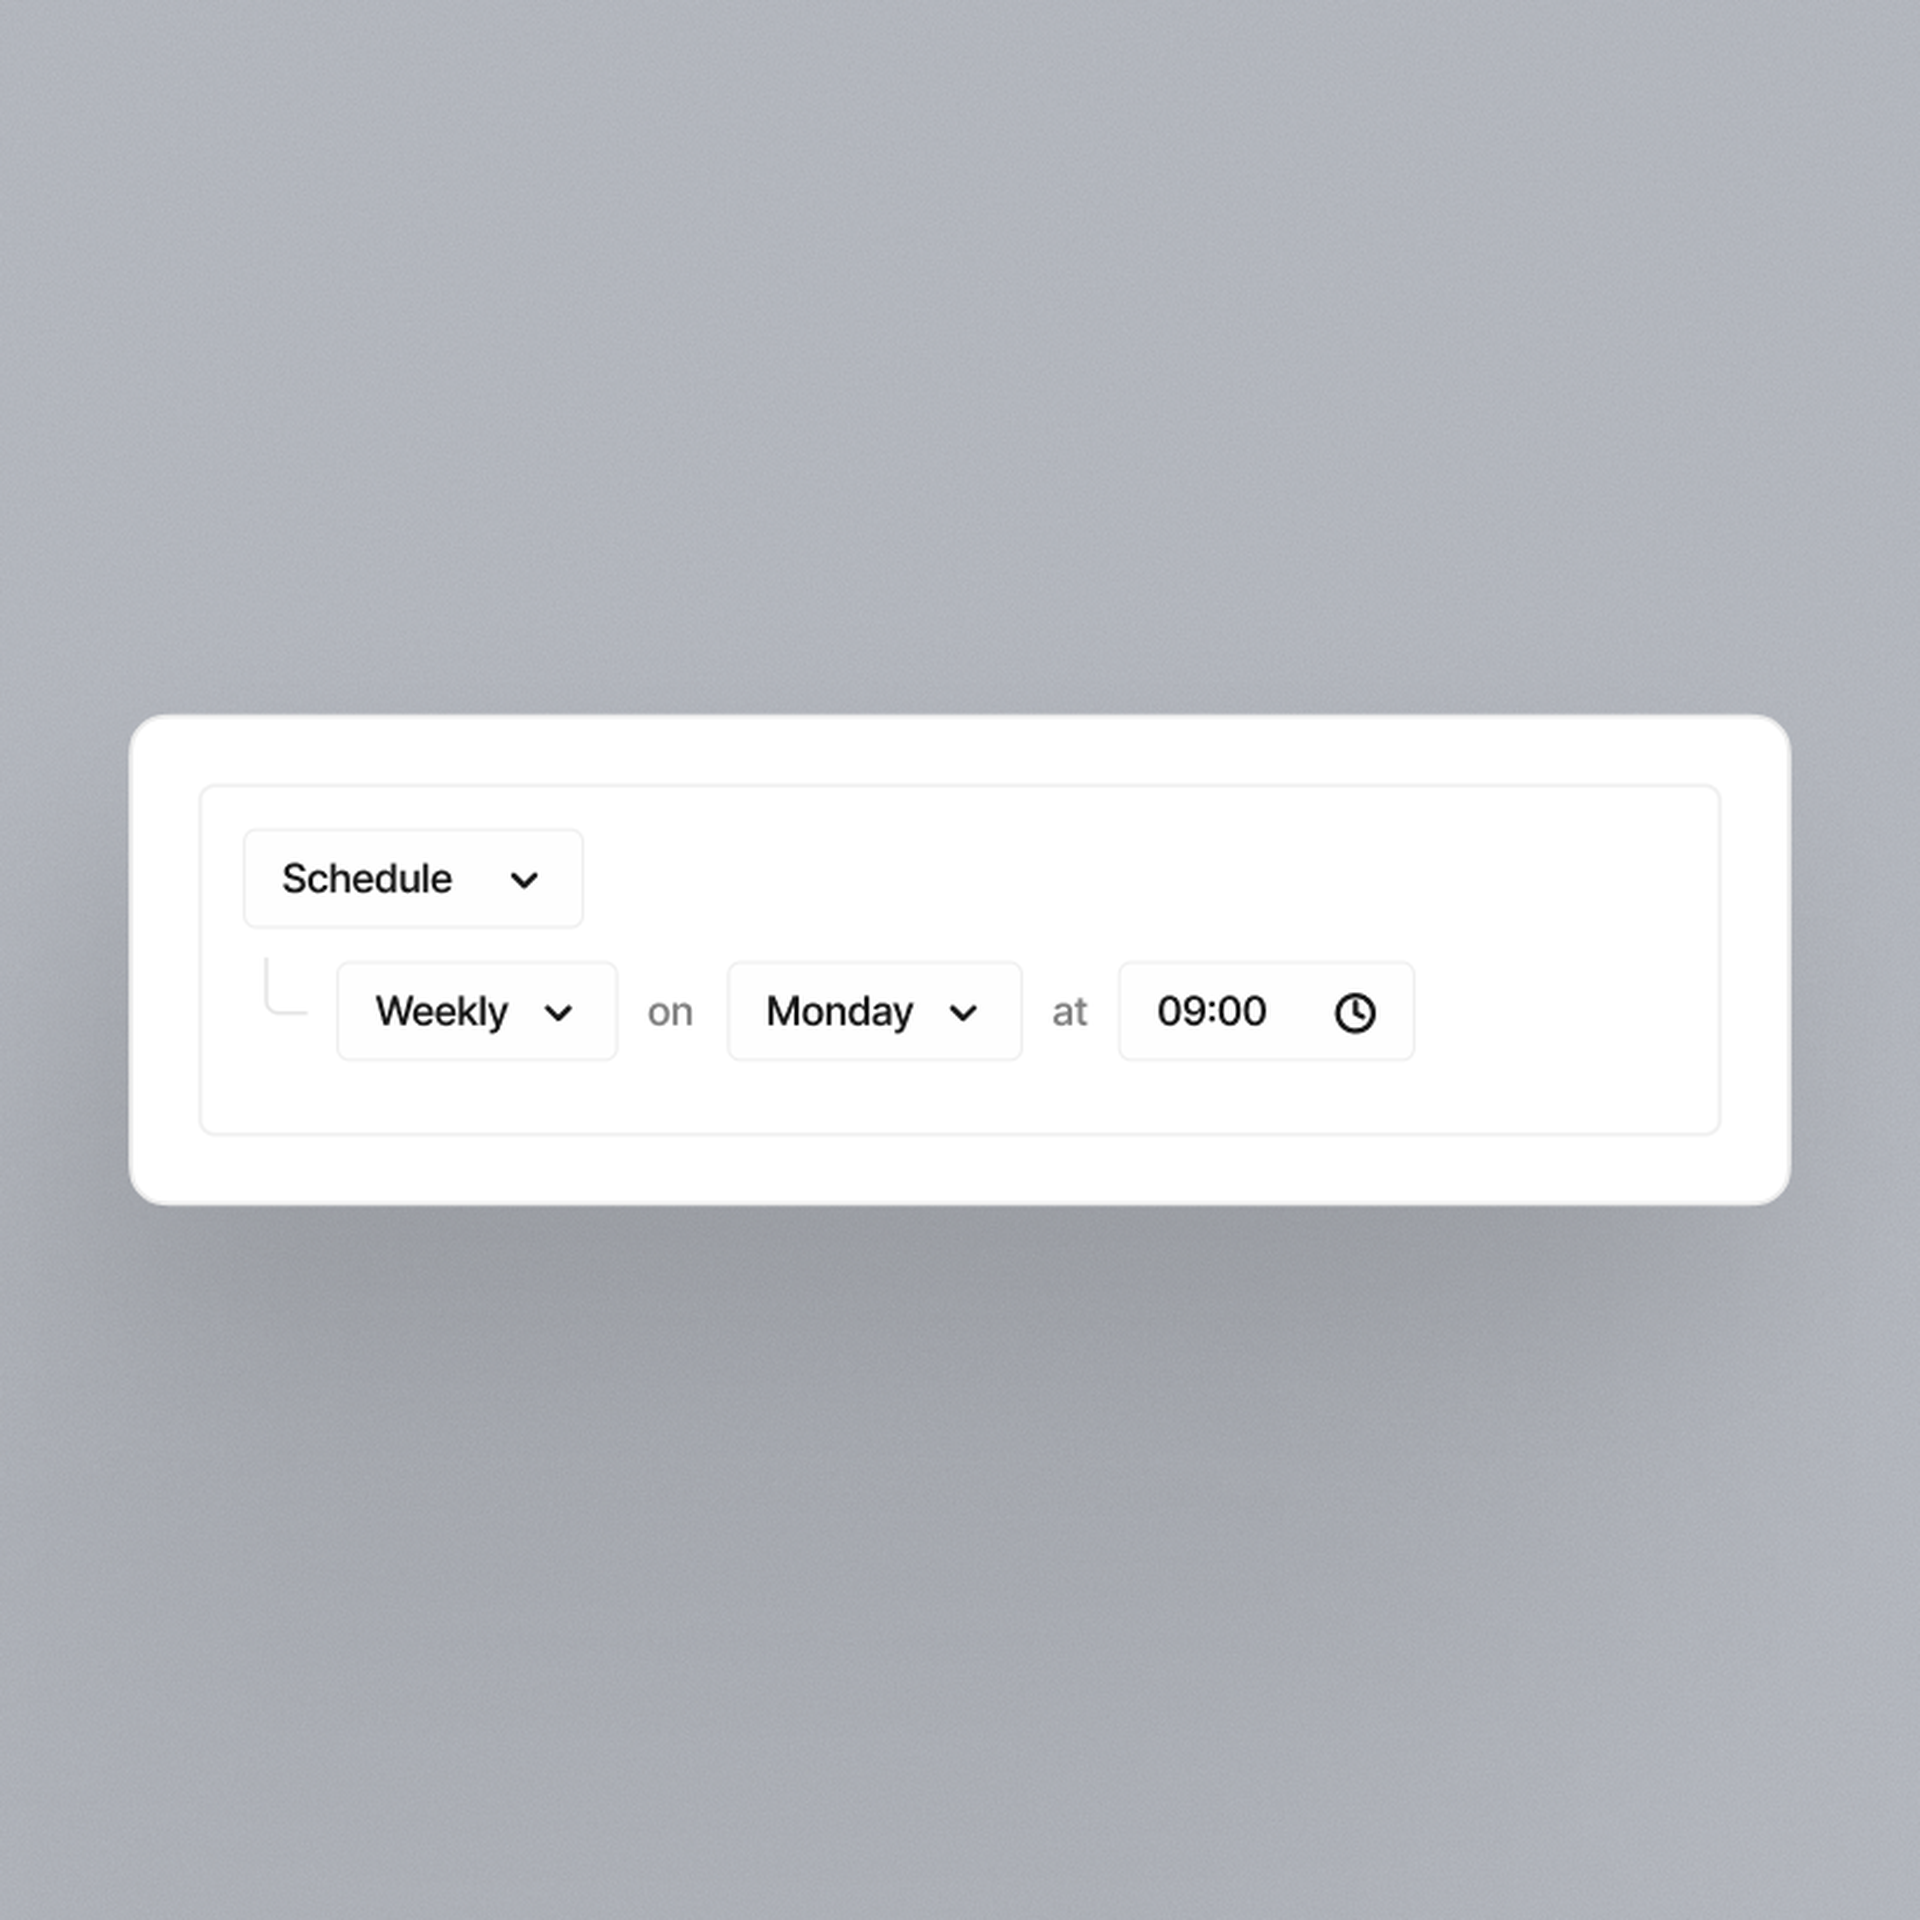
Automations
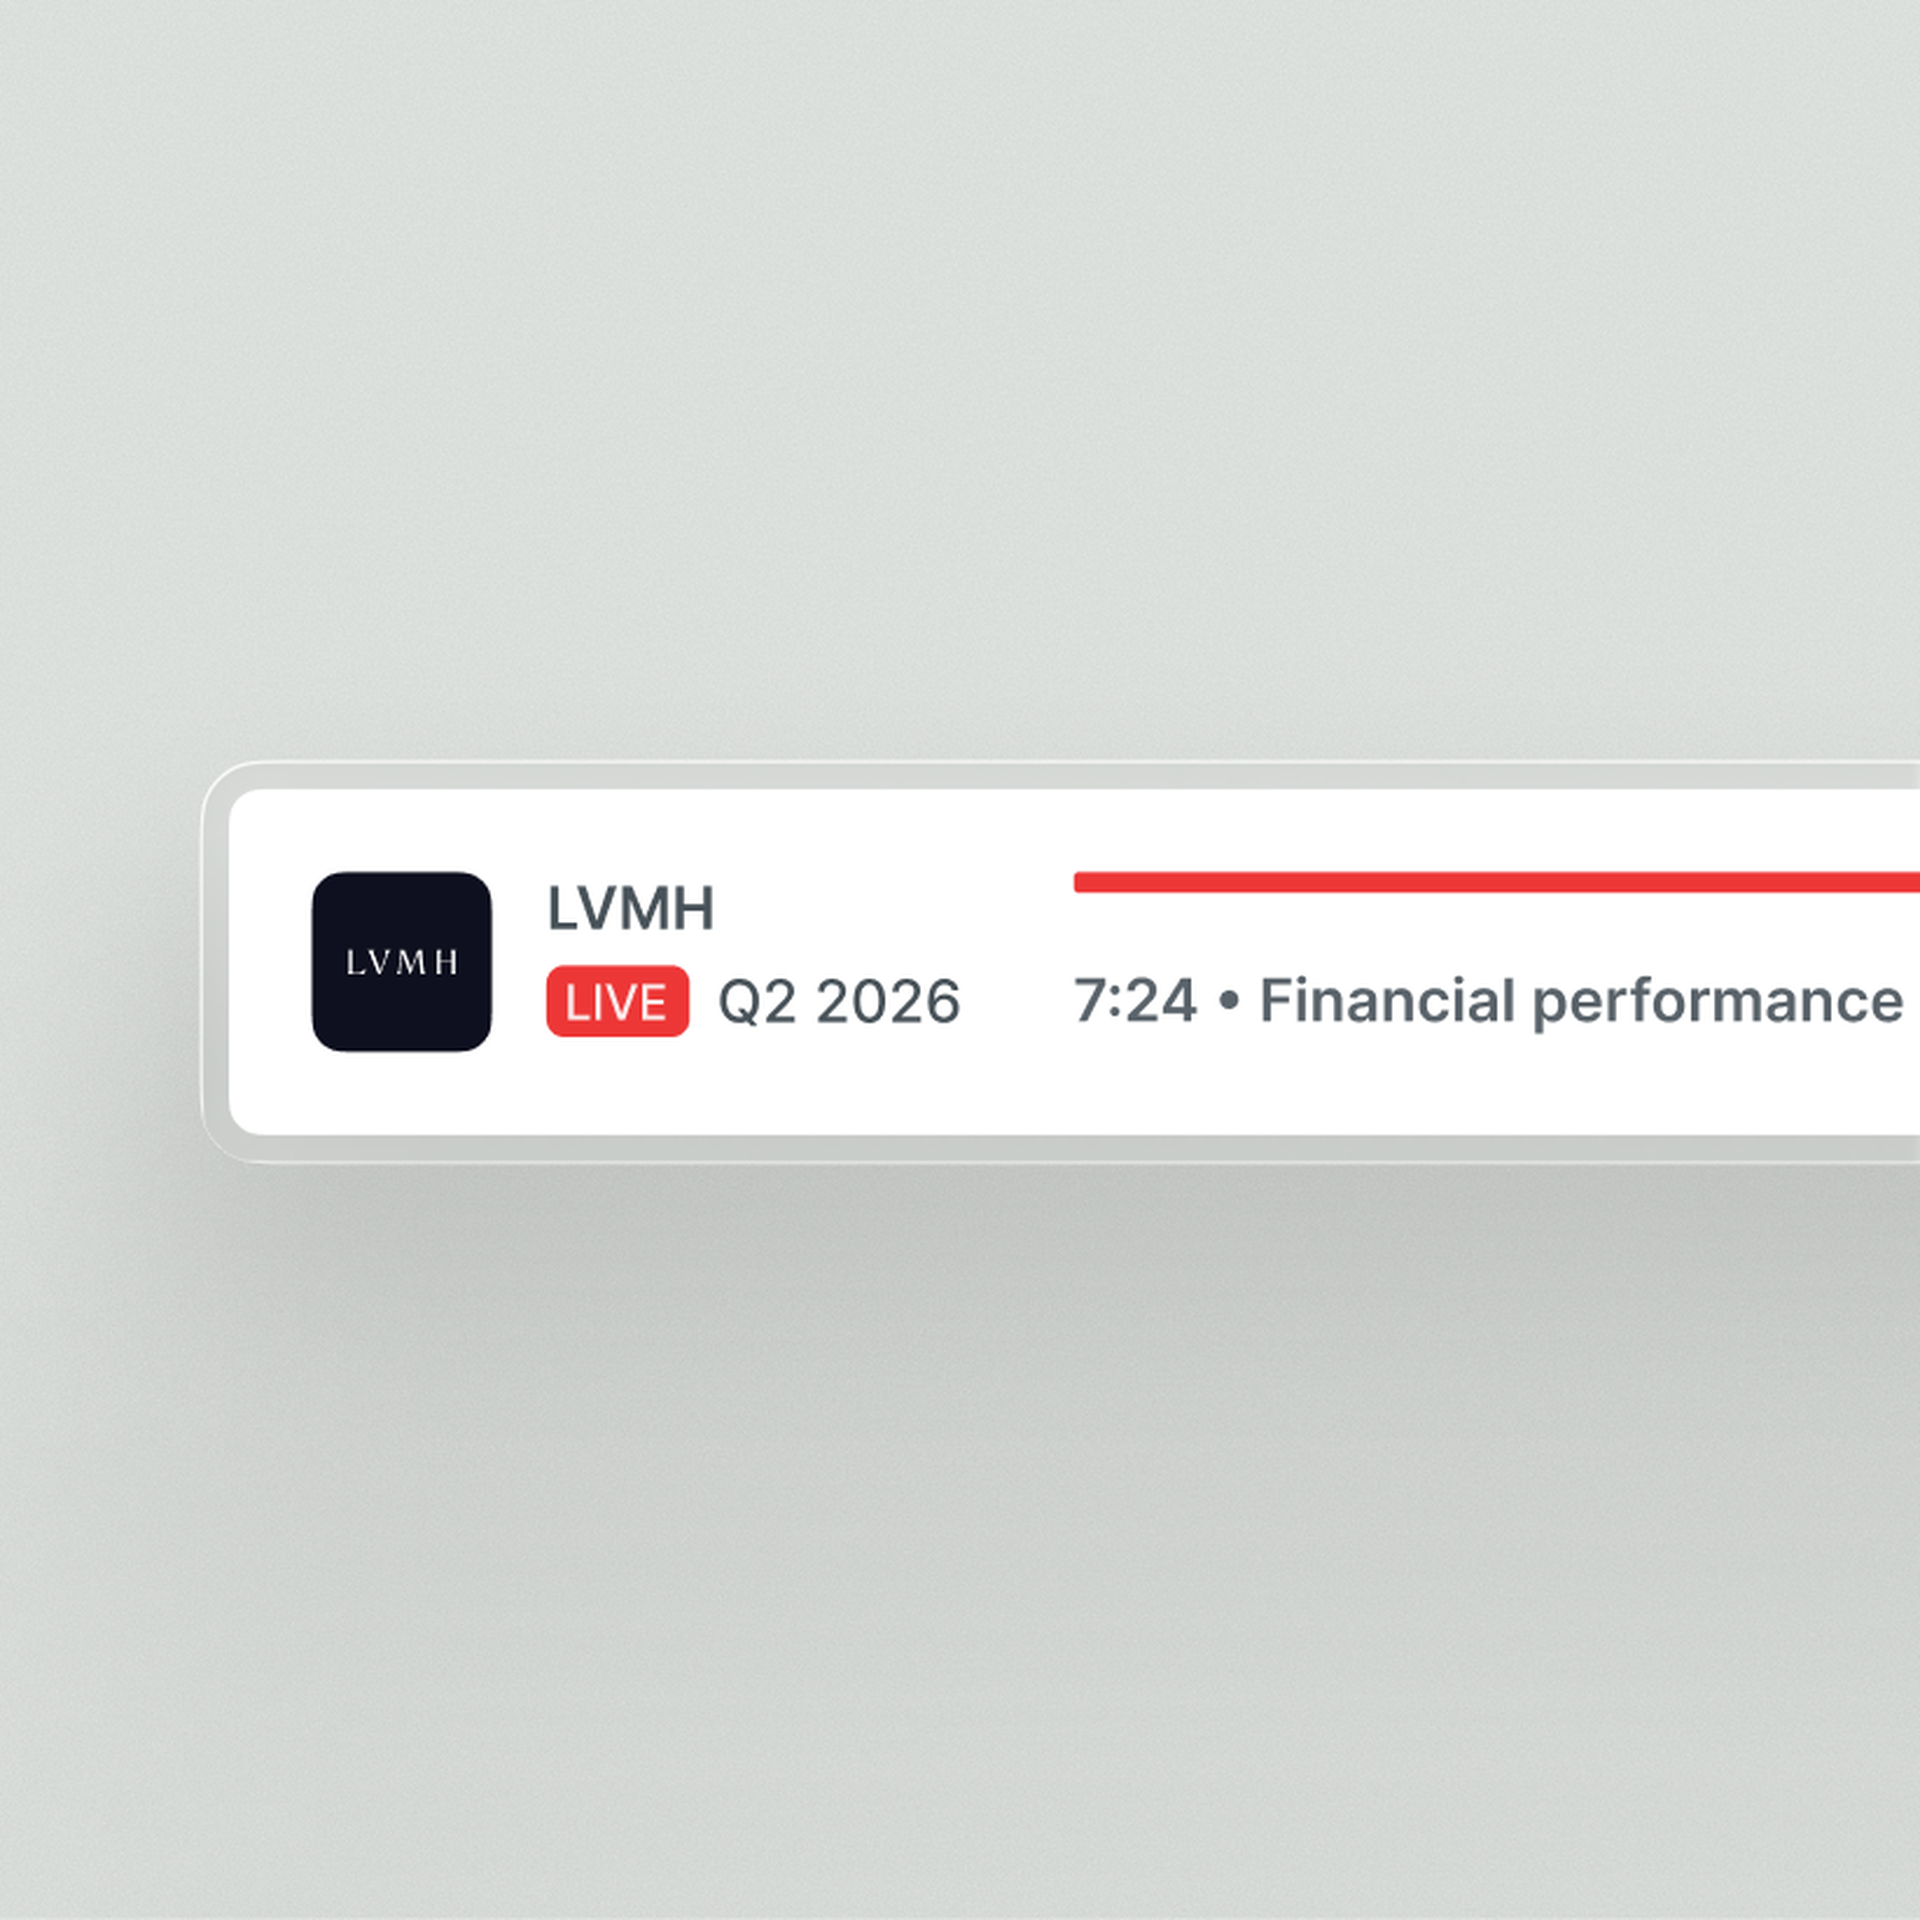
Live audio & transcripts
Quartr's AI stands out because it only pulls clean, first-party data from public companies. In investing, that's everything.
Jamie Ross
Investment Manager, GAM Investments
Research that used to take hours now takes seconds with Quartr Pro. Tracking shifts in tone or extracting tables, it's as simple as typing a query.
Tom O'Hara
Investment Director
Before Quartr we spent hours manually compiling insights through the peer earnings cycle. Now, these tasks are done faster, with greater precision.
Gregg Lampf
VP of Investor Relations
Being able to ask specific questions across years of transcripts and reports and instantly get verified answers is a game-changer.
Pontus Dackmo
CEO & Investment Manager