Edge16 Oct 2026
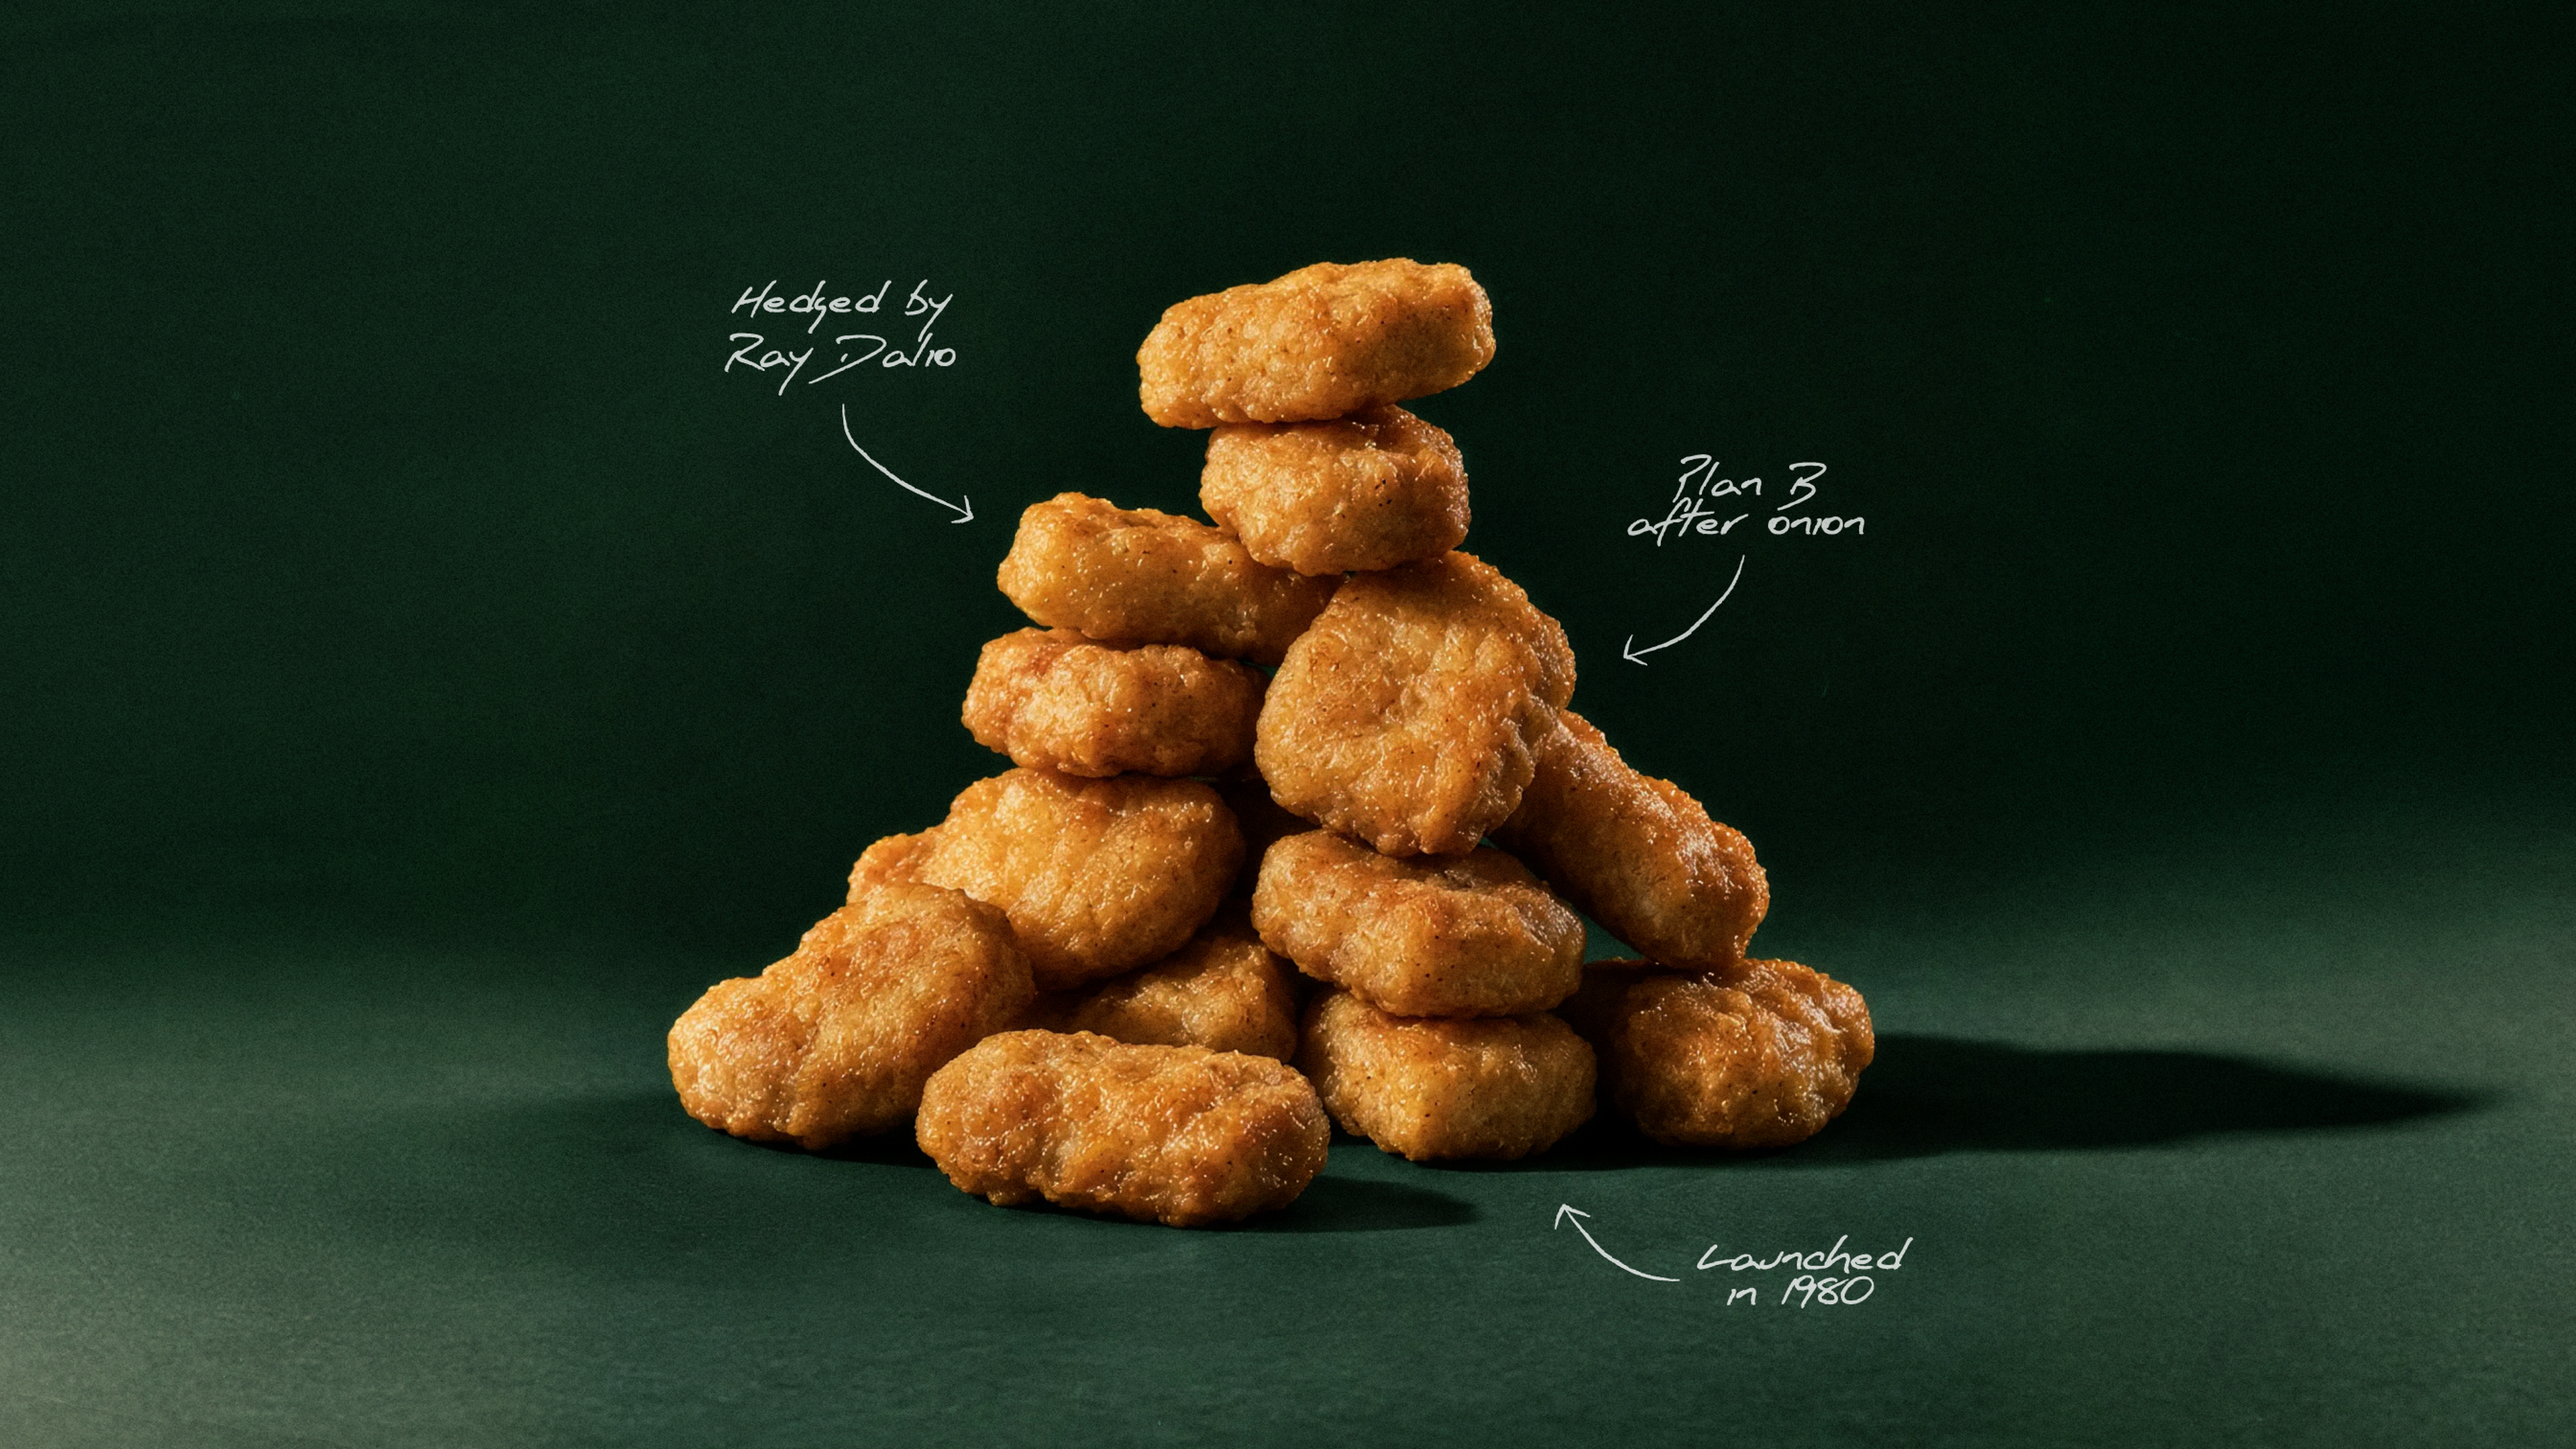
Winner, Winner: The Chicken McNugget Story
How a 1940s breeding contest, a Cornell food scientist, and a hedge by Ray Dalio helped McDonald's turn the Chicken McNugget into a fast-food icon.

2Q26 sales were KRW362bn, down 6.6% YoY; operating profit was KRW38bn and operating margin was 10.5%, up 1.8pp YoY.
Backlog reached a record KRW5.979tn at June 30, 2026, up 44.1% from FY25-end; 1H26 orders totaled KRW2.127tn.
1H26 new orders increased 31.5% YoY to KRW2.127tn, with balanced intake across vessel types.
Revenue declined as engine deliveries fell by 25 units YoY; the lower delivery volume was described as a one-time reduction.
Deliveries of orders secured since 2024 supported higher profitability despite lower marine engine sales.
2026 global newbuild orders are expected to remain in line with 2025; the 2027–2036 average is forecast at 49m CGT.
The four-stroke factory was under construction in 2Q26, with first shop tests and first engine delivery scheduled from 3Q26 onward; planned capacity is up to 180 units annually.

The #1 app for qualitative research. Live earnings calls, AI chat, transcripts, and more. All for free.
Listen to earnings calls, CMDs, investor conferences, and more – with a podcast-like experience.
Search for any keyword across all transcripts simultaneously.
Capturing important takeaways is as simple as it gets. Even during your lunch run or commute.
Follow the companies that matter to you. Get a personalized feed with real-time updates.
Set keyword alerts for any company, product, or competitor. Get notified the moment they're mentioned.
Access analyst consensus estimates, valuation multiples, and revenue segments splits.
The easiest way to stay updated during earnings season.
All events from public companies. Live and recorded.
No webcast links. No manual registrations.
excellent app, it gives me free access to company earnings calls and annual reports. I also love the convenience of calls being available offline so I can listen in whilst doing other things and even when internet or WiFi isn't available.
One of the very few apps you could call perfect. If something was to add to it, maybe the share price of the company when you search for it, but it's already excellent.
This is genuinely one of the cleanest and fastest finance apps out there to track the market.
excellent app, it gives me free access to company earnings calls and annual reports. I also love the convenience of calls being available offline so I can listen in whilst doing other things and even when internet or WiFi isn't available.
One of the very few apps you could call perfect. If something was to add to it, maybe the share price of the company when you search for it, but it's already excellent.
This is genuinely one of the cleanest and fastest finance apps out there to track the market.
I can't remember the last time an app had such a positive impact on my investment process.
Love the app! Quartr makes it really easy to keep track of earnings calls. It also includes the reports and slides to make it easier to follow along.
Quartr is amazing, no way around it. It is the best right now for earnings calls, presentations, and the like.
I can't remember the last time an app had such a positive impact on my investment process.
Love the app! Quartr makes it really easy to keep track of earnings calls. It also includes the reports and slides to make it easier to follow along.
Quartr is amazing, no way around it. It is the best right now for earnings calls, presentations, and the like.
Explore our global coverage