Edge16 Oct 2026
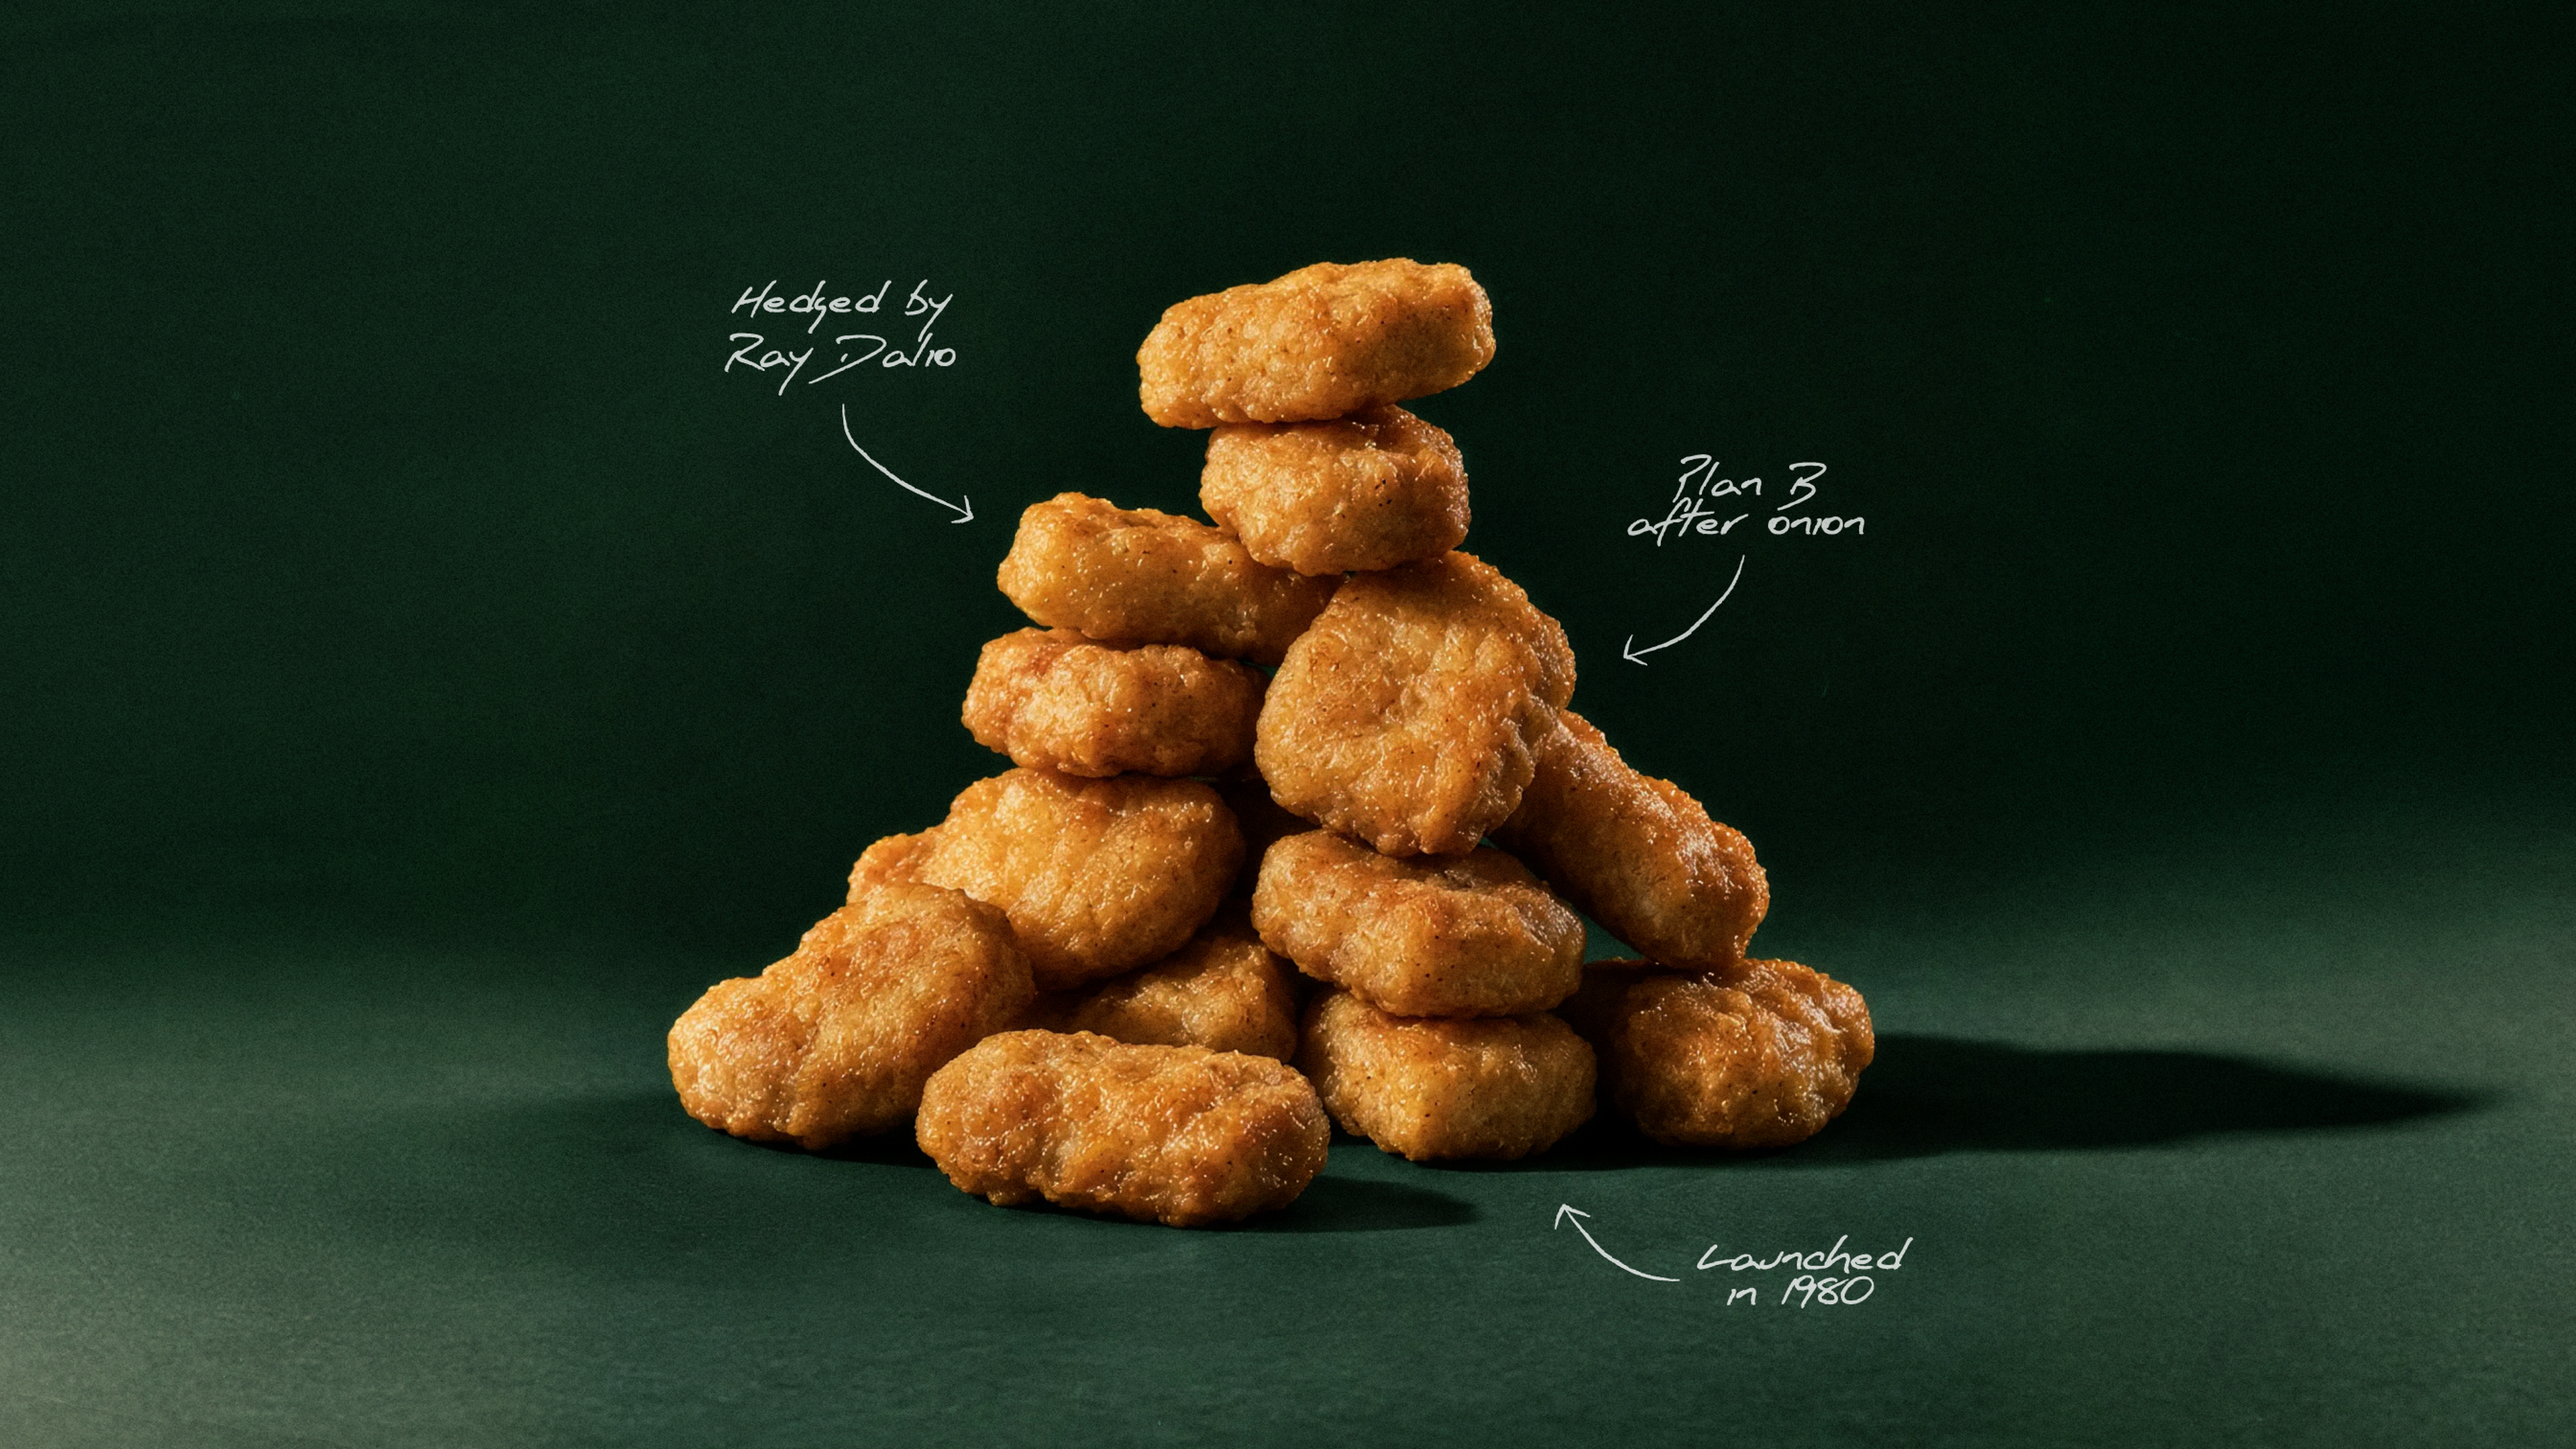
Winner, Winner: The Chicken McNugget Story
How a 1940s breeding contest, a Cornell food scientist, and a hedge by Ray Dalio helped McDonald's turn the Chicken McNugget into a fast-food icon.

2026 UK completions excluding joint ventures are expected at ~10,500; adjusted operating profit is expected near the bottom of the £262m-£299m consensus range, which includes joint ventures and excludes exceptional items.
Net private sales rate from 29 June to 8 November was 0.60 per outlet per week versus 0.63 in 2025; excluding bulk deals, 0.54 versus 0.61. Cancellation rate was 17% in both periods.
Order book was 6,839 homes valued at ~£1,984m as of 8 November, versus 7,253 homes and ~£2,116m in 2025; underlying pricing was ~2.5% below last year and incentives remained at 6%-6.5%.
Pricing pressure was most acute in London, less severe across the wider Southeast and gradually improving farther north; higher mortgage rates and living costs weighed on affordability and near-term demand.
Customer interest and site engagement remained robust, but borrowing costs and affordability concerns lengthened the inquiry-to-reservation period and increased buyer hesitation.
Build cost inflation is expected at 3%-4% for 2026; labor cost pressure has been contained through the year.
Cost actions include procurement and commercial controls, standardization, product substitutions, site-design improvements and tighter specifications, with savings tracked through orders and costs to the bottom line.
Supplier negotiations, competitive tendering, e-auctions and cost validation aim to offset supply-chain inflation; mitigation depends on energy, fuel and commodity markets.
Tight work-in-progress control is aligned with sales; outlet growth is planned without net land investment, alongside a smaller short-term landbank.
Cladding spend is expected to be ~£70m in 2026; the provision reflects the current best estimate, with cost certainty improving as building assessments progress.
Outlets increased to 225 from 206 a year earlier; 2027 openings are viewed positively but expected to be weighted toward H2 due to planning delays. More outlets are expected to open in 2026 than in 2025.
Strategic pipeline conversions reached ~5,000 plots year to date versus ~2,000 at the comparable point last year; ~5,000 plots were approved year to date, focusing on smaller sites.
Short-term landbank was ~73,000 plots at end-October versus ~75,000 at 28 June; landbank changes focus on capital efficiency.
Lower sales rates have delayed the landbank margin benefit: limited impact in 2026, a more muted contribution in 2027, and the majority expected in 2028-29.
Expected 2026 shareholder returns total ~£240m; year-end net cash is expected at ~£250m, subject to land purchase timing. By 6 November, ~39m shares had been bought for ~£31.5m of the £41.9m buyback programme.

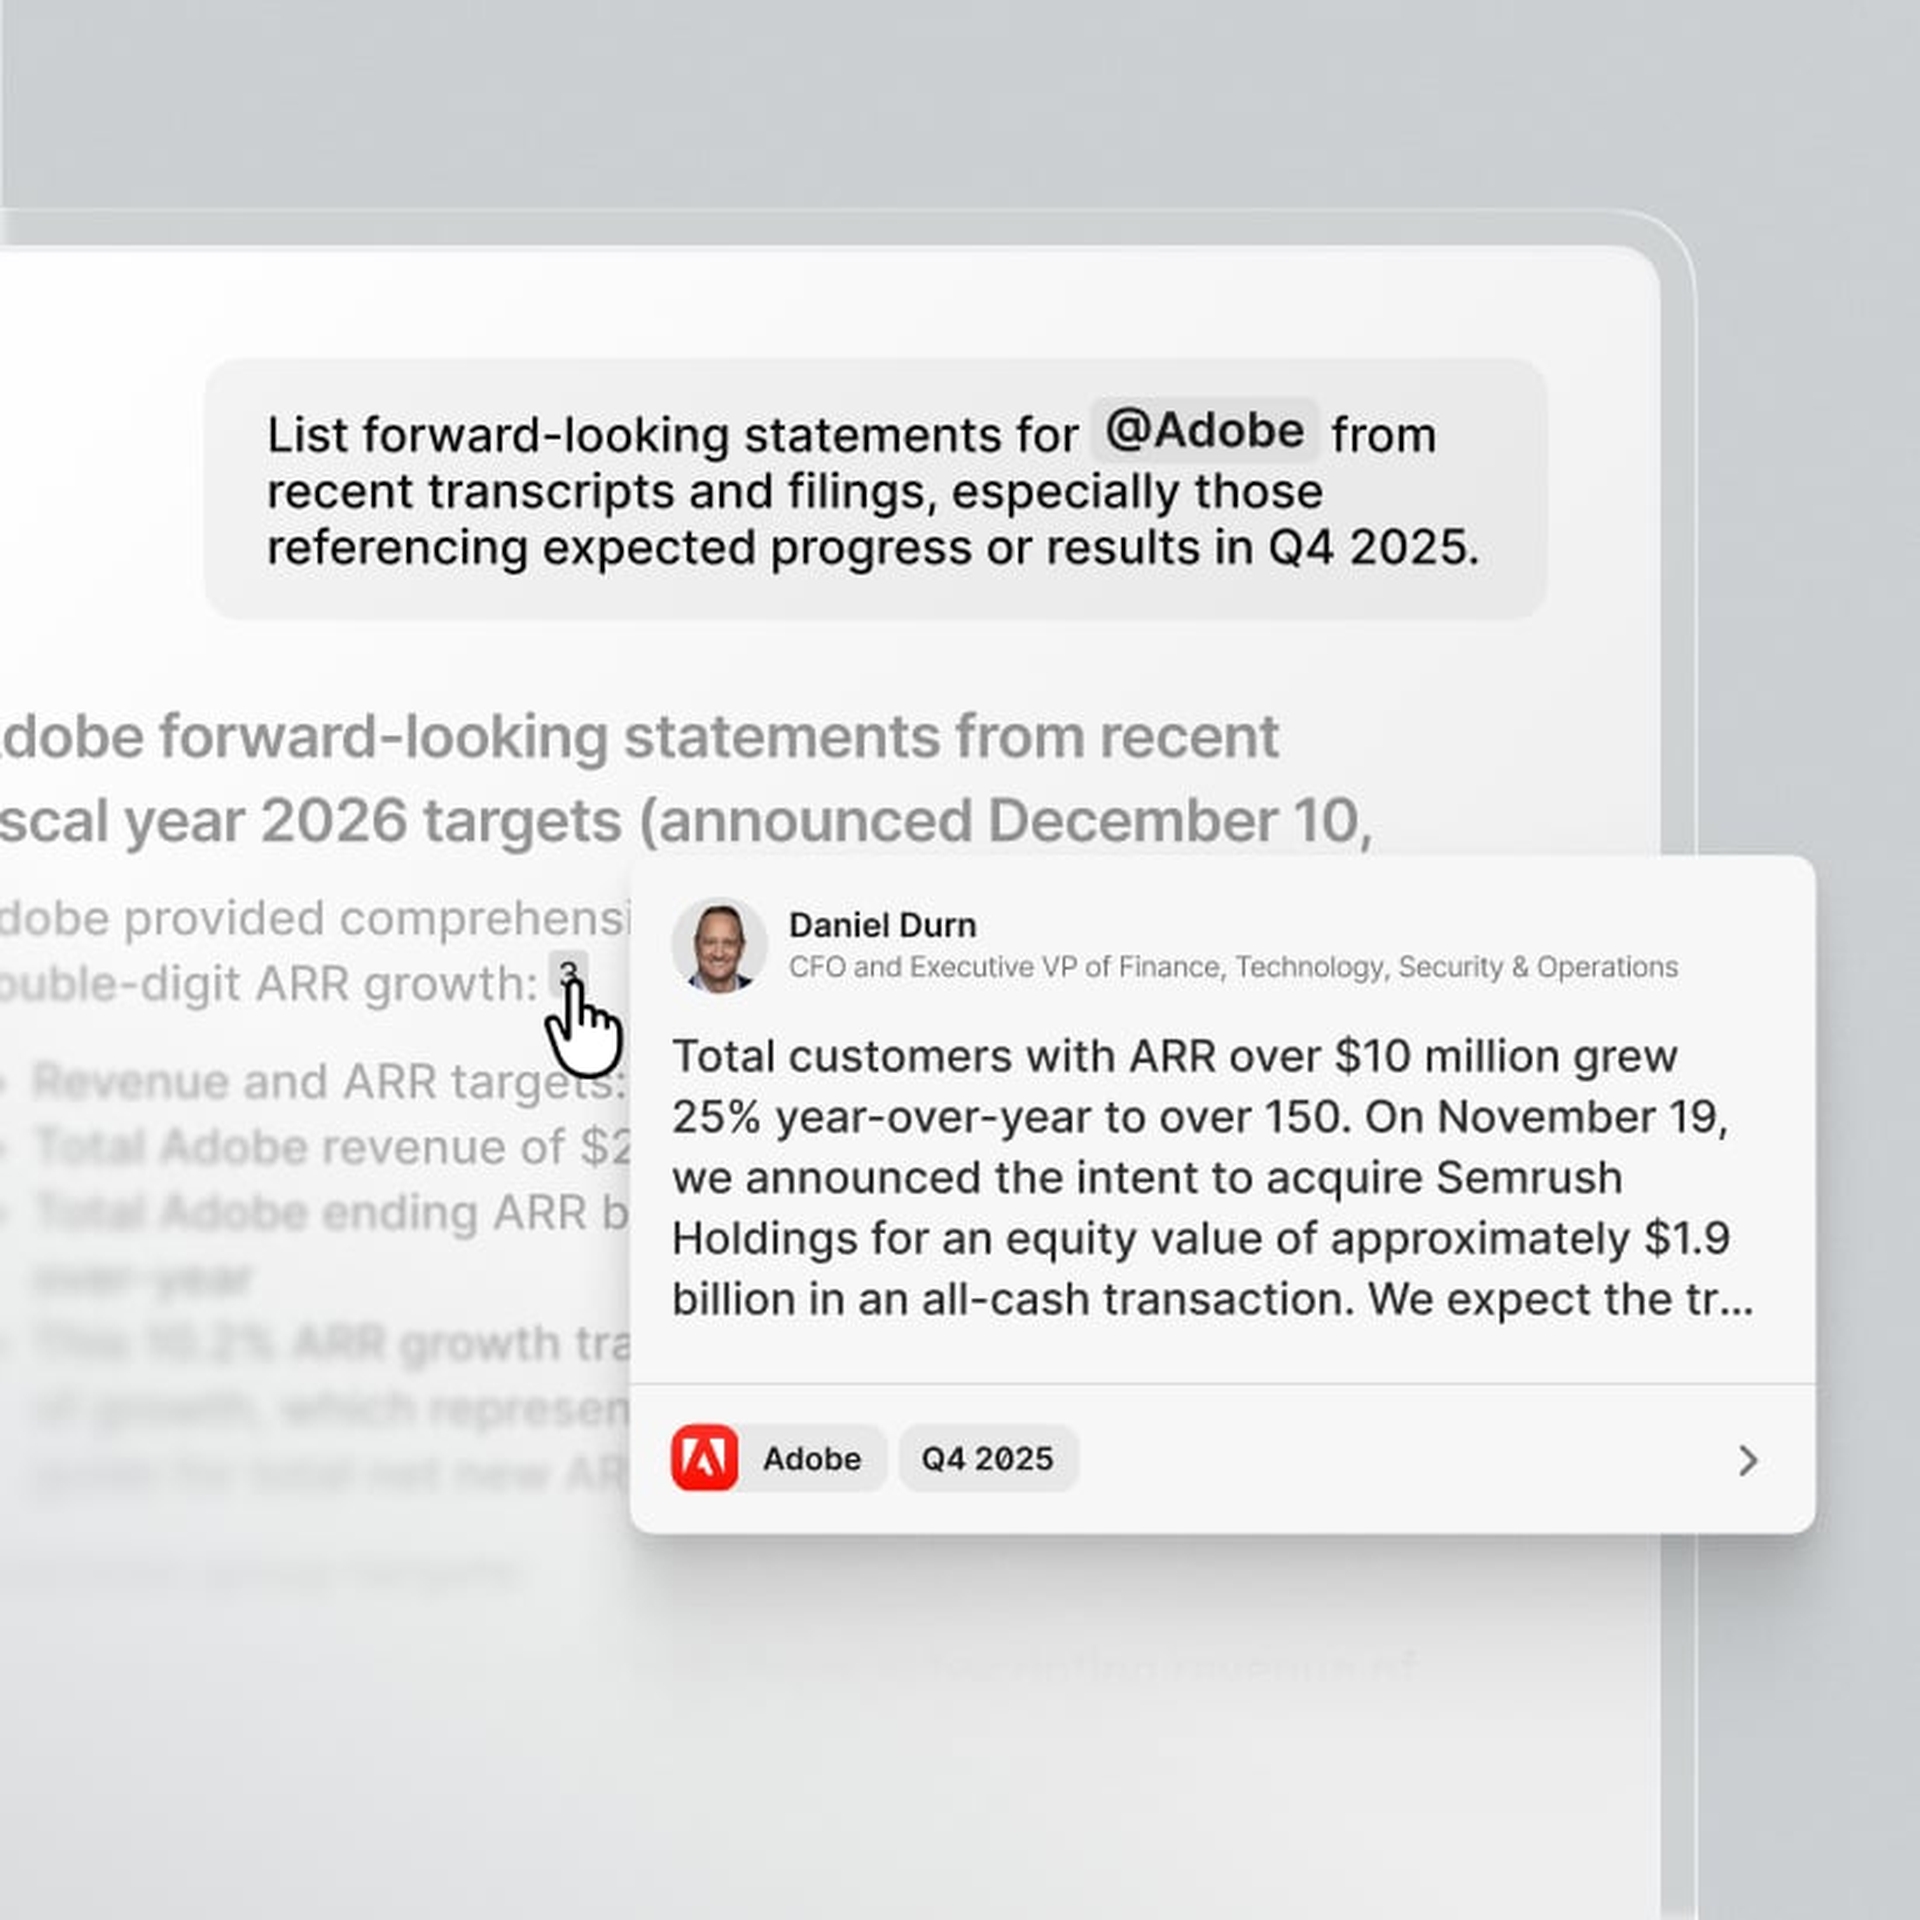
AI chat
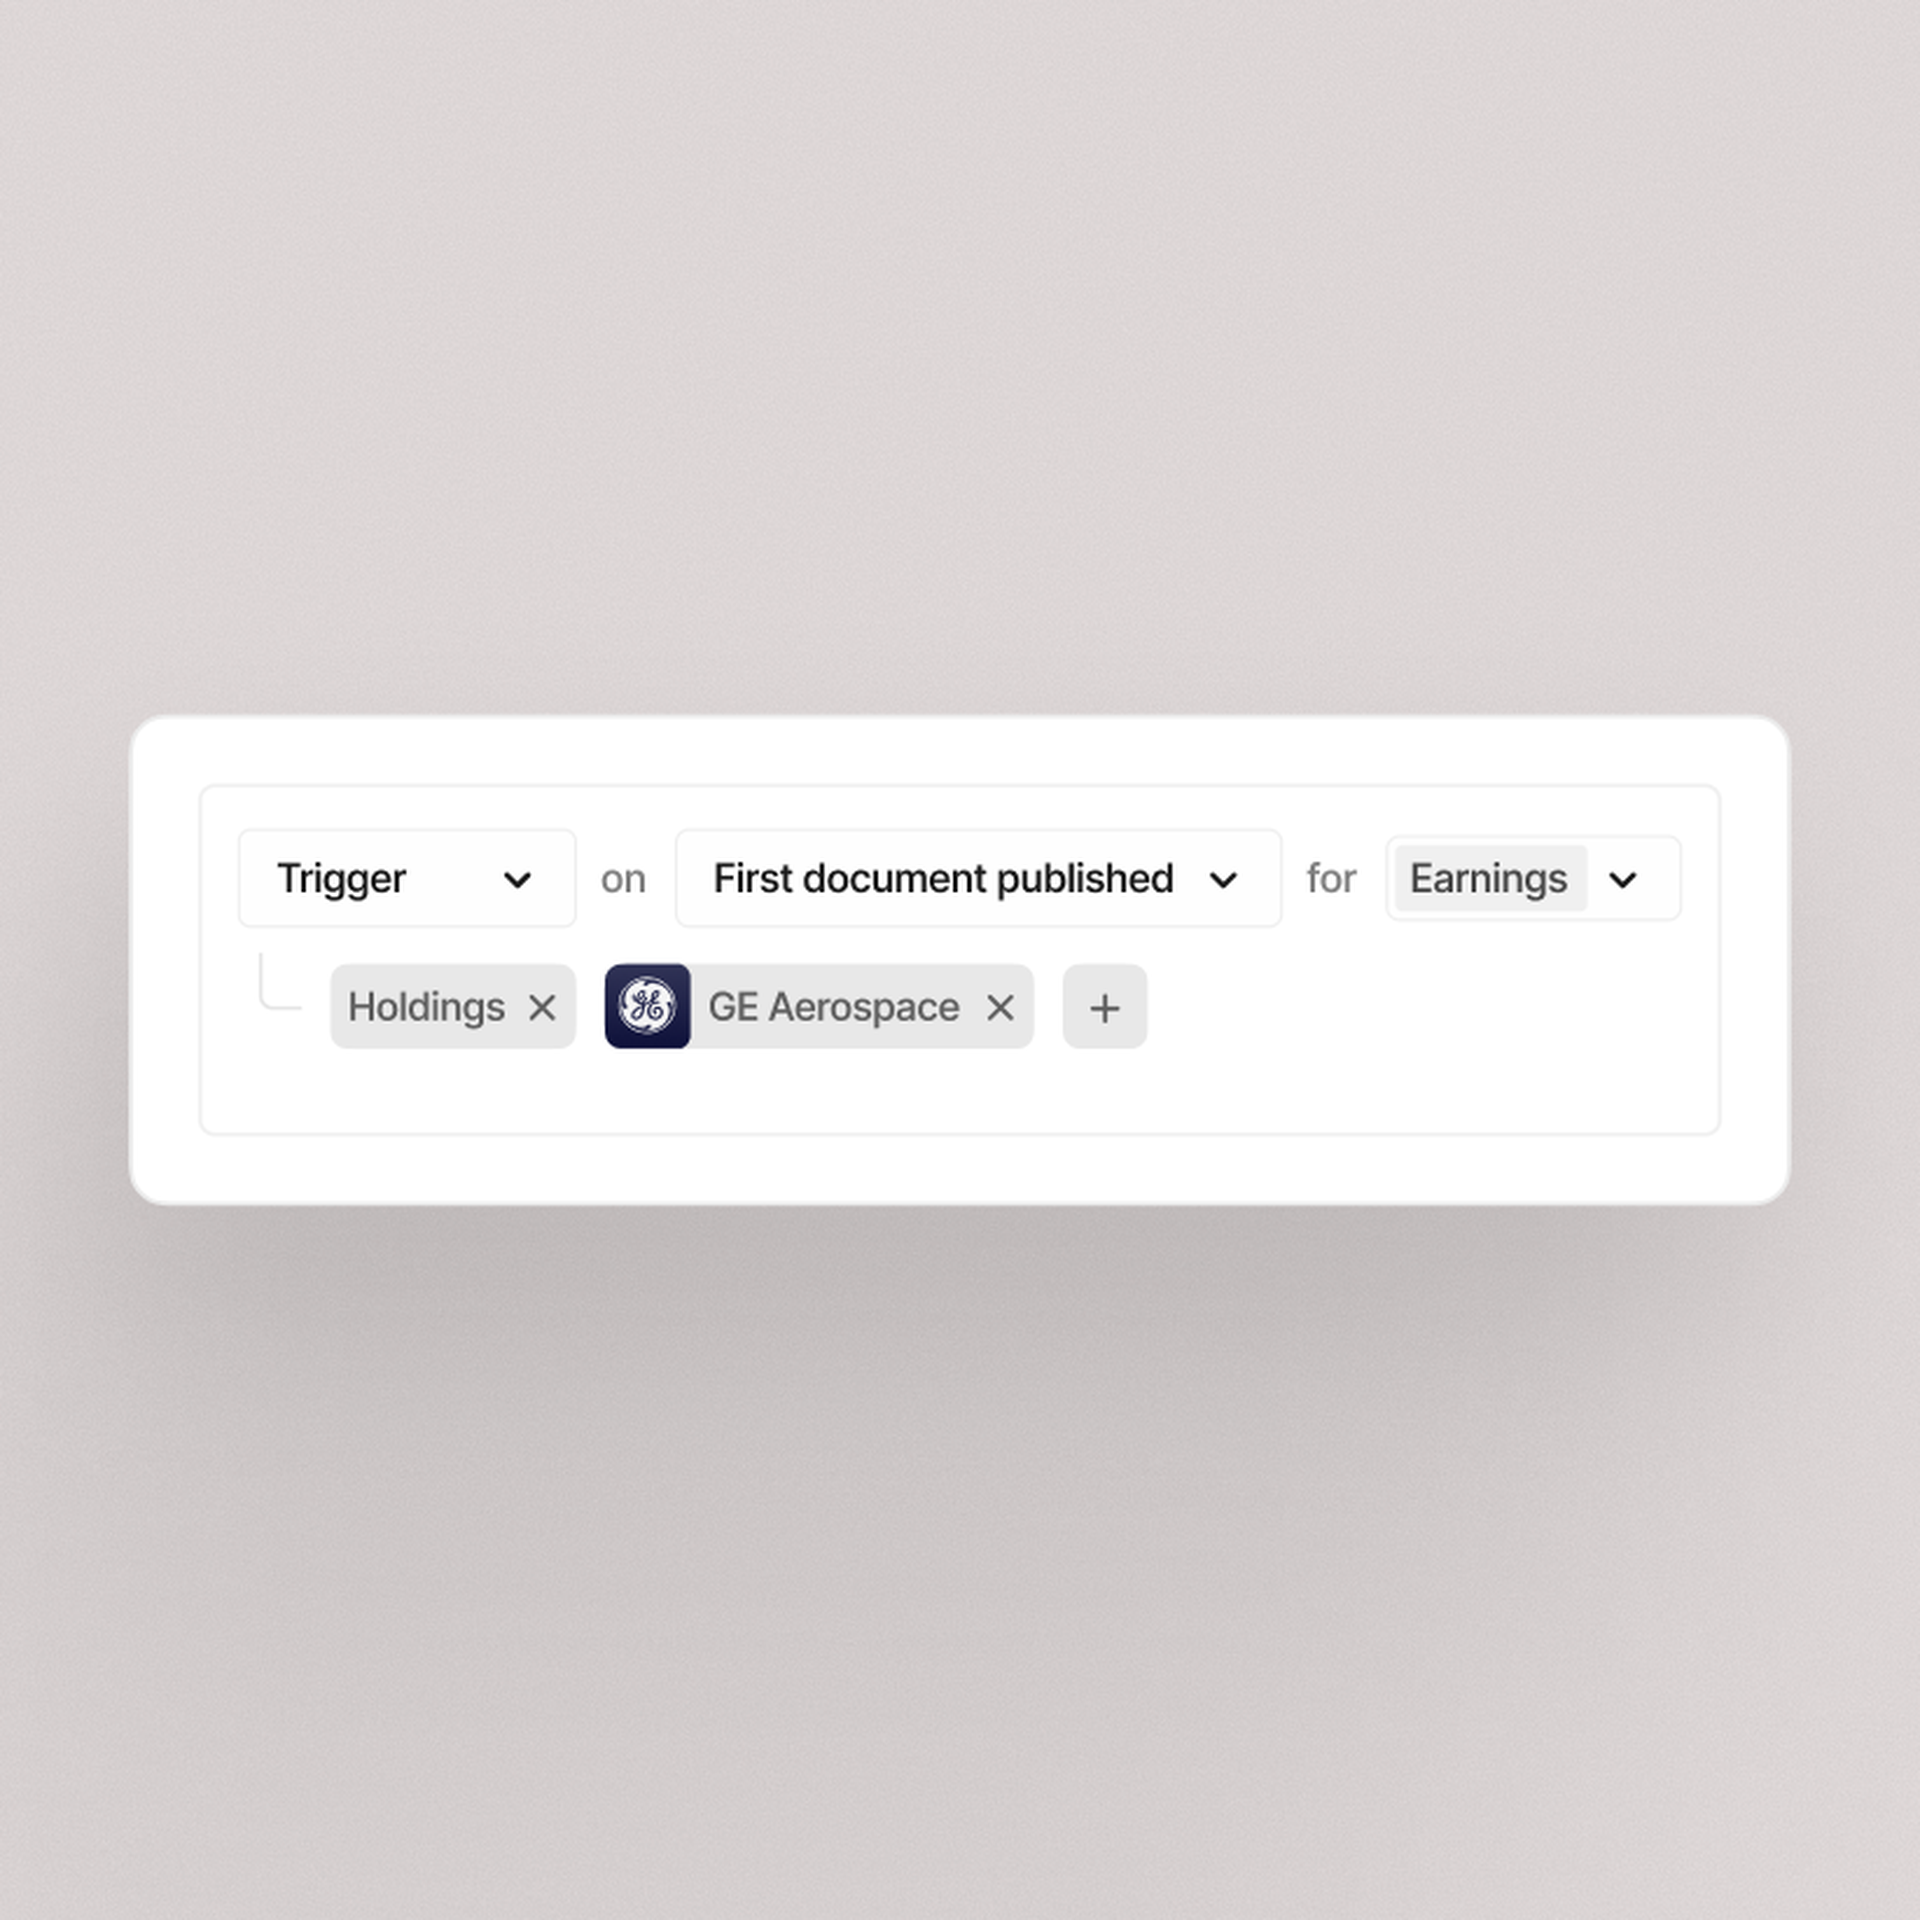
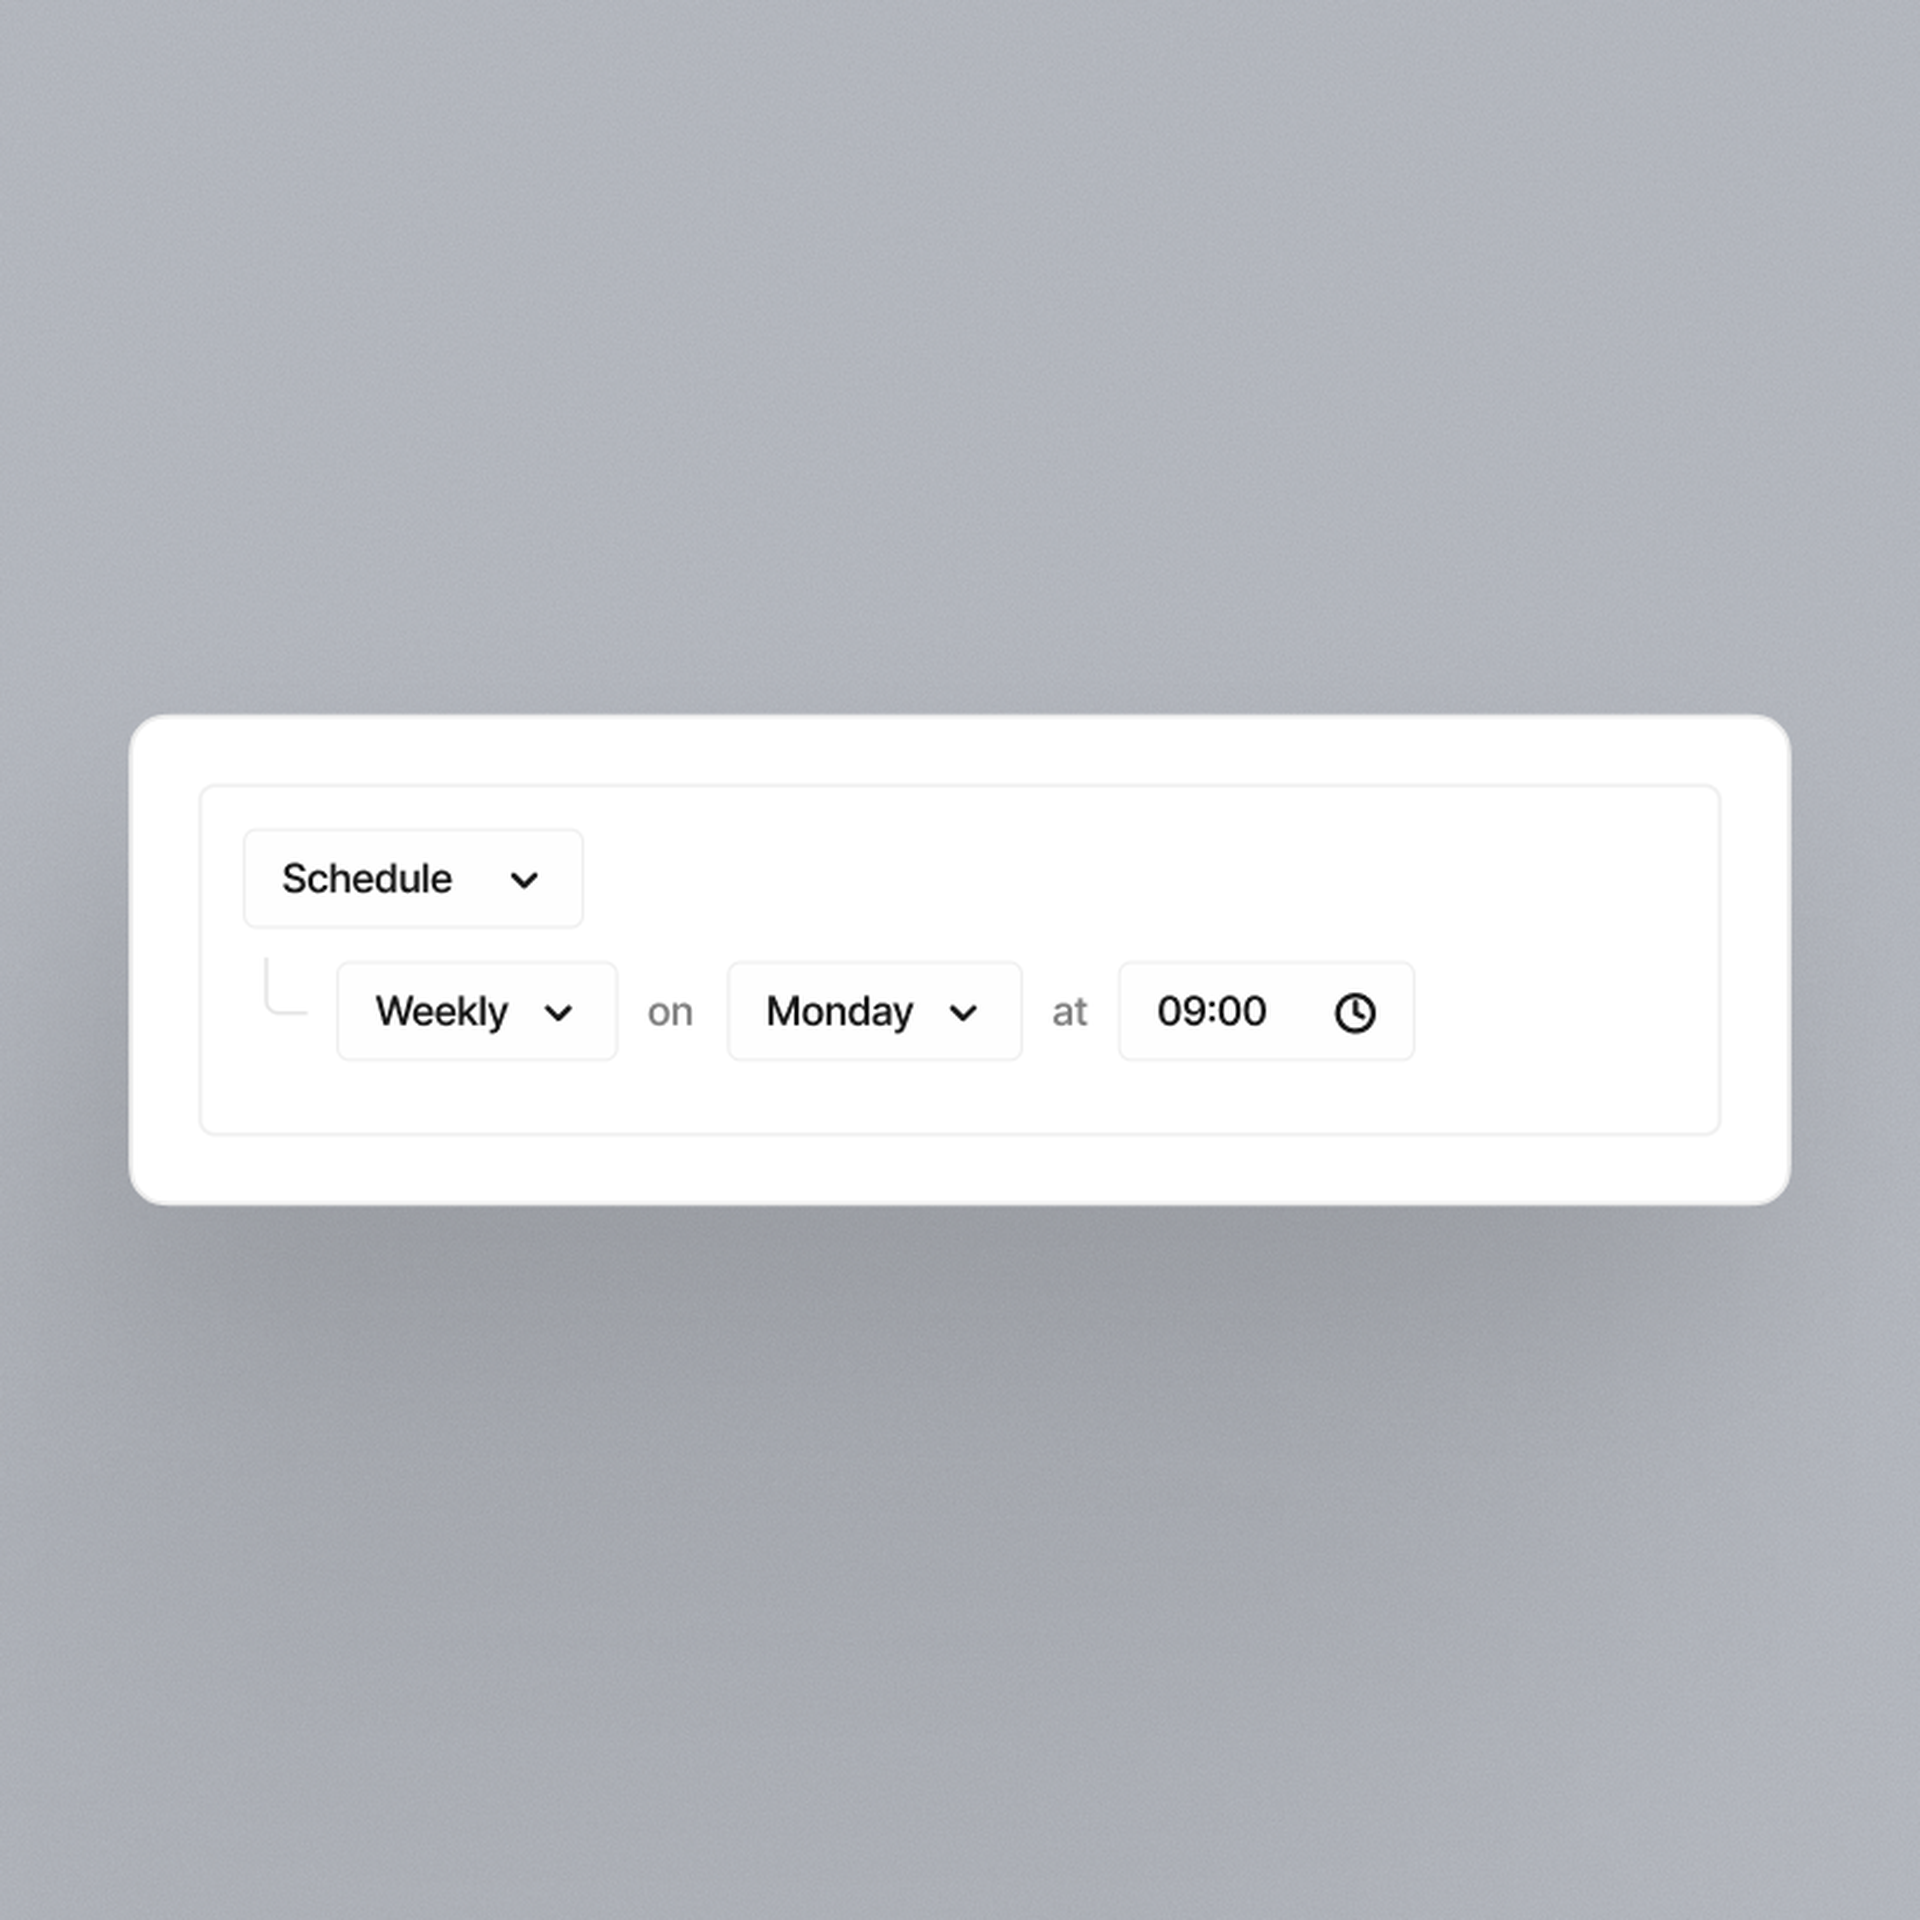
Automations
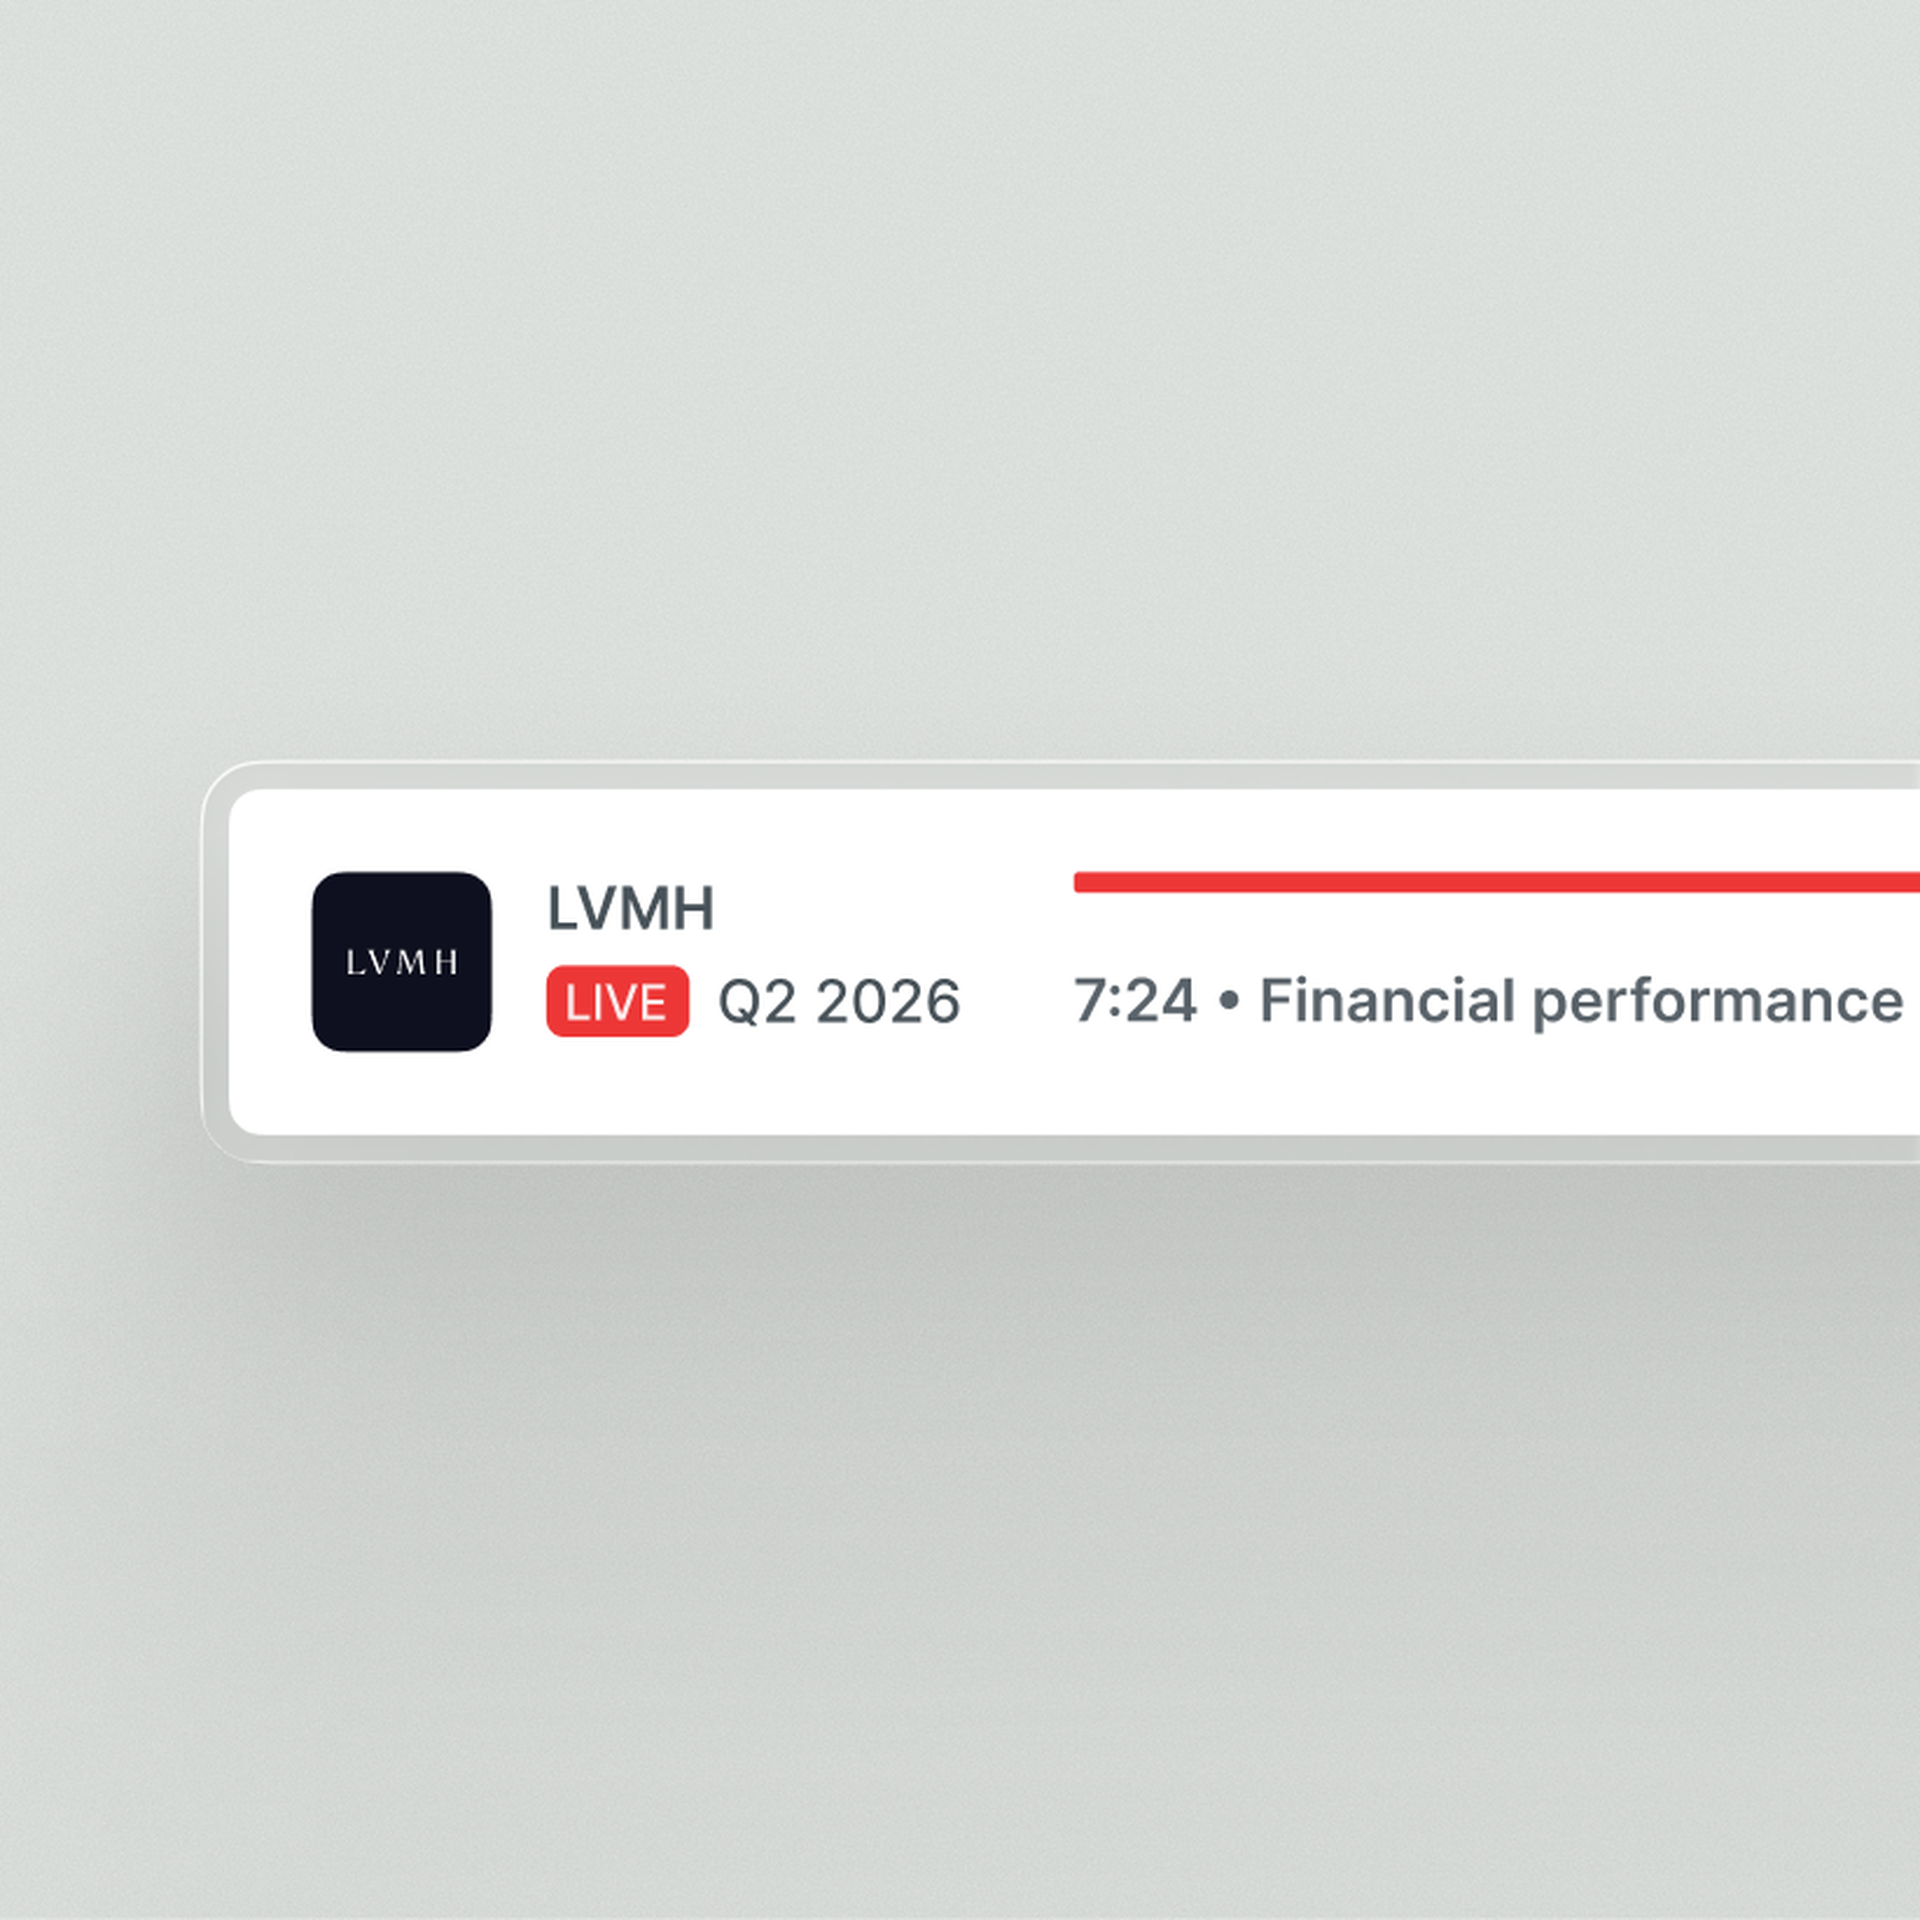
Live audio & transcripts
Quartr's AI stands out because it only pulls clean, first-party data from public companies. In investing, that's everything.
Jamie Ross
Investment Manager, GAM Investments
Research that used to take hours now takes seconds with Quartr Pro. Tracking shifts in tone or extracting tables, it's as simple as typing a query.
Tom O'Hara
Investment Director
Before Quartr we spent hours manually compiling insights through the peer earnings cycle. Now, these tasks are done faster, with greater precision.
Gregg Lampf
VP of Investor Relations
Being able to ask specific questions across years of transcripts and reports and instantly get verified answers is a game-changer.
Pontus Dackmo
CEO & Investment Manager