Edge16 Oct 2026
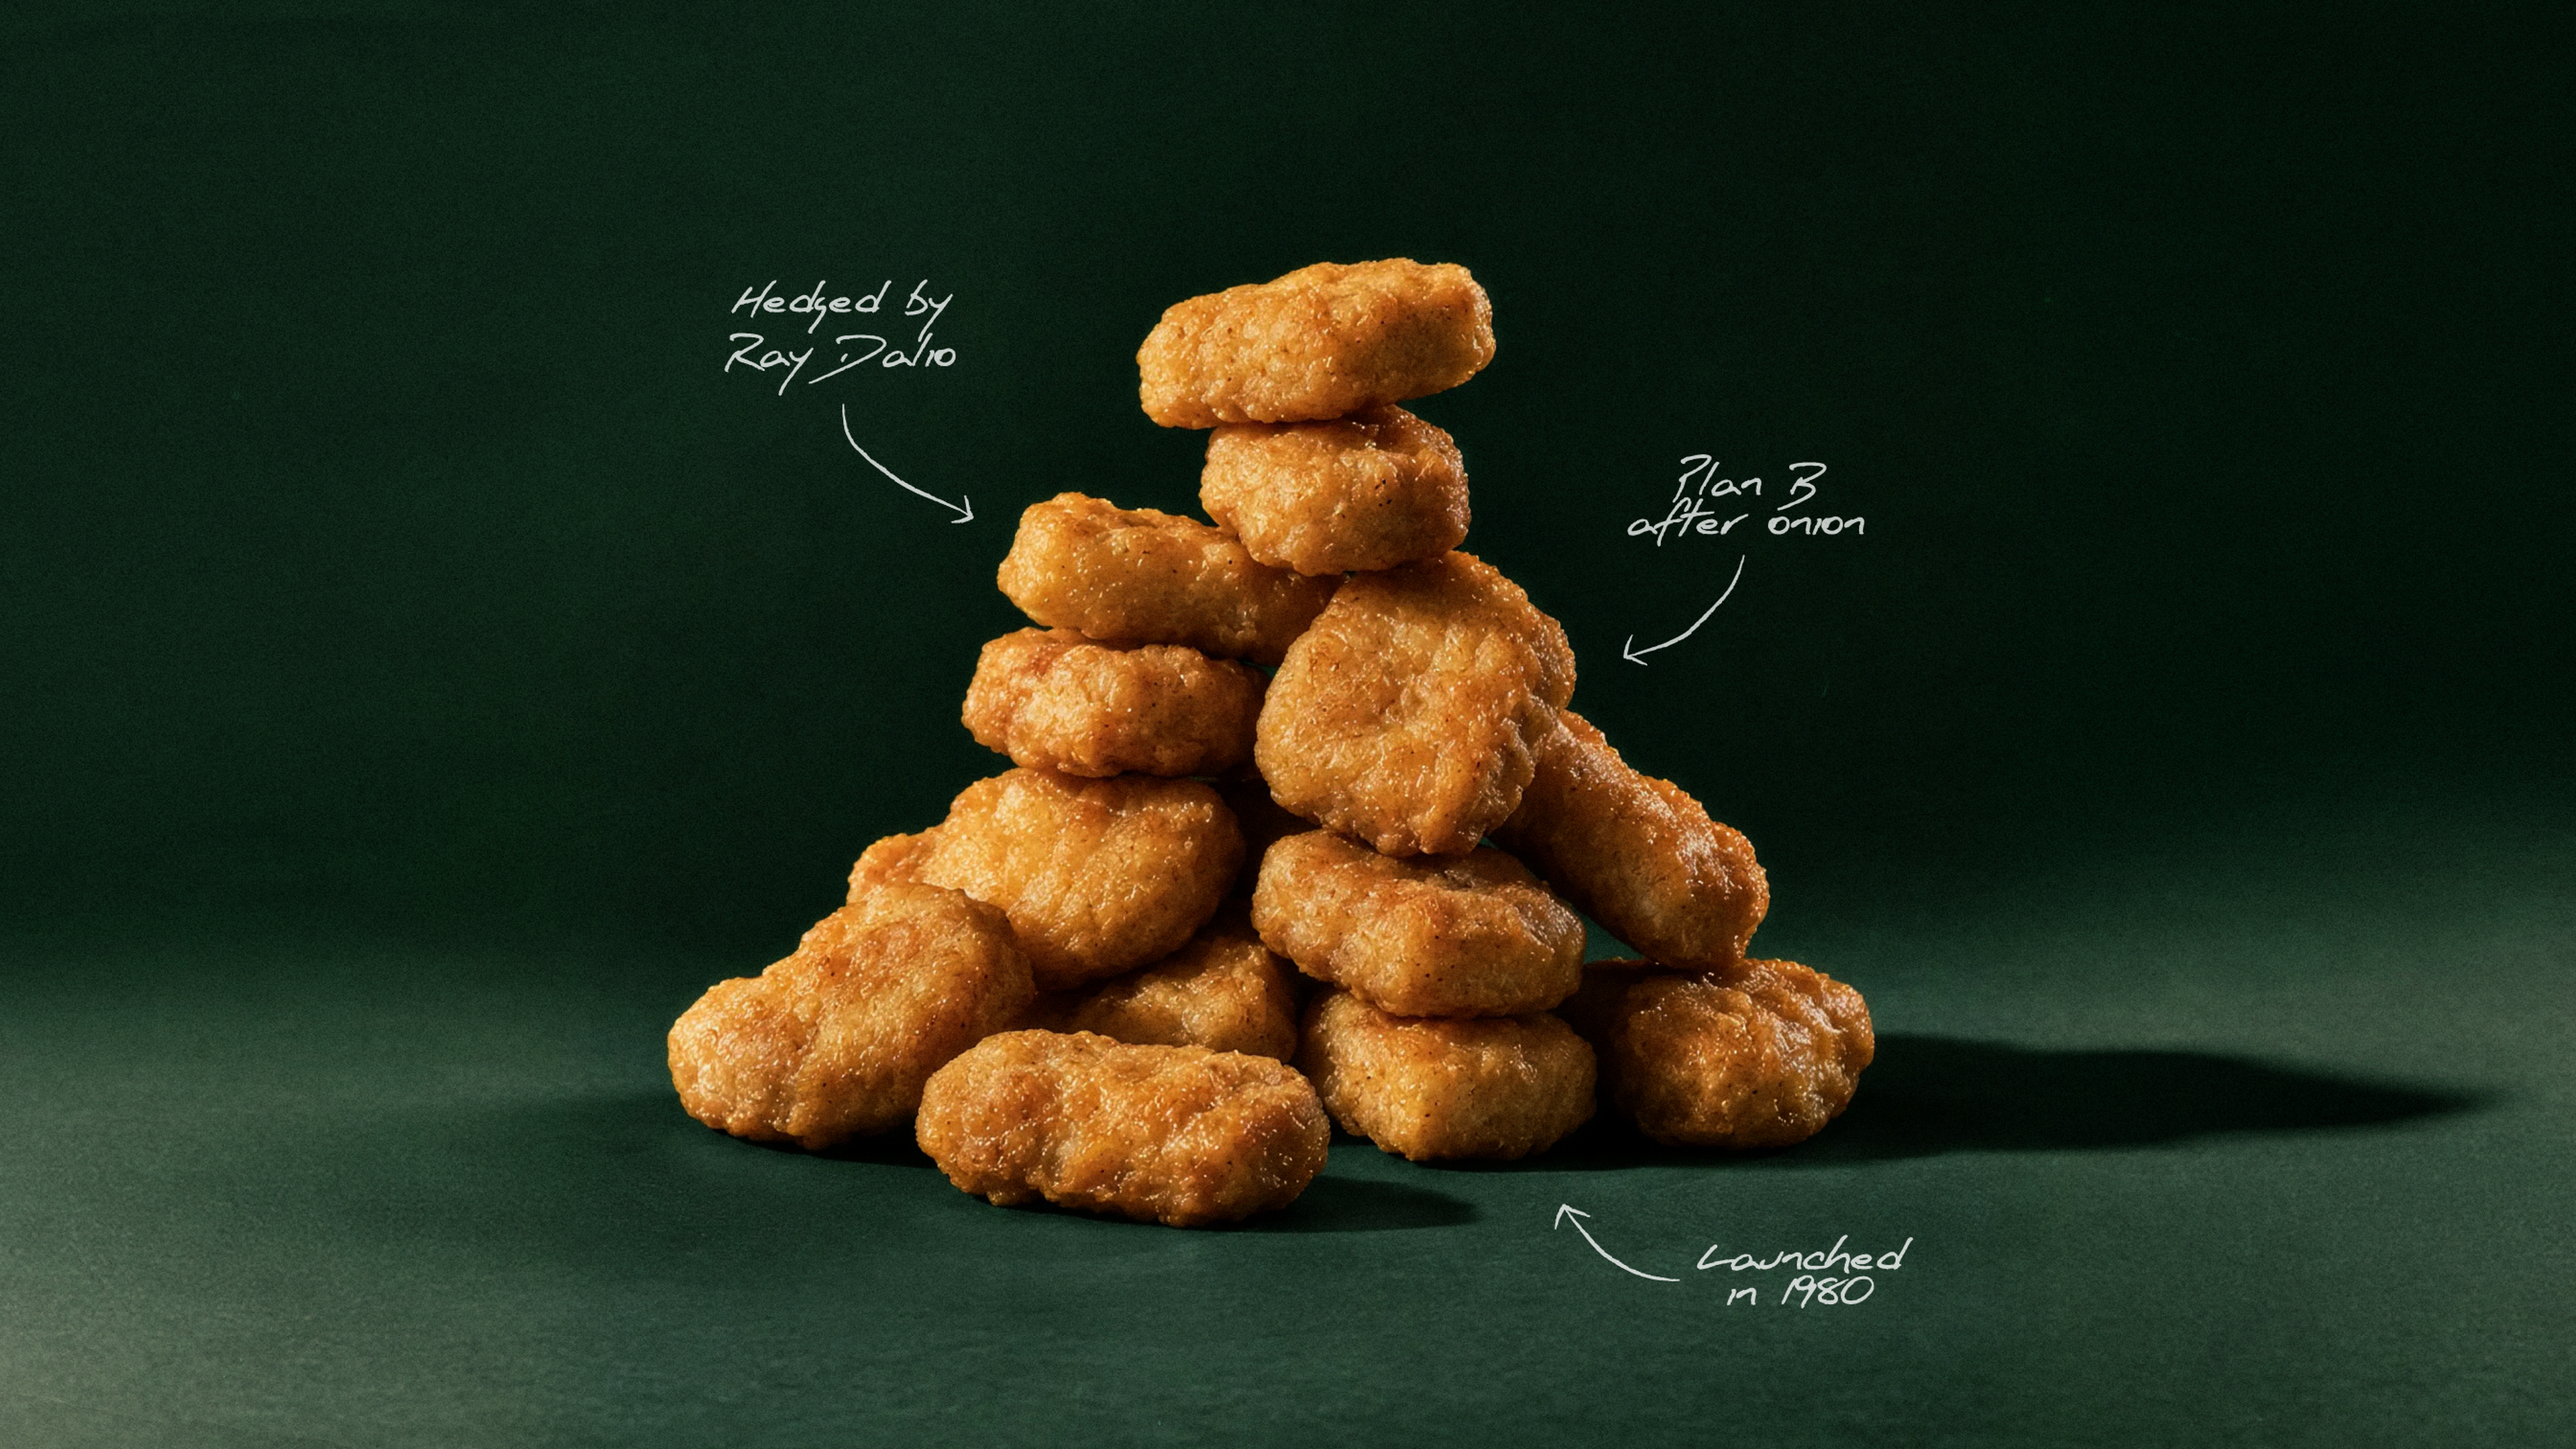
Winner, Winner: The Chicken McNugget Story
How a 1940s breeding contest, a Cornell food scientist, and a hedge by Ray Dalio helped McDonald's turn the Chicken McNugget into a fast-food icon.

Q2FY27 revenue was ₹3,897 crore, up 13%; India volume growth was 10% and International constant-currency growth was 13%.
Q2 EBITDA rose 27% to ₹709 crore and reported and recurring PAT increased 31% to ₹550 crore; consolidated net profit was ₹558 crore.
H1 revenue rose 18% to ₹7,854 crore, EBITDA increased 26% to ₹1,528 crore and PAT grew 28% to ₹1,180 crore; growth was broad-based across businesses.
More than 95% of India business gained or sustained MAT market share and penetration; Traditional and Organized Trade grew in double digits, with Quick Commerce accelerating.
Q2 gross margin expanded ~600 bps YoY; EBITDA margin rose 200 bps to 18.2%, despite A&P spending increasing 44%.
H1 EBITDA margin was 19.5%, up 130 bps; Q2 PBT was ₹674 crore, up 23%, and H1 PBT was ₹1,464 crore, up 21%.
Two-year compounded growth was 22% for revenue and 17% for EBITDA; India volume growth was 8% and International constant-currency growth was 16%.
Material cost was 51.9% of Q2 revenue versus 57.9% a year earlier; PBDIT before A&P was 29.8% versus 25.3%.
FY27 outlook: teens revenue growth, revenue comfortably above ₹15,000 crore, mid-20s EBITDA growth and double-digit India volume growth; management expects EBITDA growth of at least 24%–25%.
EBITDA margin could expand 120–150 bps in FY27; profit growth from FY28 is expected to be mid-teens.
Medium-term construct: high-single-digit India growth, mid-teens International growth and ~3% inflation; ₹20,000 crore revenue by FY29 remains an organic-growth aspiration.
Growth portfolio is expected to deliver 20%–25% growth with improving profitability; Parachute and Saffola are expected to grow mid-single digits, while value-added hair oils target double-digit value growth.
Vision 2030 targets include ₹20,000 crore revenue, double-digit revenue growth and mid-teens EBITDA CAGR; India Foods and Premium Personal Care share targeted at ~33% by FY30.

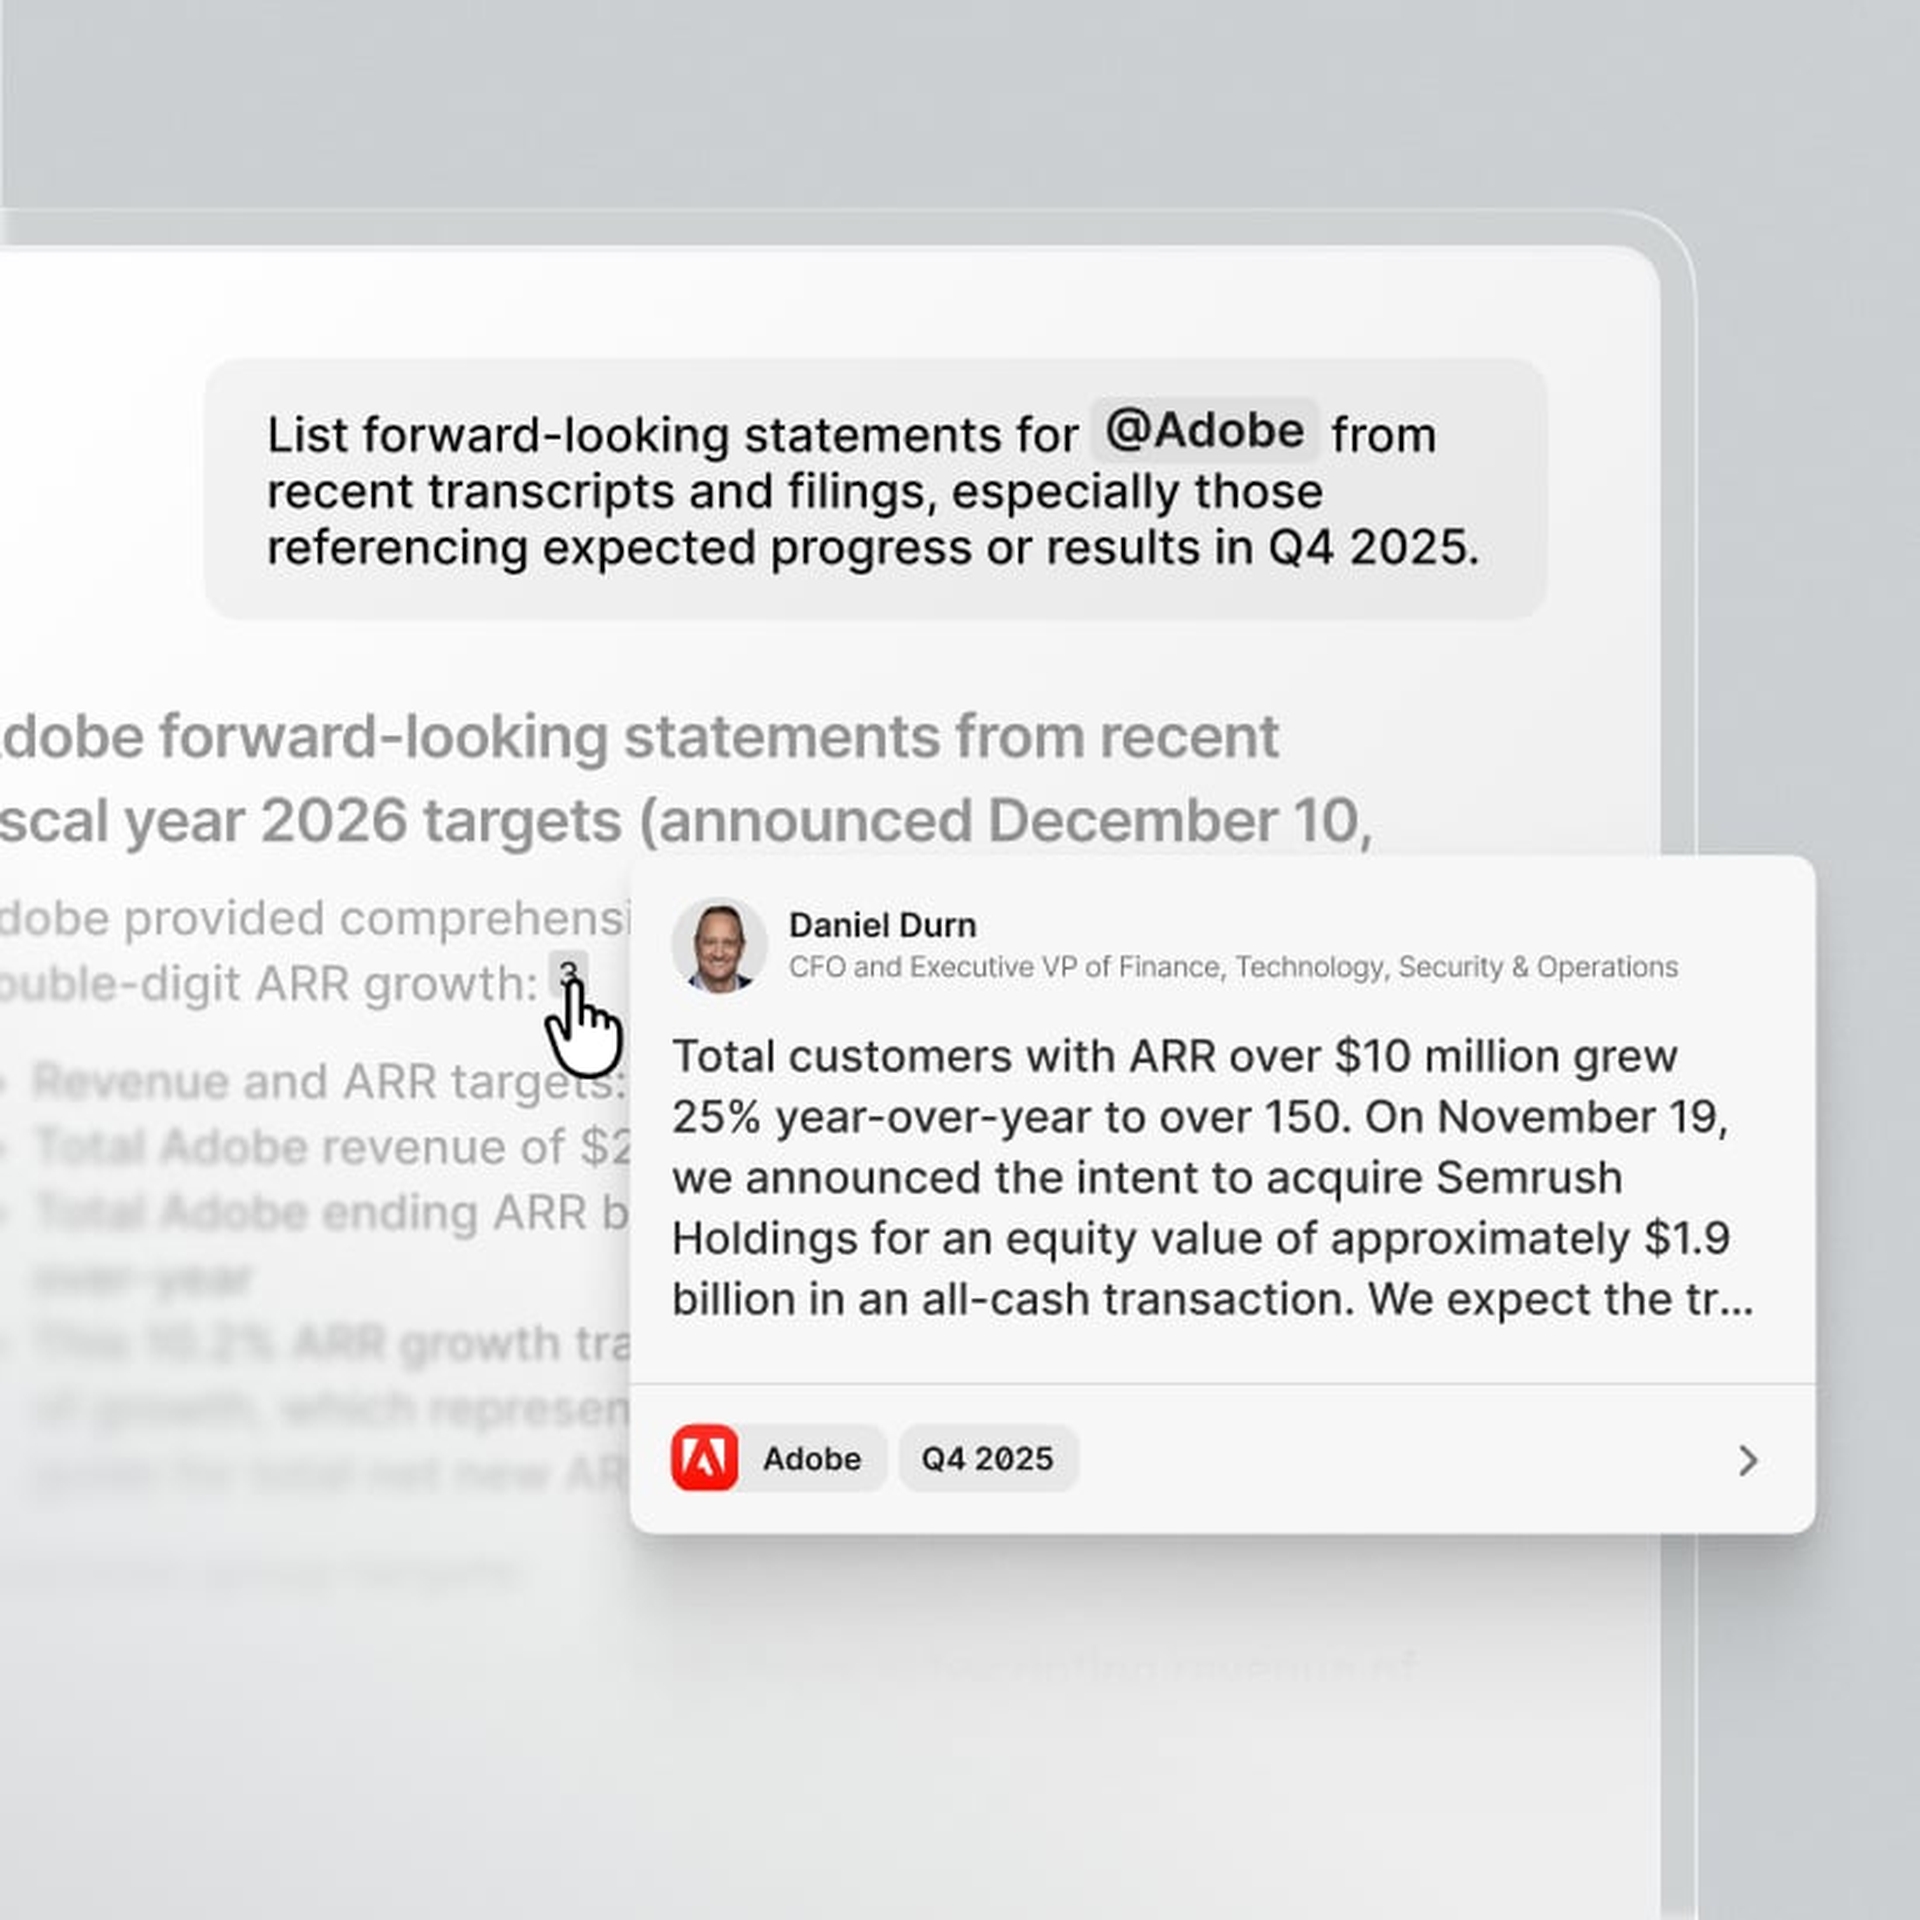
AI chat
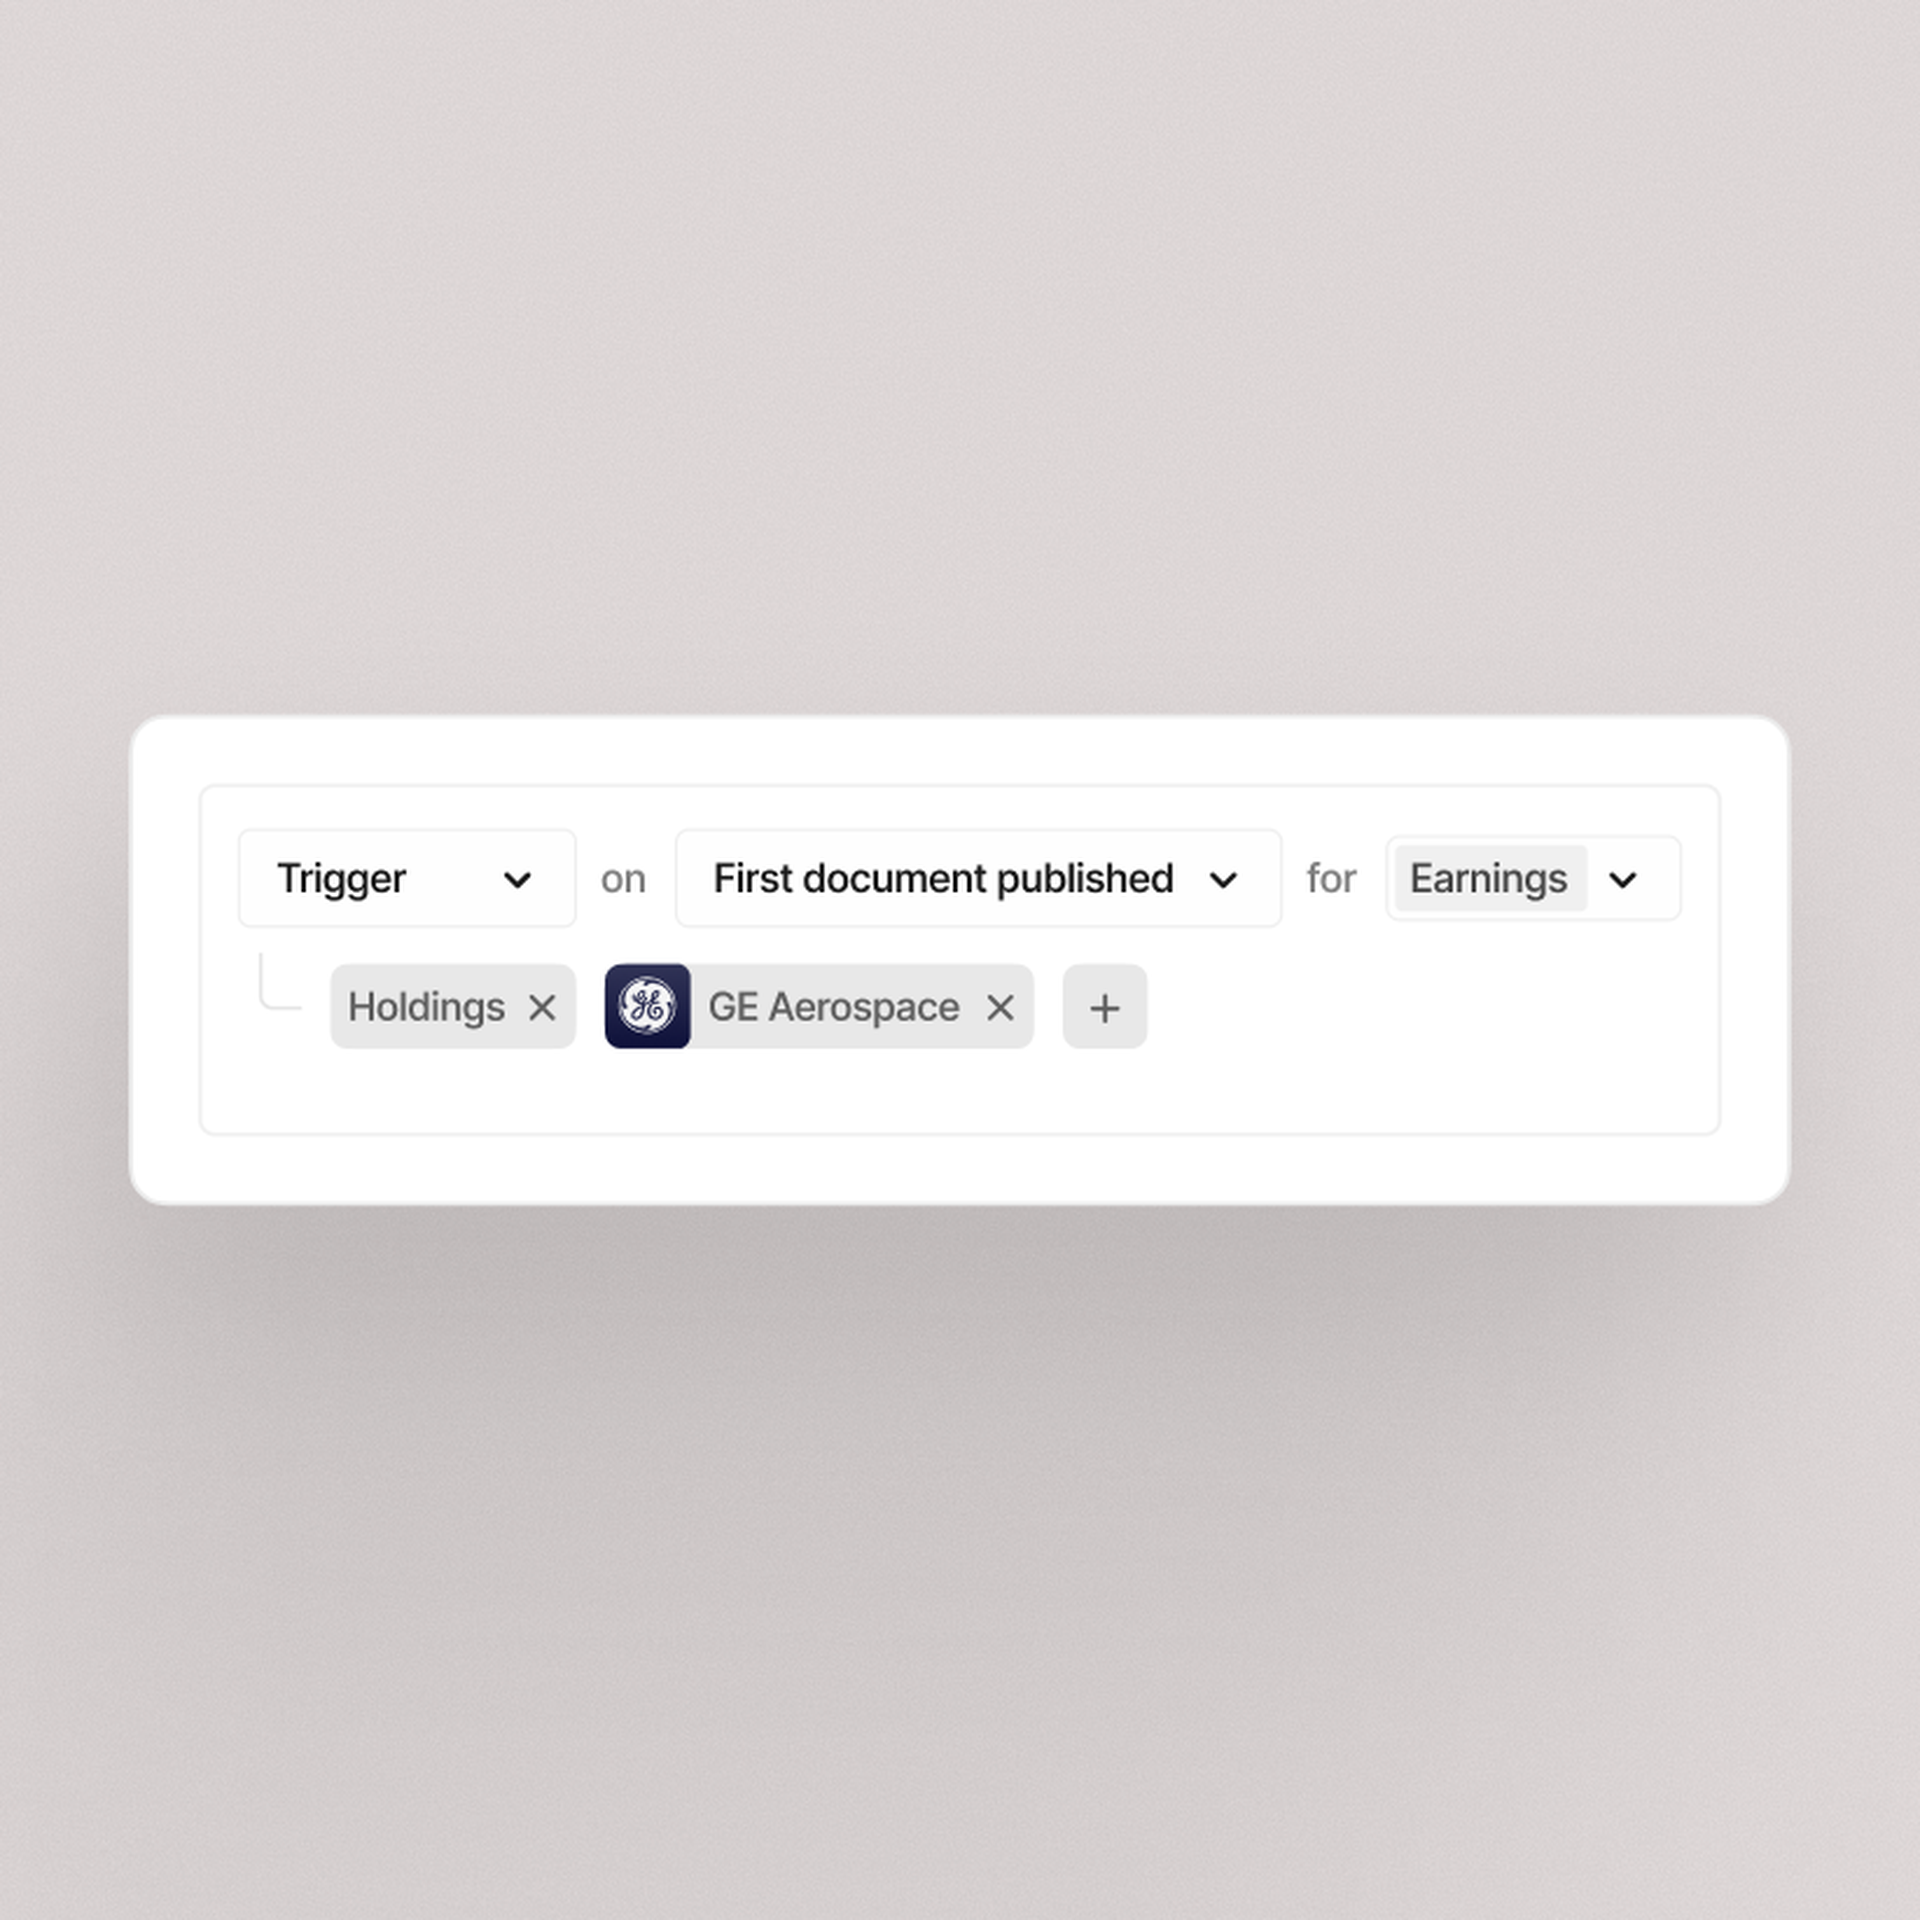
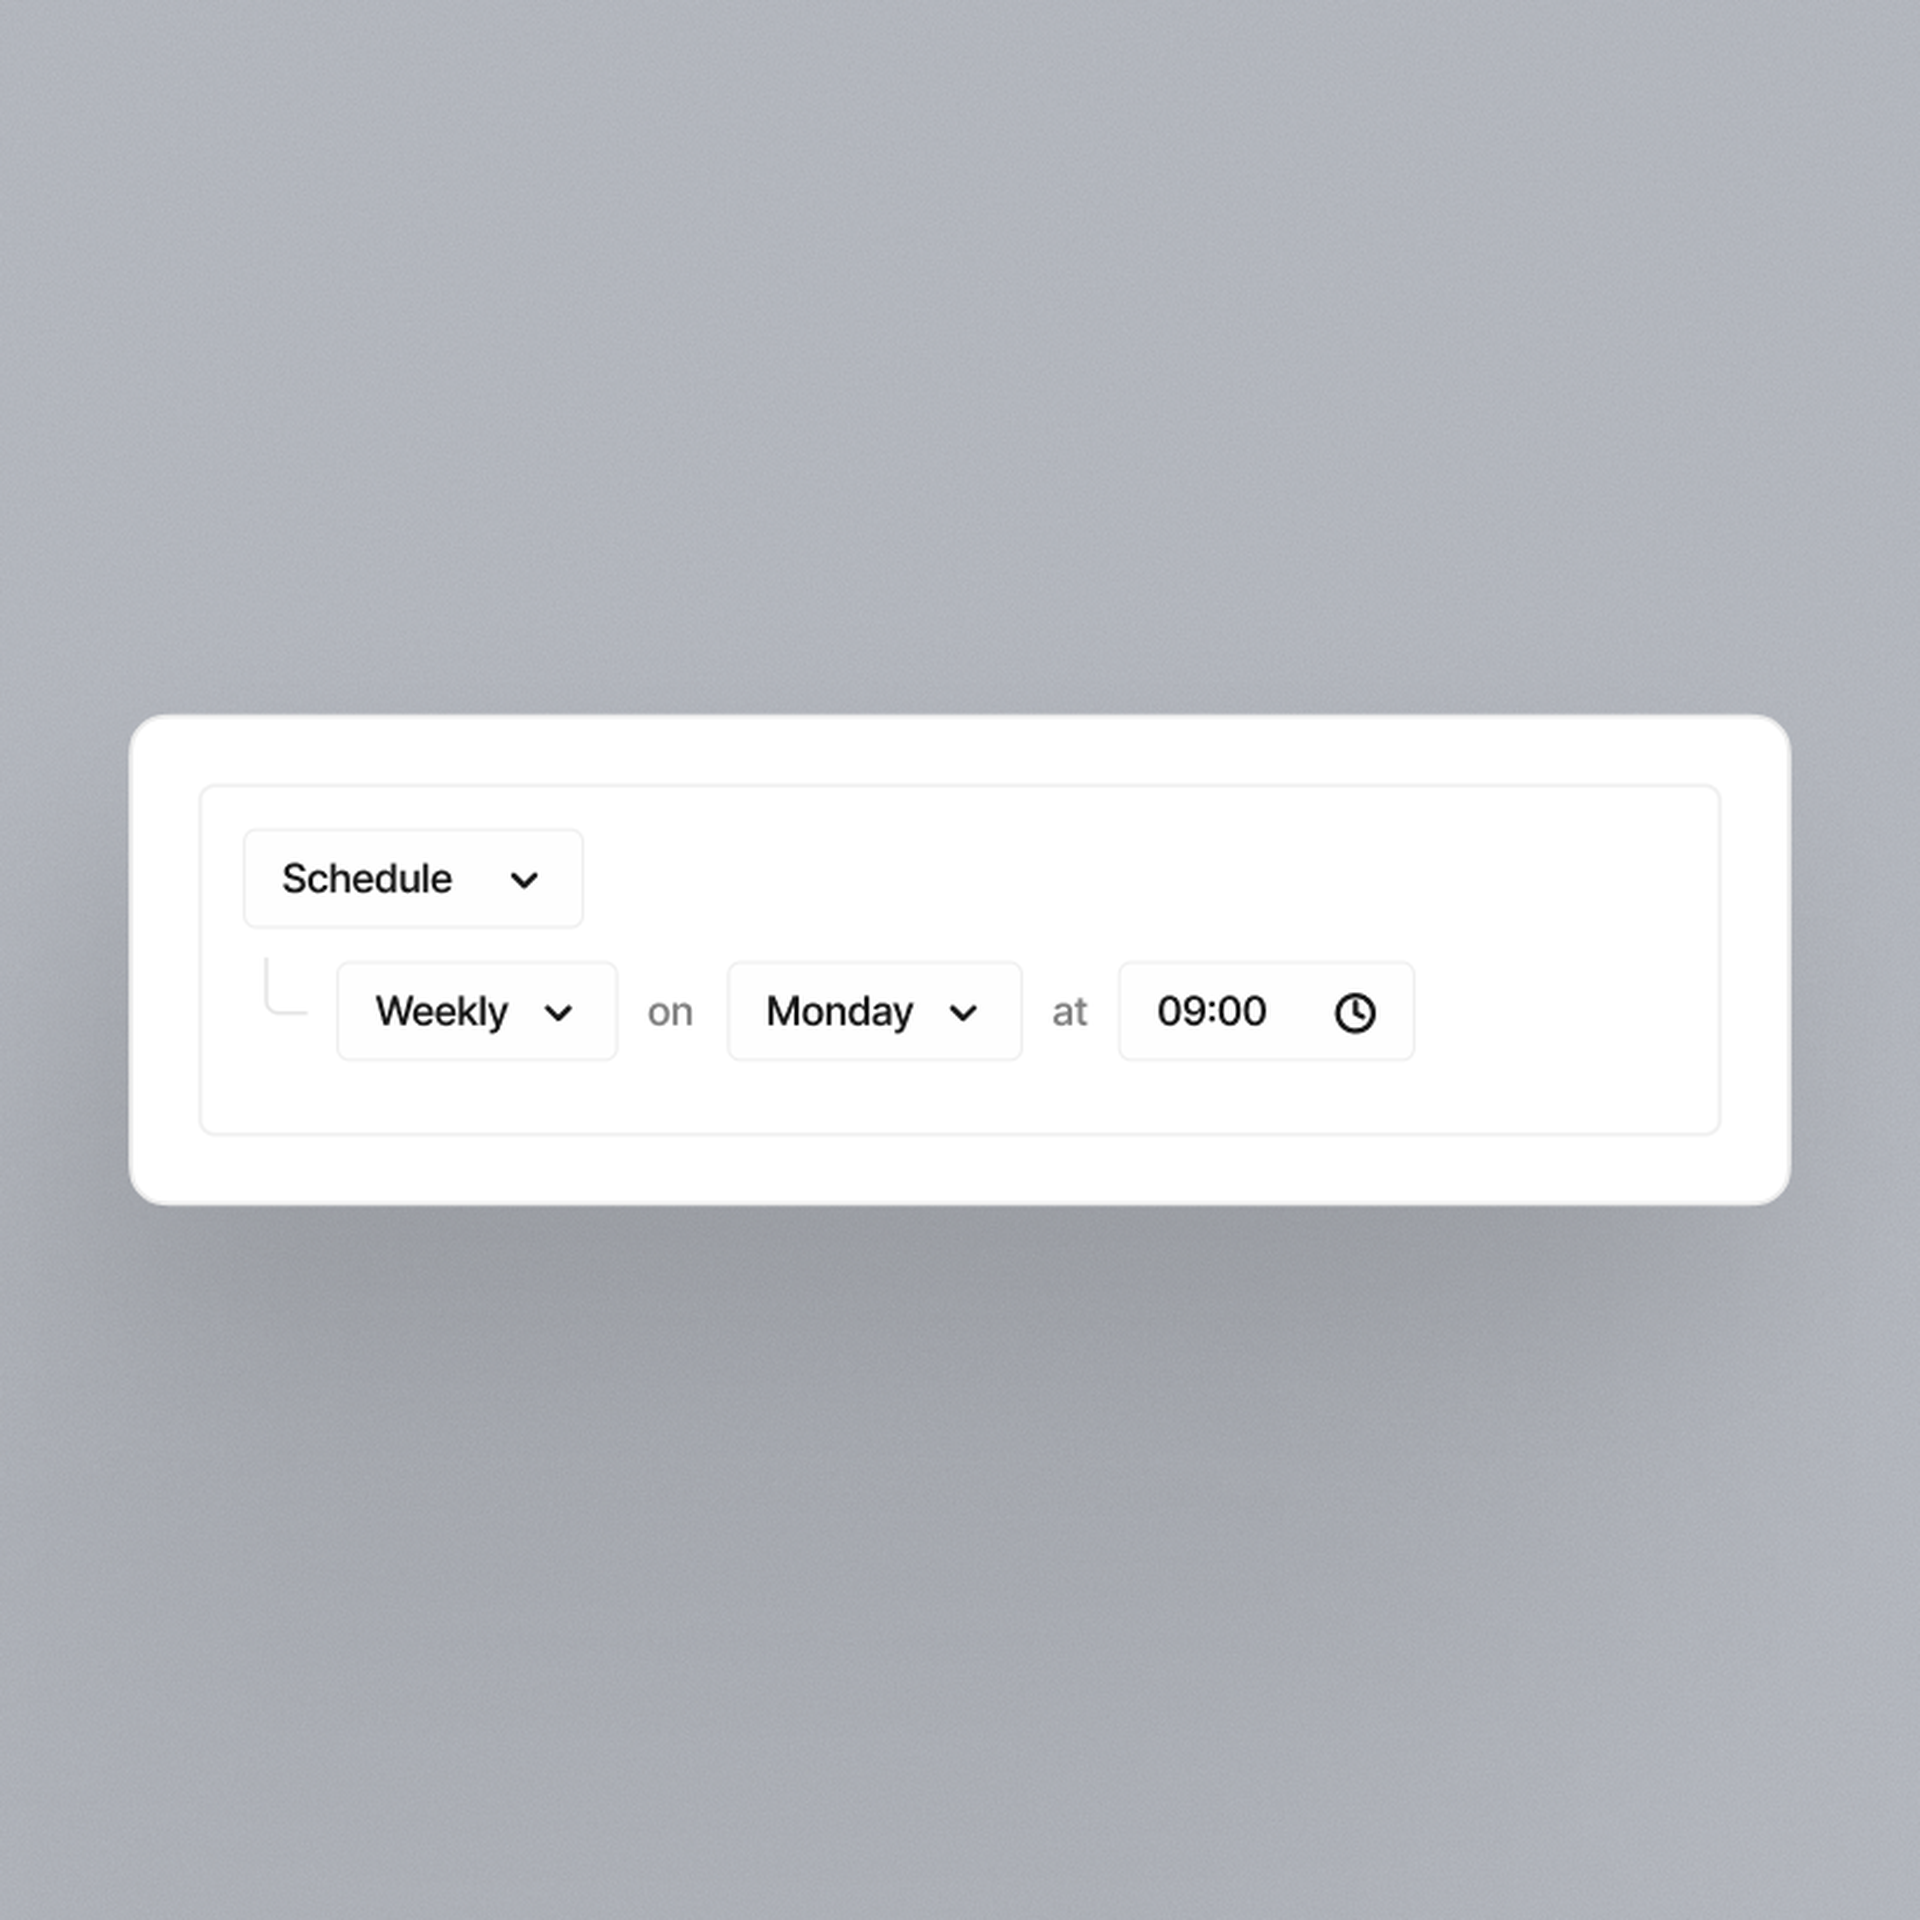
Automations
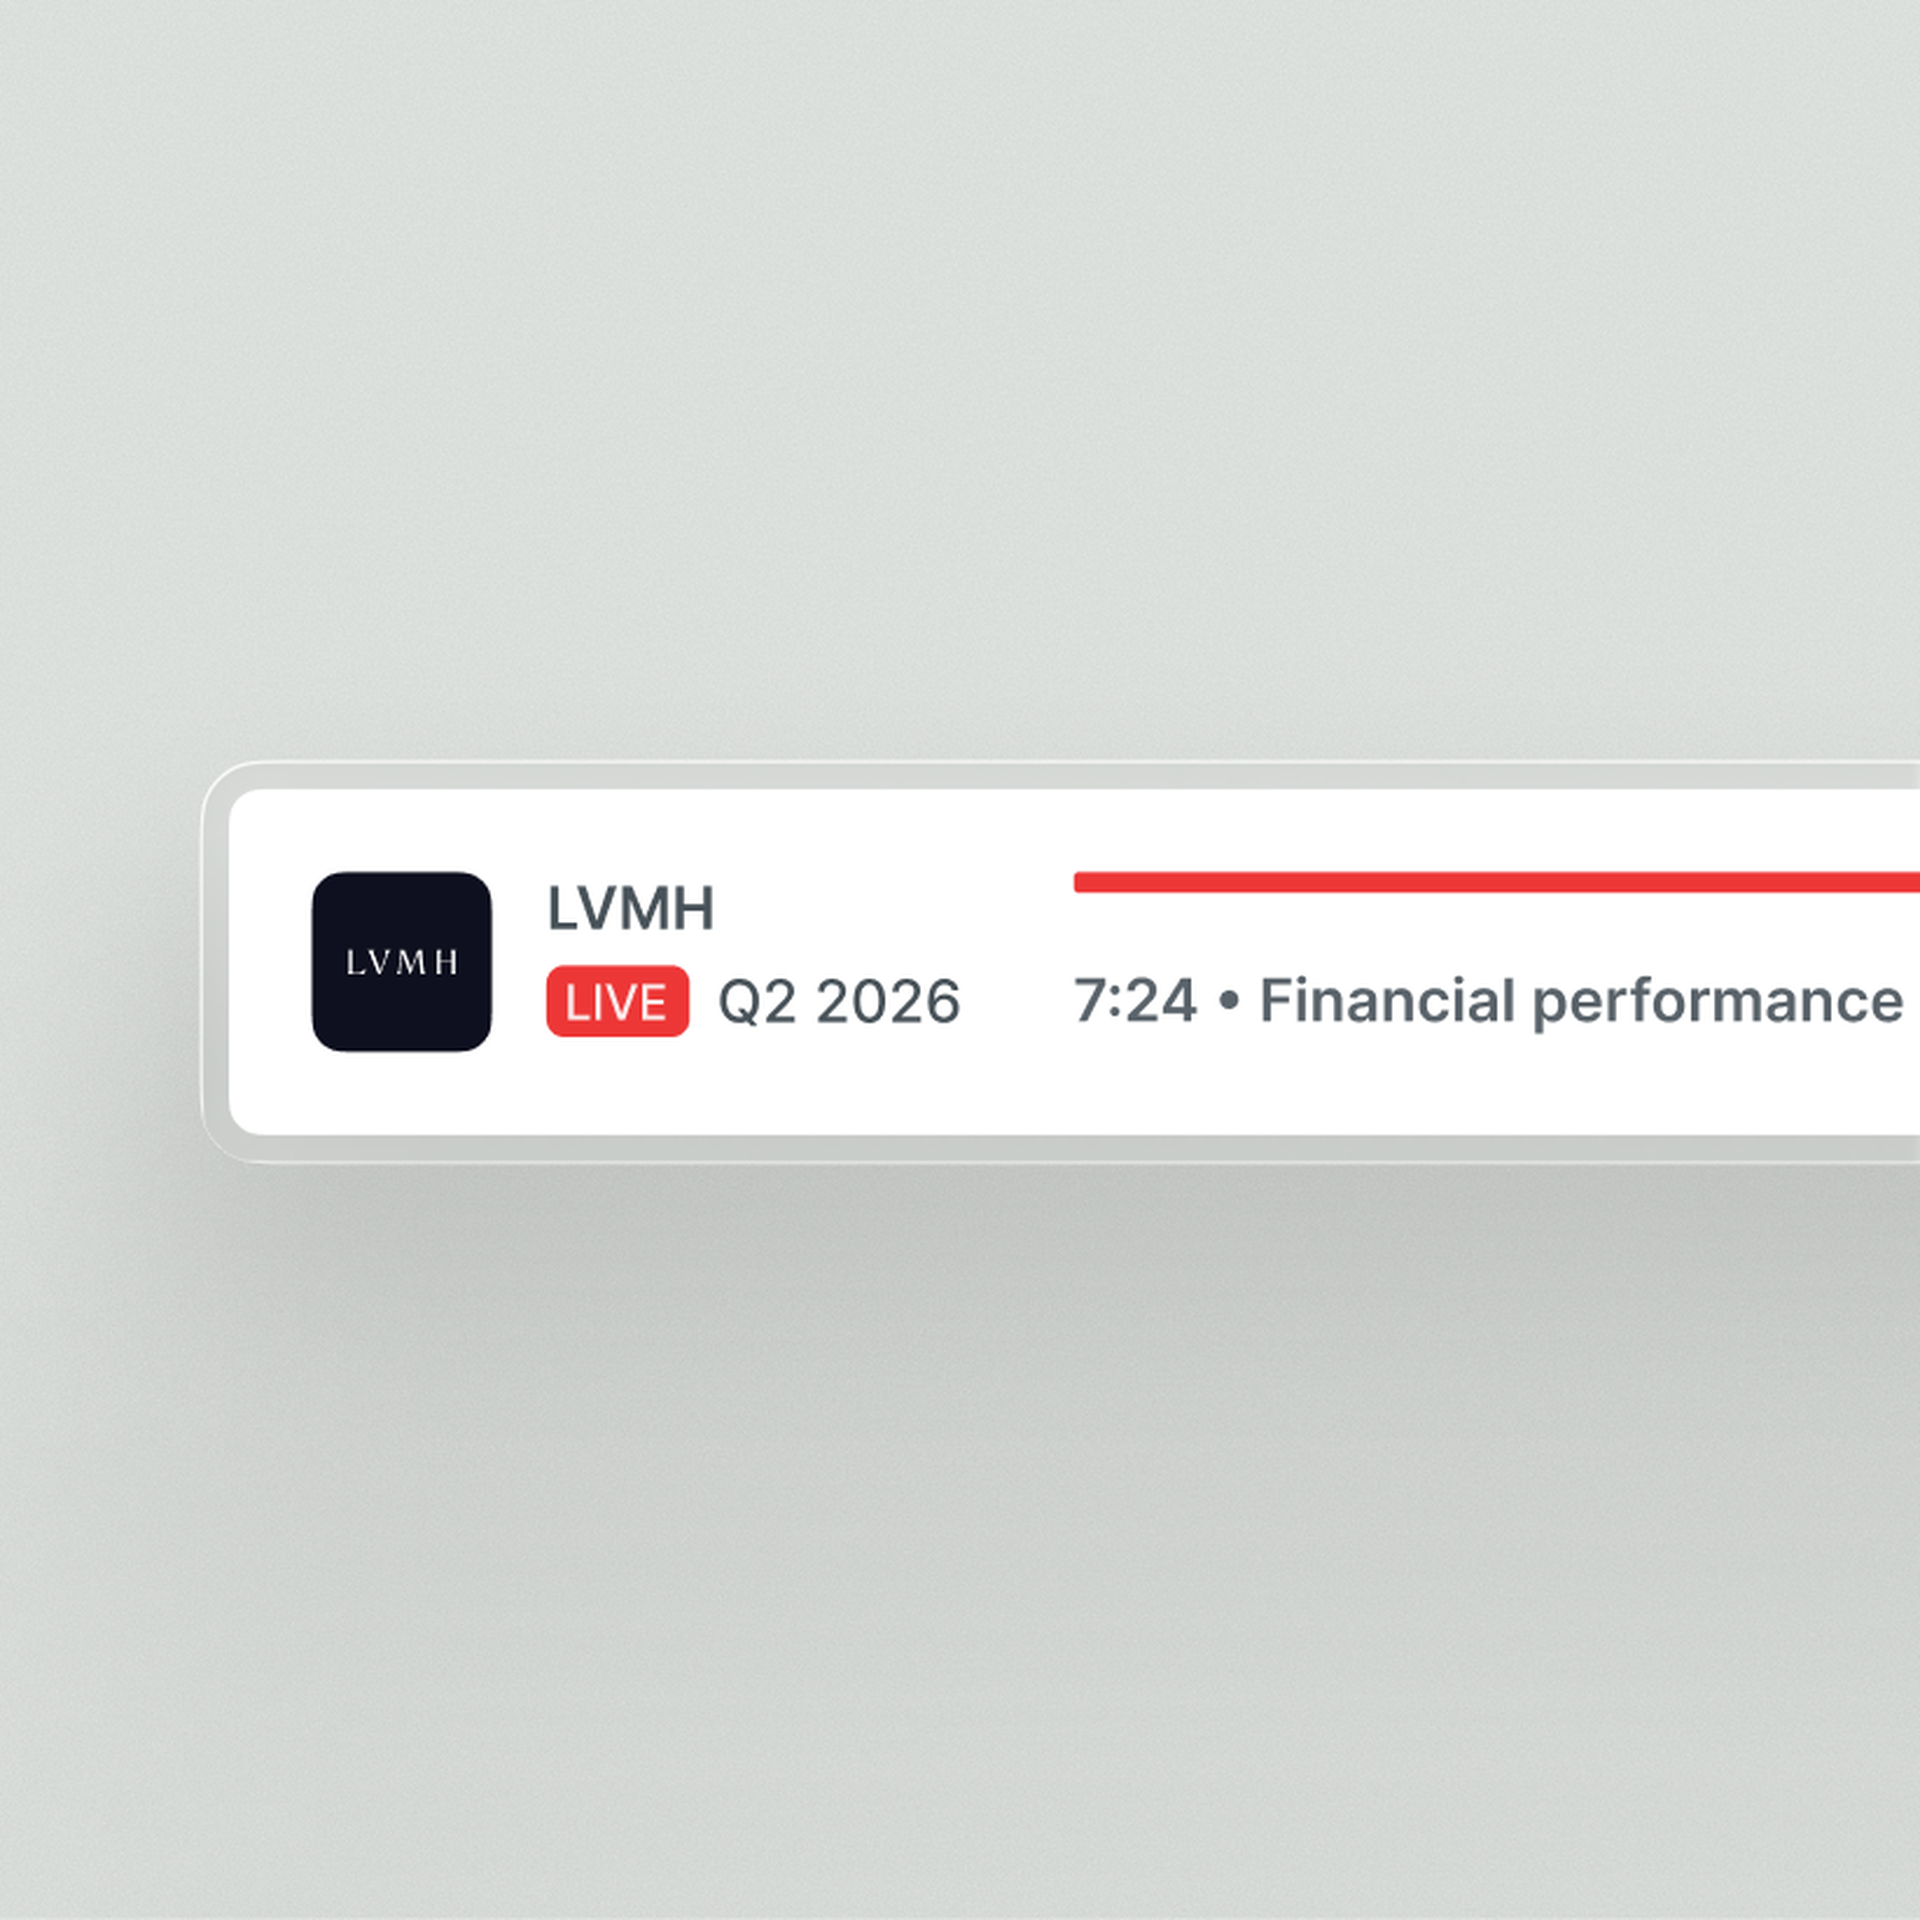
Live audio & transcripts
Quartr's AI stands out because it only pulls clean, first-party data from public companies. In investing, that's everything.
Jamie Ross
Investment Manager, GAM Investments
Research that used to take hours now takes seconds with Quartr Pro. Tracking shifts in tone or extracting tables, it's as simple as typing a query.
Tom O'Hara
Investment Director
Before Quartr we spent hours manually compiling insights through the peer earnings cycle. Now, these tasks are done faster, with greater precision.
Gregg Lampf
VP of Investor Relations
Being able to ask specific questions across years of transcripts and reports and instantly get verified answers is a game-changer.
Pontus Dackmo
CEO & Investment Manager