Edge16 Oct 2026
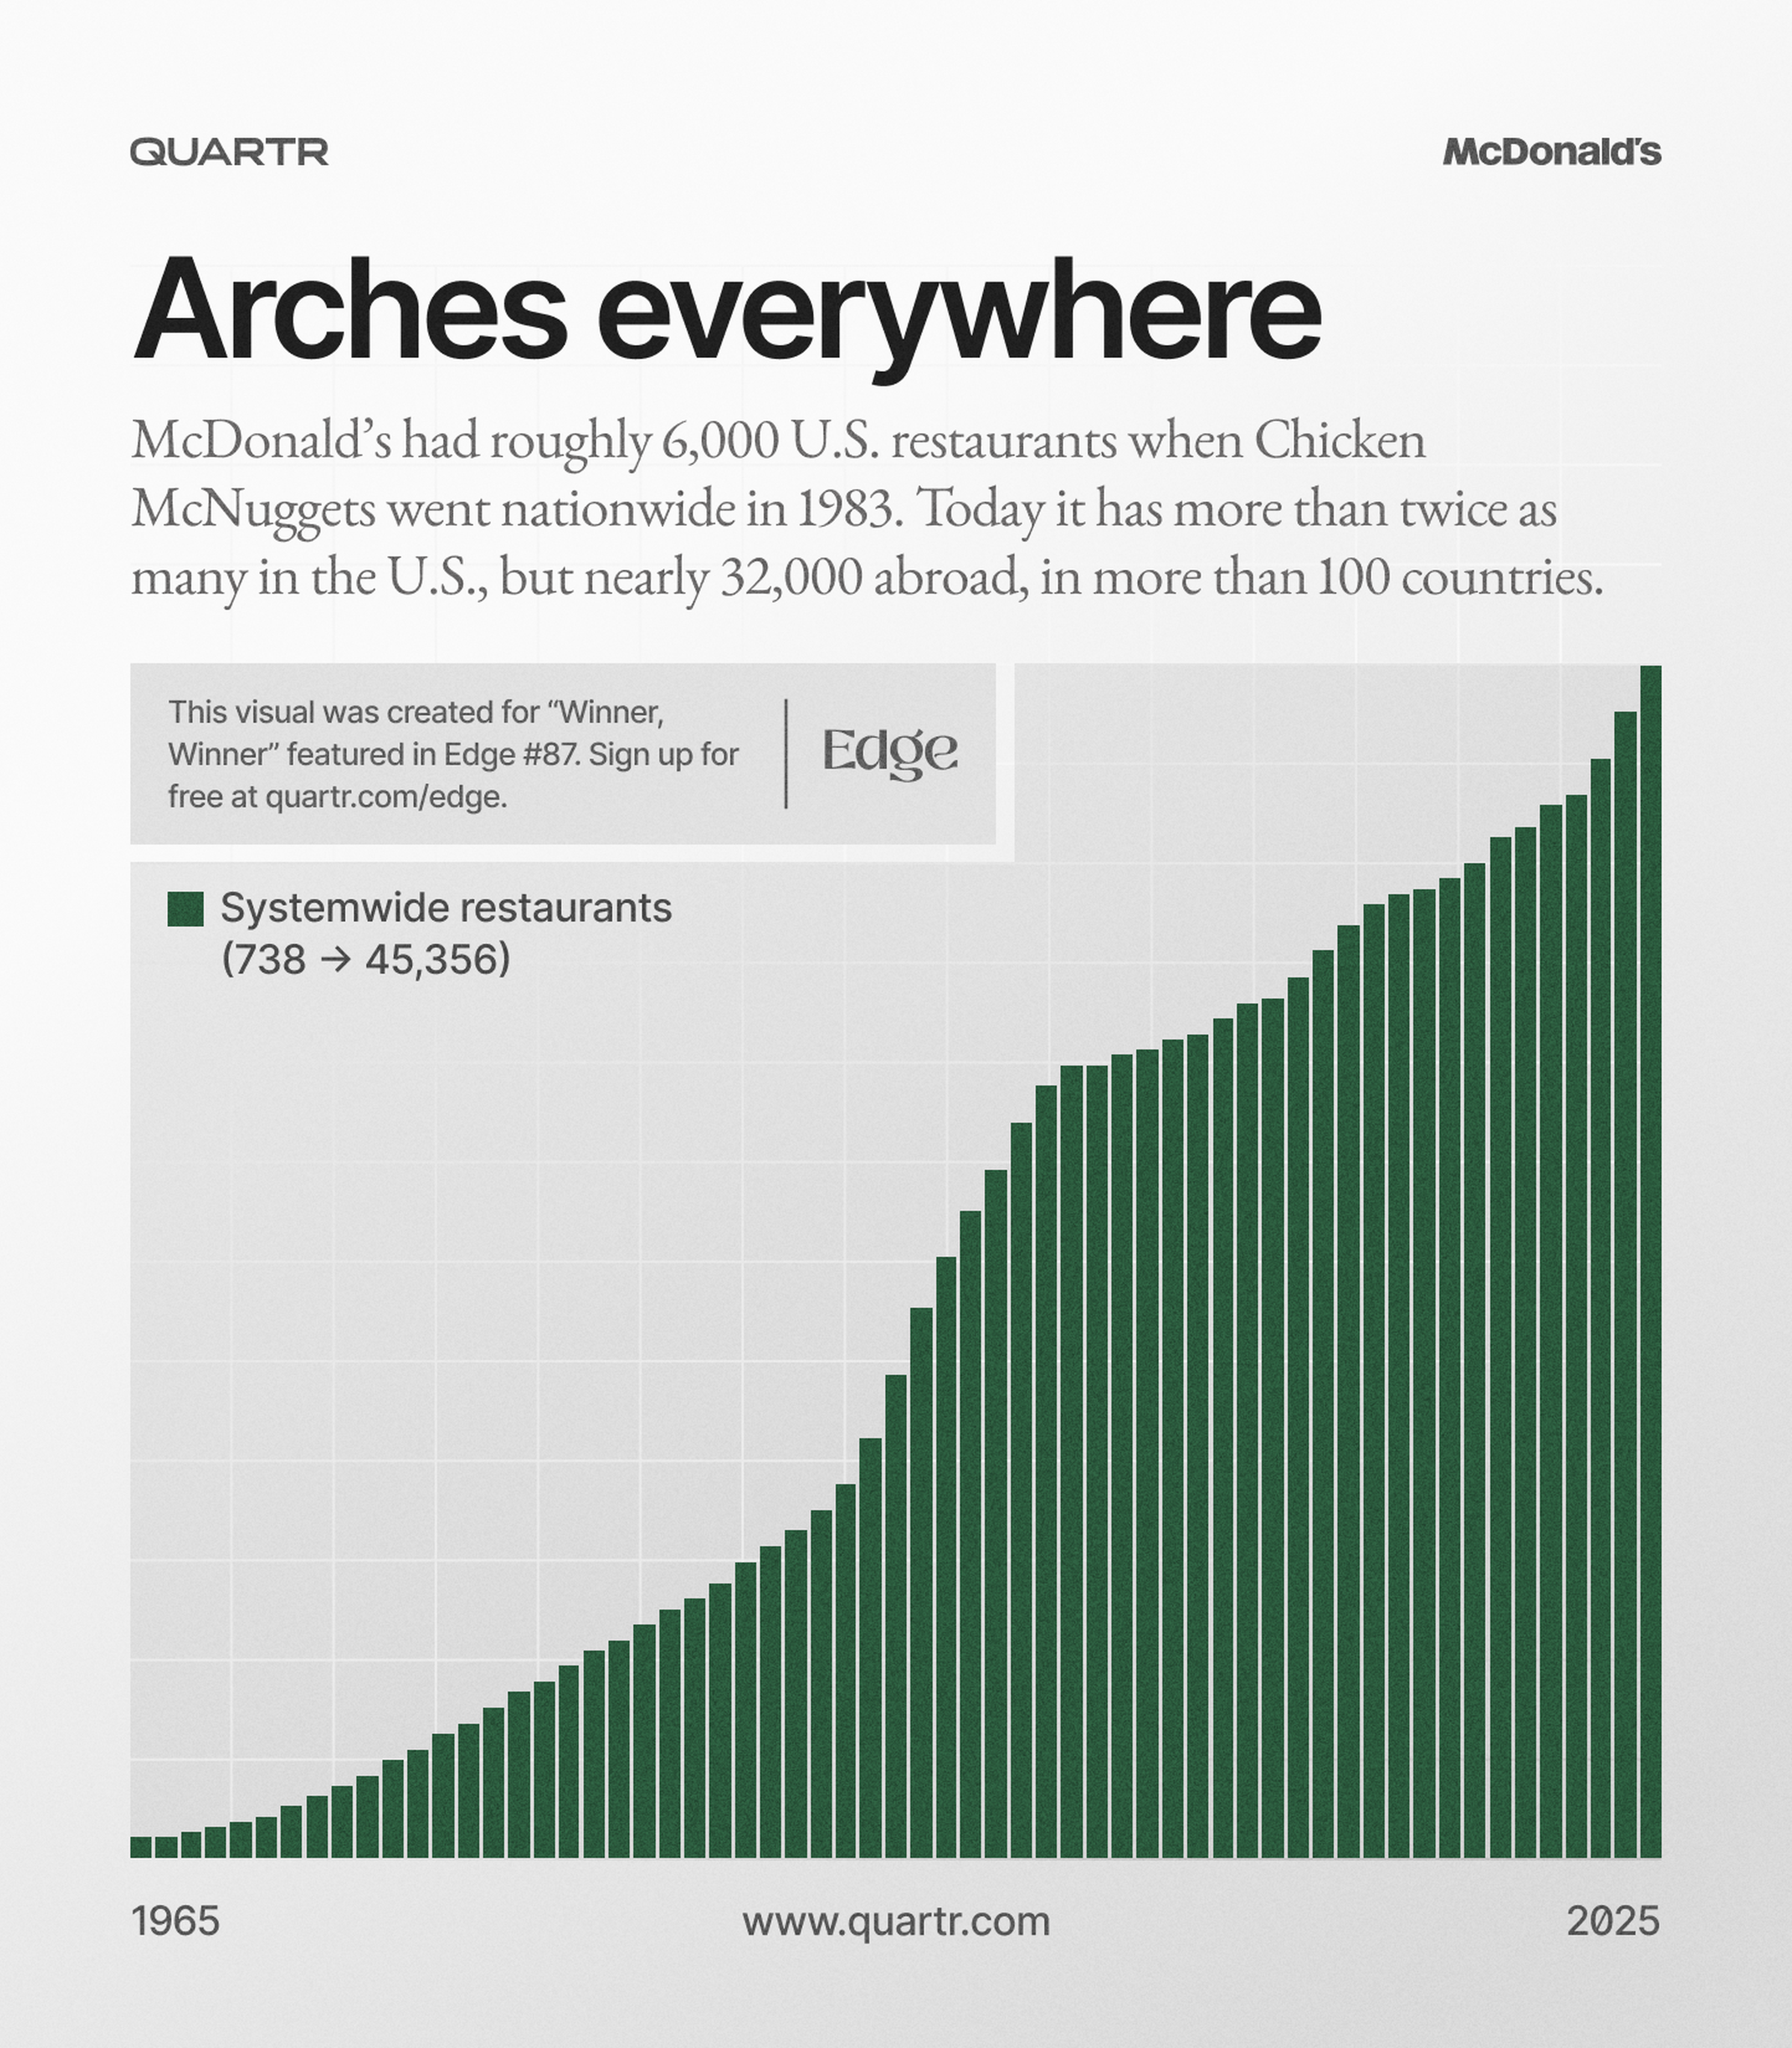
Winner, Winner: The Chicken McNugget Story
How a 1940s breeding contest, a Cornell food scientist, and a hedge by Ray Dalio helped McDonald's turn the Chicken McNugget into a fast-food icon.

Q4 FY26 revenue was $657M, up 27% YoY; FY26 revenue reached $2.535B, up 27%, marking the strongest financial year.
Q4 non-GAAP EPS rose 43% to $11.10; FY26 non-GAAP EPS increased 44% to $42.99. FY26 free cash flow was $1.034B, up 40%.
Q4 GAAP net income was $175M, up 13%, and diluted EPS was $8.12, up 26%; FY26 GAAP net income was $835M, up 28%, and EPS was $36.32, up 37%.
Q4 operating income was $266.6M; FY26 operating income was $1.266B.
Q4 adjusted EBITDA was $404.6M, or 62% of revenue; FY26 adjusted EBITDA was $1.561B, also 62% of revenue.
Q4 free cash flow was $284.3M; FY26 operating cash flow was $1.072B and free cash flow was $1.034B.
FY27 guidance was deferred while bespoke mortgage pricing programs are negotiated and mortgage-market volumes and pricing remain uncertain.
Management expects very high platform growth rates in FY27, citing demand, pipeline and ACV bookings; no specific growth outlook was provided.
FY27 operating tax rate is expected to be 26%; professional services revenue is expected to decline significantly as resources shift to distribution and other strategic needs.

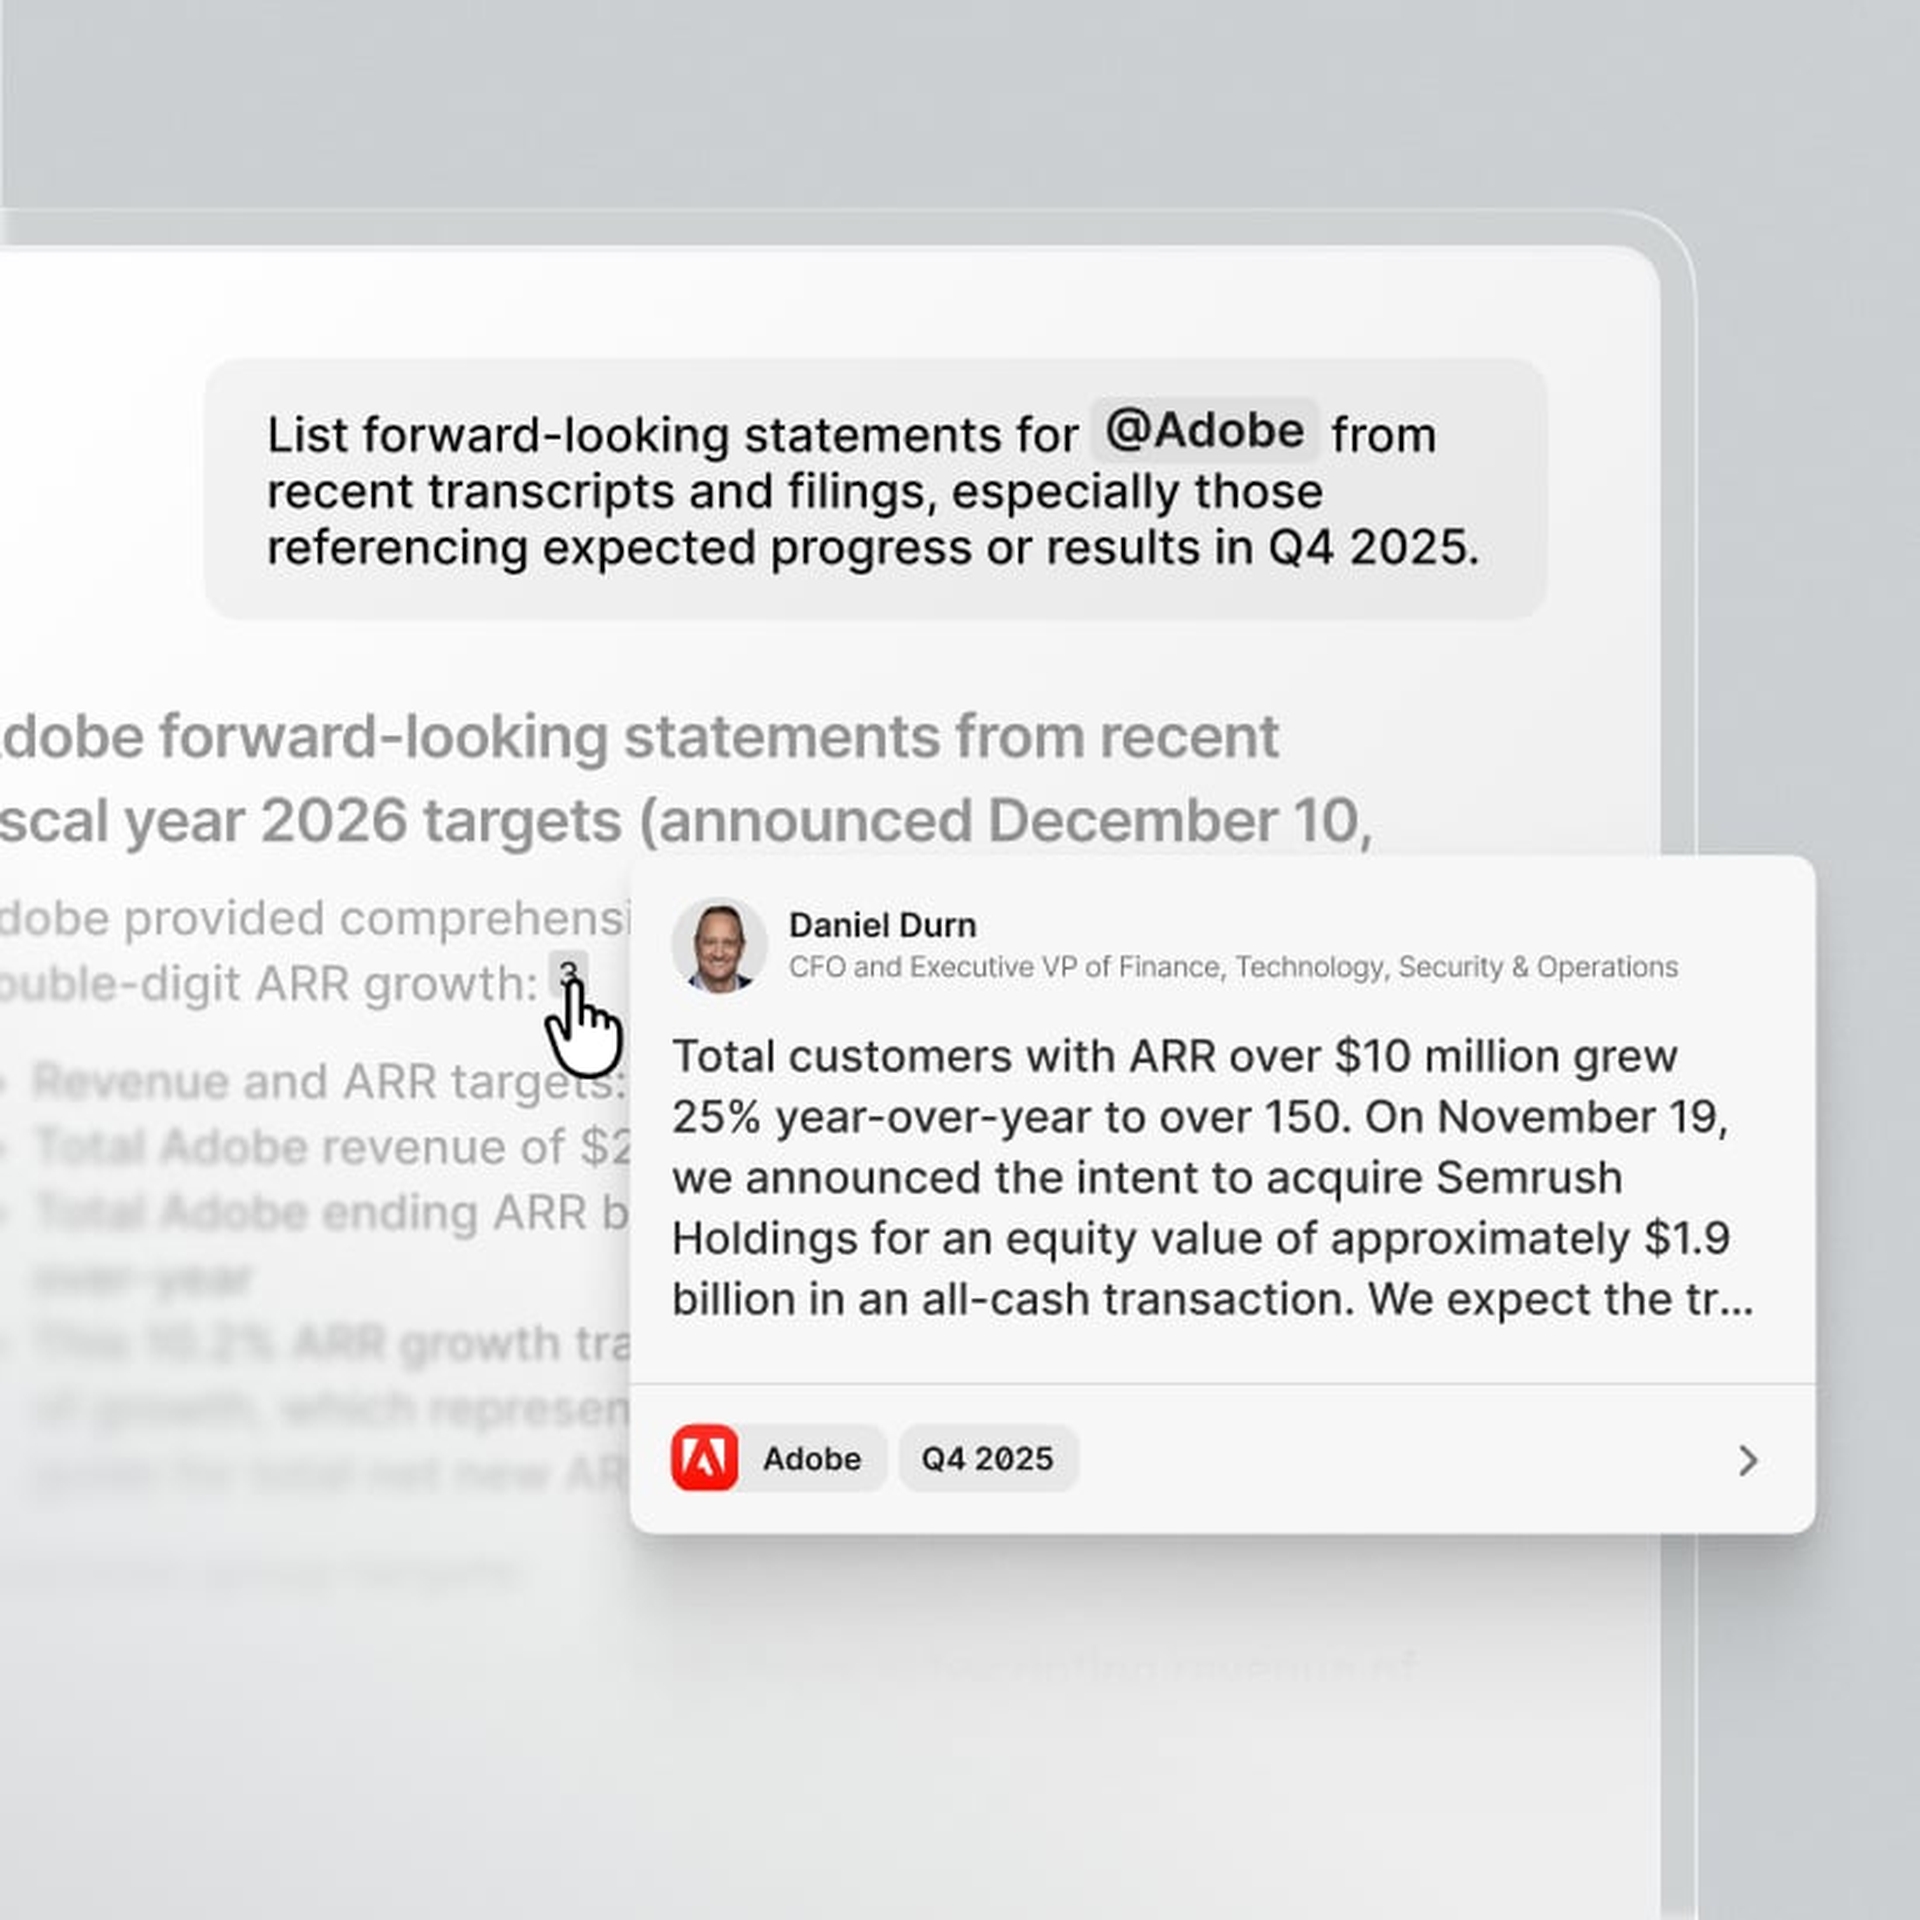
AI chat
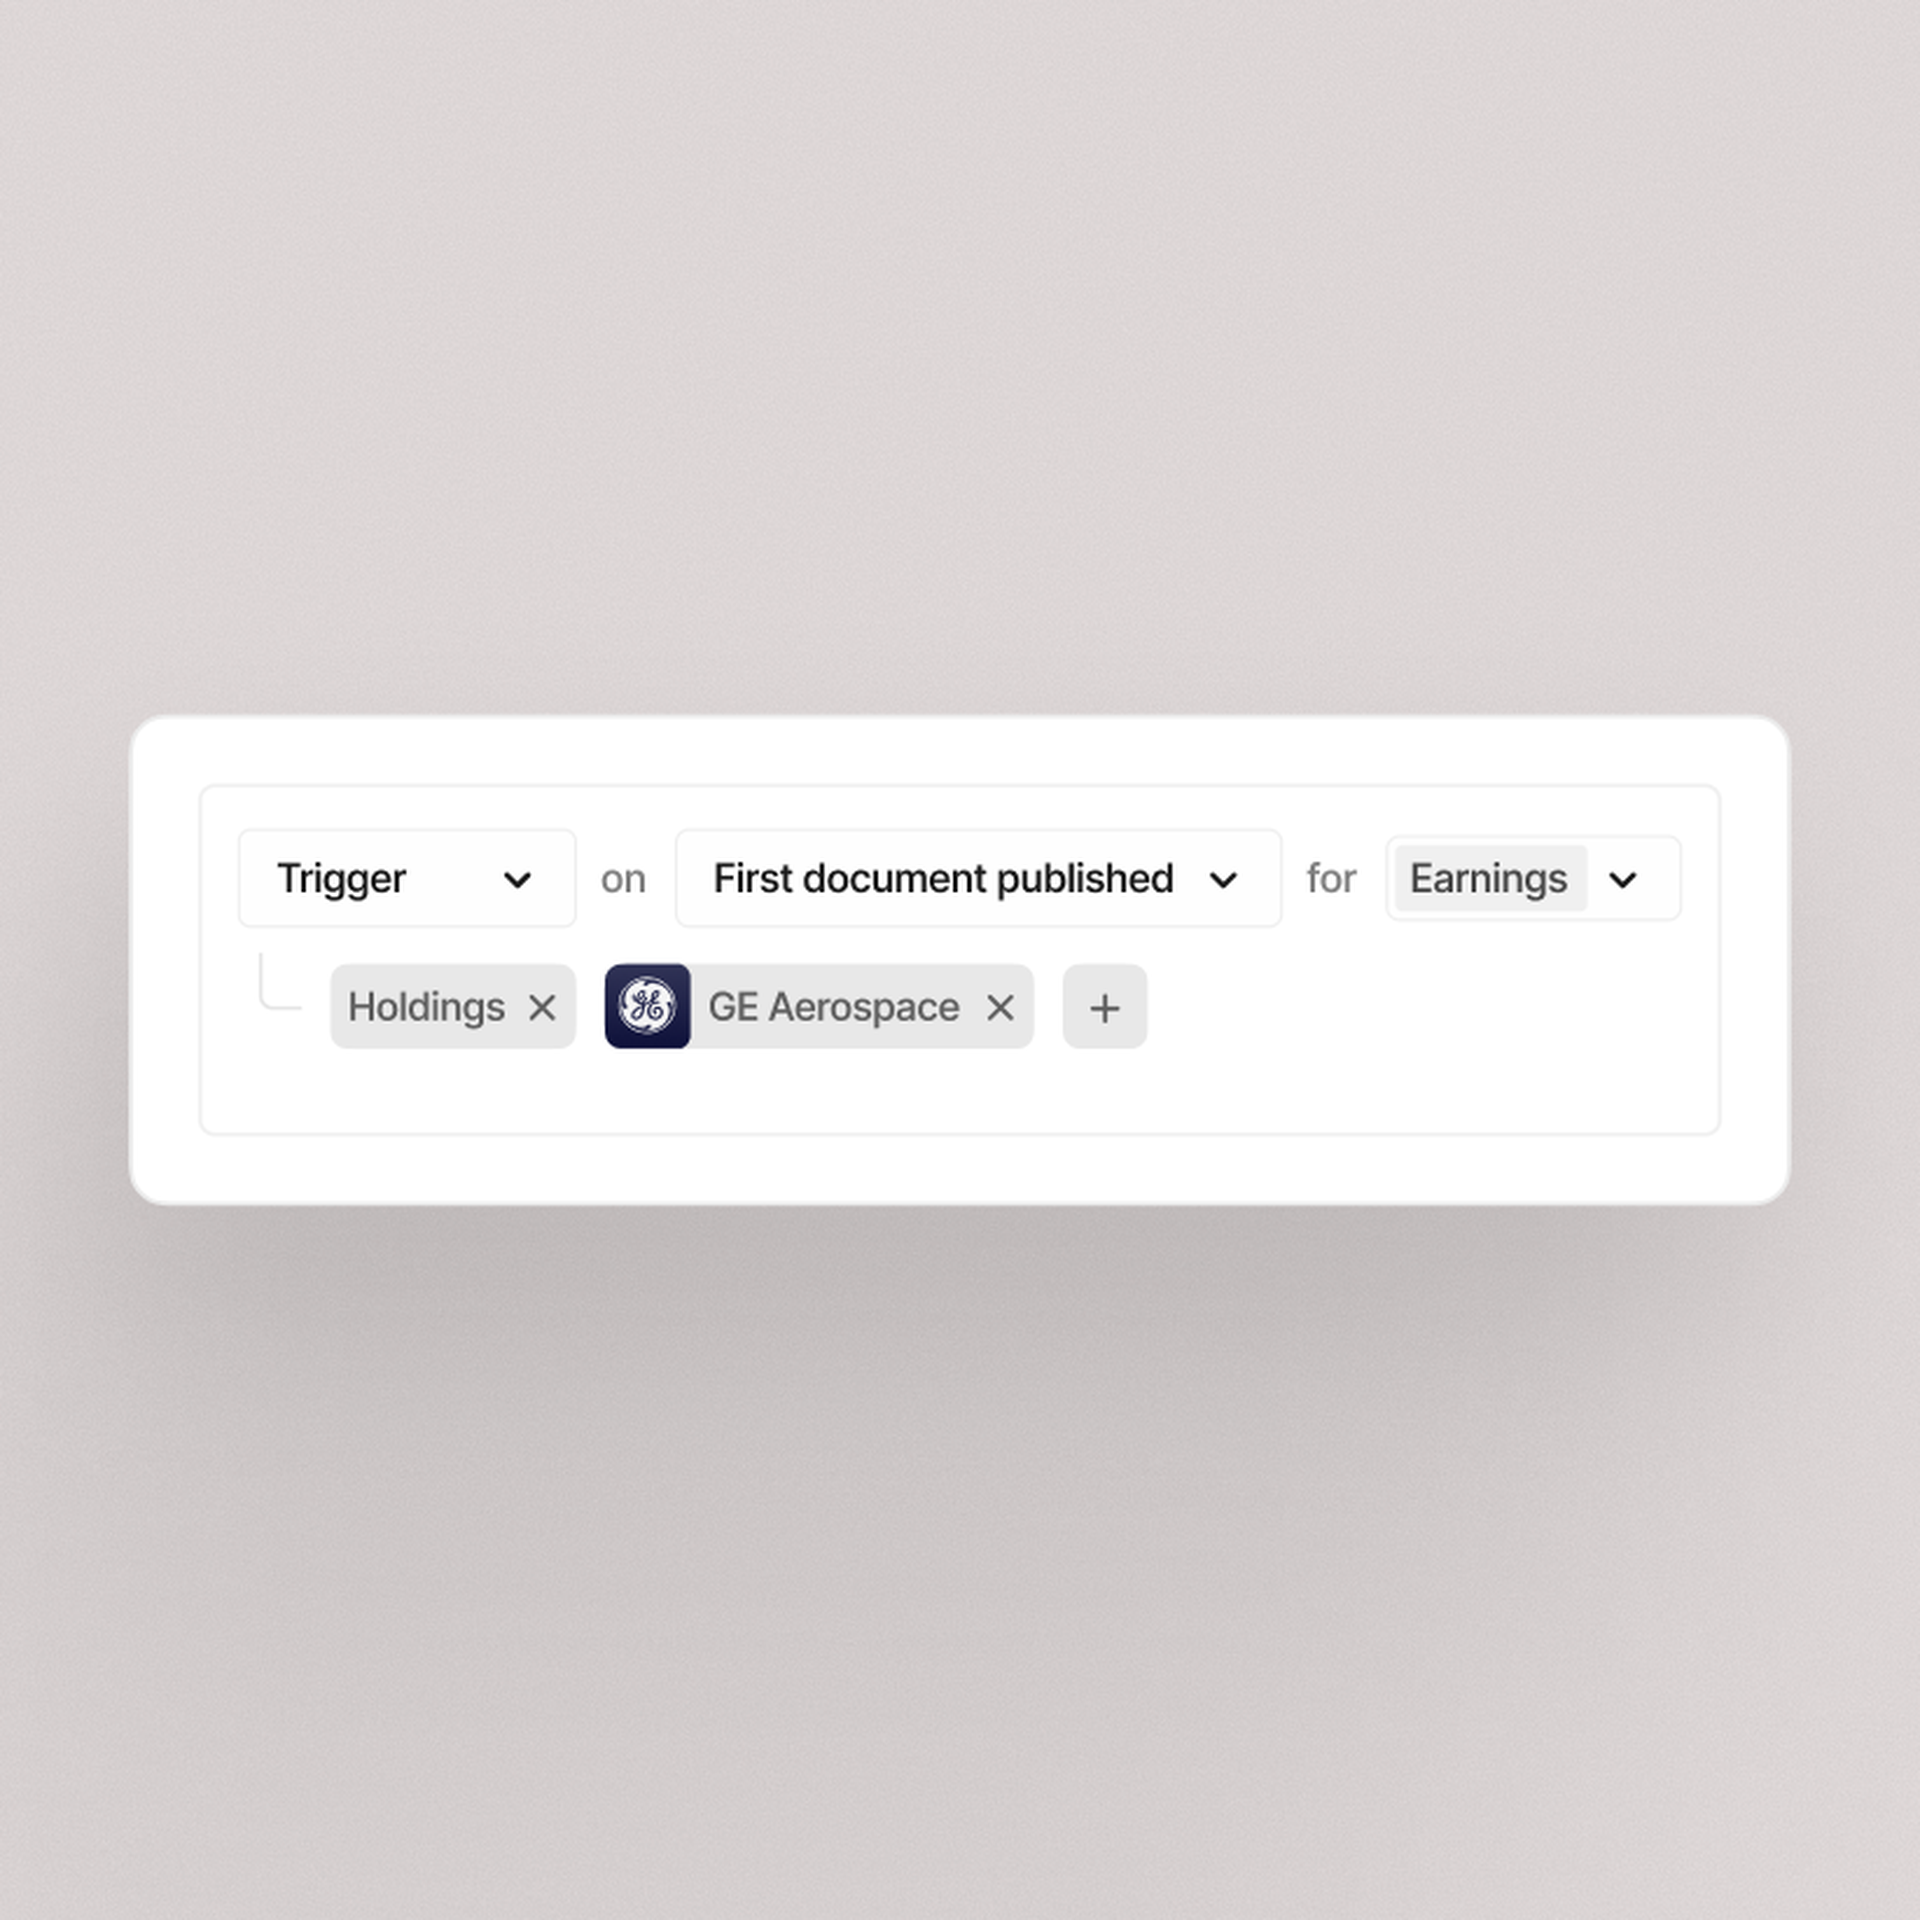
Automations
Live audio & transcripts
Quartr's AI stands out because it only pulls clean, first-party data from public companies. In investing, that's everything.
Jamie Ross
Investment Manager, GAM Investments
Research that used to take hours now takes seconds with Quartr Pro. Tracking shifts in tone or extracting tables, it's as simple as typing a query.
Tom O'Hara
Investment Director
Before Quartr we spent hours manually compiling insights through the peer earnings cycle. Now, these tasks are done faster, with greater precision.
Gregg Lampf
VP of Investor Relations
Being able to ask specific questions across years of transcripts and reports and instantly get verified answers is a game-changer.
Pontus Dackmo
CEO & Investment Manager
Fico is the most recognizable name in credit scores and the most widely used credit scoring system in the US. When using a credit scoring algorithm, 90 percent of top US lenders in 90 percent of lending decisions use Fico’s systems. And 98.8 percent of dollars securitized in the US solely cite Fico scores as risk measurement, 300 million consumer accounts have access to Fico scores, and one billion consumers could get credit through the scores. Fico is the industry standard for consumer credit lending decisions, and there are high barriers to entry for new companies that seek to replicate similar services. Some of the company’s competitors include Fiserv, Western Union, and Experian.
Fico’s sticky offering could be compared with getting Americans to start using the metric system or quoting temperature in Celsius. Fico is the low-cost producer of high accuracy scores; for example, it took Synchrony Financial three years to move away from using Fico. The company's fast-growing software business also has substantial switching costs. It becomes increasingly embedded in customer workflows, a software with over 90 percent retention rate and, thus, substantial amounts of recurring revenue.
The Fico score was introduced in 1989, and through the information found in the individual consumer's credit reports, the algorithm calculates credit scores for them. Lenders use these scores to evaluate the creditworthiness of their customers and thus determine whether to approve applications for loans, credit cards, and other borrowings.
As the creator and owner of the FICO credit-rating score with a world-class credit database, Fico checks many of the criteria when looking for a wide moat business:
High free cash flow
High return on capital employed
High return on equity
High operating margins